➢ Guidelines Under Sub-Section (4) of Section 194-O of the Income-Tax Act, 1961.
➢ CBDT has notified the ITR-6 for the Assessment Year 2024-25.
➢ CBDT has notified under Section 10(23FE) of the Income-Tax Act, 1961 – Exemption – Income of Specified Person from an Investment Made in India – Specified Pension Fund.
➢ CBDT has notified under Section 10(4G), read with section 80LA of the Income-tax act, 1961 – Exemption – Activity investment in a financial product by a non-resident under contract with capital market intermediary being a unit in IFSC.
➢ CBDT has notified under section 10(46) of the Income Tax Act, 1961 – Exemptions – Statutory Body/ Authority/ Board/ Commission – Notified Body or Authority.
➢ Extension of the due date of furnishing return in GSTR-3B for specified places.
➢ Furnishing of Annual Returns and self-certified reconciliation statements for registered persons of specified areas.
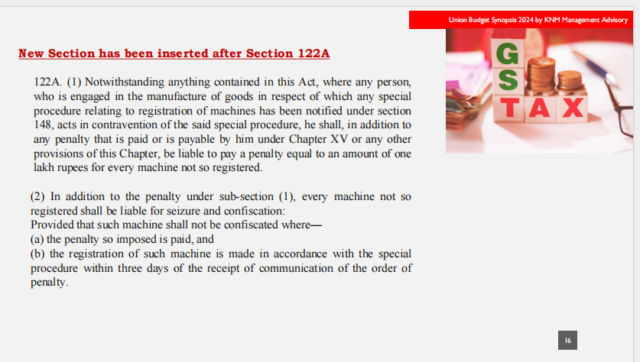
➢ Special Procedures for Certain Processes and Special Procedures to be followed by registered persons engaged in manufacturing notified goods.
➢ MCA notifies norms w.r.t listing of equity shares in IFSC by public companies.
➢ RBI issues updated master circular on exposure norms and statutory/other restrictions-UCBs.
➢ Govt. notifies accounting, taxation, & financial crime compliance services as ‘financial services’ under IFSCA Act`
➢ Govt. permits investment by ‘permissible holders’ in the equity of Indian public Cos.listed on international exchanges.
➢ Competition Commission of India (General) Amendment Regulations, 2024
➢ SEBI Streamlines regulatory reporting by Designated Depository Participants (DDPs) and Custodians through SI Portal
➢ SEBI Circular: New Framework for Employee Share Sale via Stock Exchange
CBDT has issued the guidelines under sub-section (4) of section 194-O of the Income Tax Act, 1961.
Central Board of Direct Taxes (Board) vide
Circular No. 20 of 2023 [F. NO. 370142/43/2023-TPL], dated 28-12-2023 has issued the guidelines on the above-mentioned subject.
Following are the guidelines:
(I) Who should deduct tax at the source where there are multiple e-commerce operators (ECO) involved in a transaction?
For example, a buyer-side ECO could be involved in buyer-side functions, and a seller-side ECO Involved in seller-side functions. In this case, there may be two situations:
a) Where the seller-side ECO is not the actual seller of the goods or services –
In this situation, the compliance is to be done by the seller-side ECO who finally makes the payment to the seller and the tax shall be deducted on the “gross amount” of such sales of goods or provision of services. The tax shall be deducted by the seller-side ECO at the time of credit to the account of a seller or at the time of payment, whichever is earlier.
b) Where the seller-side ECO is the actual seller of the goods or services.
In this situation, compliance is to be done by the ECO which finally makes the payment to the seller for goods or services sold, which in this case is ECO-2* and the tax shall be deducted on the gross amount of such sale of goods or provision of services and shall be deducted by ECO-2* at the time of credit or at the time of the payment, whichever is earlier.
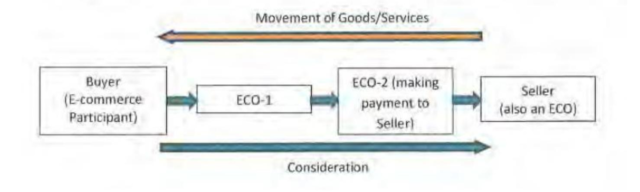
*For Situation (b)
(ii) E-Commerce Operator may levy convenience fees or charge commission for each transaction and the Seller might levy logistics & delivery fees for the transaction.
Payments may also be made to the platform or network provider to facilitate the transaction. Do the logistics charges, delivery fees, etc. form part of the gross amount for TDS Deduction under section 194O? Further, the buyer-side ECO and seller-side ECO may charge a commission to the seller to enable the online transaction, and the seller may choose to recoup all or part of that amount from the buyer.
(iii) Are GST, state levies, and taxes other than GST such as VAT treated when calculating the gross amount of sales of goods or provision of services for section 194O?
(iv) How will adjustment for purchase-returns take place?
(v) How will discounts given by the seller as an E-Commerce Participant or by any of the multiple ECOs be treated while calculating the ‘gross amount’ for section 194-O?`
➢ CBDT has notified the ITR-6 for the Assessment Year 2024-25.
CBDT has notified ITR6 for Assessment Year 2024-25 for filing returns for Financial Year 2023-24.
➢ CBDT has notified ITR-1 and ITR-4 for Assessment Year 2024-25
CBDT has notified ITR1 SAHAJ and ITR4 SUGAM for Assessment Year 2024-25 for filing returns for Financial Year 2023-24.
➢ CBDT has notified under Section 10(23FE) of the Income-Tax Act, 1961 –
Exemption – Income of Specified Person from an Investment Made in India –
Specified Pension Fund.
In exercise of the powers conferred by sub-clause (iv) of clause (c) of Explanation 1 to clause (23FE) of section 10 of the Income-tax Act, 1961 (43 of 1961) (hereinafter referred to as the Act), the Central Government hereby specifies the pension fund, namely, Ravenna Investments Holding B.V (PAN: AAMCR8596D), (hereinafter referred to as the assessee) as the specified person for the said clause in respect of the eligible investment made by it in India on or after the date of publication of this notification in the Official Gazette but on or before the 31st day of March 2024 (hereinafter referred to as the said investments) subject to the fulfillment of the following conditions, namely:-
➢ CBDT has notified under Section 10(4G), read with section 80LA of the Income-tax Act, 1961 – Exemption – Activity investment in a financial product by a non-resident under contract with a capital market intermediary being a unit in IFSC.
In exercise of the powers conferred by sub-clause (ii) of clause (4G) of section 10 of the Income-tax Act, 1961 (43 of 1961), the Central Government hereby notifies the activity of investment in a financial product by the non-resident, under a contract with such non-resident entered into by a capital market intermediary, being a Unit of an International Financial Services Centre, where the income from such investment is received in the account of the non-resident maintained with the Offshore Banking Unit of such International Financial Services Centre, as referred to in sub-section (1A) of section 80LA
Explanation. —For this notification —
➢ CBDT has notified under section 10(46) of the Income Tax Act, 1961 – Exemptions – Statutory Body/ Authority/ Board/ Commission – Notified Body or Authority
The Central Government has notified the following Statutory Body/ Authority/Board/ Commission for Section 10(46) subject to specified conditions for the years mentioned in the notification:
a) Karnataka State Rural Livelihood Promotion Society.
b) Polavaram Project Authority.
c) Madhya Professional Examination Board, Bhopal.
d) Punjab State Faculty of Ayurvedic and Unani Systems of Medicine.
e) Karmayogi Bharat.
f) Chennai Metropolitan Water Supply and Sewerage Board.
g) Haryana State Board of Technical Education, Panchkula.
h) District Legal Service Authority Union territory Chandigarh.
i) Bellary Urban Development Authority\
➢ Extension of Due date of furnishing return GSTR-3B for specified places –
As per Notification No. 1/2024-CENTRAL TAX Dated 05-01-2024, the government has extended the due date of furnishing the return in Form GSTR- 3B for November 2023 till the tenth day of January 2024 for the registered persons whose principal place of business is in the districts of Tirunelveli, Tenkasi, Kanyakumari, Thoothukudi and Virudhunagar in the state of Tamil Nadu. This notification shall come into force w.e.f. 20th day of December 2023
➢ Furnishing of Annual Returns and self-certified reconciliation statements for registered persons of specified areas –
As per Notification No. 2/2024- CENTRAL TAX- Dated 05-01-2024, the Central Government has made the following rules further to amend the Central Goods and ServicesTax Rules, 2017, namely: –
Short title and commencement
1. (1) These rules may be called the Central Goods and Services Tax (Amendment) Rules, 2024.
(2) They shall come into force on the 31st day of December 2023
2. In the Central Goods and Services Tax Rules, 2017, in rule 80, –
(a) after sub-rule (1A), the following sub-rule shall be inserted, namely: – (1B) Notwithstanding anything contained in sub-rule (1), for the financial year 2022-23, the said annual return shall be furnished on or before the tenth day of January 2024 for the registered persons whose principal place of business is in the districts of Chennai, Tiruvallur, Chengalpattu, Kancheepuram, Tirunelveli, Tenkasi, Kanyakumari, Thoothukudi and Virudhunagar in the state of Tamil Nadu.
(b) after sub-rule (3A), the following sub-rule shall be inserted, namely: – (3B) Notwithstanding anything contained in sub-rule (3), for the financial year 2022-23, the said self-certified reconciliation statement shall be furnished along with the said annual return on or before the tenth day of January 2024 for the registered persons whose principal place of business is in the districts of Chennai, Tiruvallur, Chengalpattu, Kancheepuram, Tirunelveli, Tenkasi, Kanyakumari, Thoothukudi and Virudhunagar in the state of Tamil Nadu.”
➢ Special Procedures for Certain Processes and Special Procedures to be followed by a registered person engaged in manufacturing notified good
As per Notification No. 4/2024- CENTRAL TAX- Dated 05-01-2024, Central Government has notified Special Procedures for Certain Processes and Special Procedures to be followed by a registered person engaged in manufacturing notified goods (Schedule includes Description of Goods like Pan Masala, Tobacco, Smoking mixtures for pipes and cigarettes, etc.), namely: –
1. Details of Packing Machines
(1) All the registered persons engaged in manufacturing the goods mentioned shall furnish the details of packing machines being used for filling and packing packages in FORM GST SRM-I, within thirty days of coming into effect of this notification.
(2) Any person intending to manufacture goods as mentioned in the Schedule to this notification, and who has been granted registration after the issuance of this notification, shall furnish the details of packing machines being used for filling and packing of packages in FORM GST SRM-I on the common portal, within fifteen days of grant of such registration.
(3) The details of any additional filling and packing machine being installed at the registered place of business shall be furnished, electronically on the common portal, by the said registered person within twenty-four hours of such installation in PART (B) of Table 6 of FORM GST SRM-I.
(4) If any change is to be made to the declared capacity of the machines, the same shall be furnished, electronically on the common portal, by the said registered person within twenty-four hours of such change in Table 6A of FORM GST SRM-I.
(5) Upon furnishing of such details in FORM GST SRM-I, a unique registration number shall be generated for each machine, the details of which have been furnished by the registered person, on the common portal.
(6) In case, the said registered person has submitted or declared the production capacity of his manufacturing unit or his machines, to any other government department or any other agency or organization, the same shall be furnished by the said registered person in Table 7 of FORM GST SRM-I on the common portal, within fifteen days of filing such declaration or submission:
Provided that where the said registered person has submitted or declared the production the capacity of his manufacturing unit or his machines, to any other government department or any other agency or organization, before the issuance of this notification, the latest such certificate in respect of the manufacturing unit or the machines, as the case may be, shall be furnished by the said registered person in Table 7 of FORM GST SRM-I on the common portal, within thirty days of issuance of this notification.
(7) The details of any existing filling and packing machine disposed of from the registered place of business shall be furnished, electronically on the common portal, by the said registered person within twenty-four hours of such disposal in Table 8 of FORM GST SRM-I
2. Special Monthly Statement
The registered person shall submit a special statement for each month in FORM GST SRM-II, electronically on the common portal, on or before the tenth day of the month succeeding such month.
3. Certificate of Chartered Engineer
(1) The taxpayer shall upload a certificate of Chartered Engineer FORM GST SRM-III in respect of machines declared by him, as per para 1 of this notification, in Table 6 of FORM GST SRM-I.
(2) If details of any machine are amended subsequently, then a fresh certificate in respect of such machine shall be uploaded.
4. This notification shall come into effect from the 1st day of April 2024.
➢ MCA notifies norms w.r.t listing of equity shares in IFSC by public companies.
The Companies (Listing of equity shares in permissible jurisdictions) Rules, 2024, introduced by the Ministry of Corporate Affairs (MCA), marks a significant step towards enabling unlisted and listed public companies to issue securities for listing on approved stock exchanges in permissible foreign jurisdictions.
These regulations provide clarity on eligibility criteria, listing requirements, and reporting obligations, fostering transparency and compliance within the international financial landscape.
➢ RBI issues updated master circular on exposure norms and statutory/other restrictions-UCBs.
RBI issues a master circular consolidating all the instructions/guidelines on exposure norms and statutory/other restrictions related to the (urban) cooperative banks UCBs. Now users can refer to the consolidated master circular, consolidating different circulars in one place.
➢ Govt. notifies accounting, taxation, & financial crime compliance services as ‘financial services’ under the IFSCA Act
The RBI has notified amendment sub-clause (xiv) of clause (e) of sub-section (1) of section 3 of the International Financial Services Centres Authority Act, 2019 (50 of 2019), the Central Government hereby notifies the following as financial services, namely: —
➢ Govt. permits investment by ‘permissible holders’ in the equity of Indian public Cos. listed on international exchanges
The Ministry of Finance vide. Notification No. S.O. 332(E) dated 24.01.2024 has notified the Foreign Exchange Management (Non-debt Instruments) Amendment Rules, 2024. A new Rule 34 in chapter X has been inserted which permits the Investment by permissible holders in Equity Shares of Public Companies Incorporated in India and Listed on International Exchanges.
➢ Competition Commission of India (General) Amendment Regulations, 2024
In the Competition Commission of India (General) Regulations, 2009, regulation 49,
after sub-regulation
(1) the following sub-regulation shall be inserted, namely:
(1A) Each Interlocutory Application received under sub-regulation (6) of Regulation 15 shall be accompanied by proof of having paid the fee as under: –
(a) Rupees 500 (five hundred) in case of individual or Hindu Undivided Family (HUF), or
(b) Rupees 1000 (one thousand) in case of a Non-Government Organization (NGO), or Consumer Association, or Co-operative Society, or Trust or
(c) Rupees 1000 (one thousand) in case of firm (including proprietorship, partnership or Limited Liability Partnership) or company (including one person company) having turnover in the preceding year up to rupees two crore, or
(d) Rupees 5000 (five thousand) in all other cases.”
➢ SEBI Streamlines regulatory reporting by Designated Depository Participants (DDPs) and Custodians through SI Portal
The Securities and Exchange Board of India (SEBI) has recently issued a circular, SEBI/HO/AFD/AFD-SEC-2/P/CIR/2024/8, dated January 25, 2024. The circular focuses on streamlining regulatory reporting by Designated Depository Participants (DDPs) and Custodians. The objective is to establish uniform compliance standards, enhance ease of reporting, and meet regulatory requirements.
➢ SEBI Circular: New Framework for Employee Share Sale via Stock Exchange
The Securities and Exchange Board of India (SEBI) has issued a circular, SEBI/HO/MRD/MRD-PoD-3/P/CIR/2024/6, dated January 23, 2024. This circular introduces a new framework for the Offer for Sale (OFS) of shares to employees through the stock exchange mechanism. The purpose is to streamline the existing process, enhance efficiency, and reduce costs associated with the current procedure.
Disclaimer: Information in this note is intended to provide only a general update on the subjects covered. It is not intended to be a substitute for detailed research or the exercise of professional judgment. KNM accepts no responsibility for loss arising from any action taken or not taken by anyone using this publication. Updates are for the period 25.01.2024.
CBDT extends the Time Limit for processing validly filed income tax returns with refund claims up to assessment year 2017-18 until January 31, 2024.
➢ Guidelines Prescribed by CBDT for withholding Tax u/s 194-O.
➢ CBDT has notified ITR-1 and ITR-4 for Assessment Year 2024-25
➢ Central Government notifies Godavari River Management Board of Hyderabad for exemption in exercise of the powers conferred by clause (46) of section 10 of the Income-tax Act, 1961.
➢ Sovereign Gold Bond Scheme 2023-24 (Series III) will be opened for subscription during the period December 18-22, 2023.
➢ PowerGrid Infrastructure Investment Trust to be recognized as a mode for continuity of tax exemption for Charitable Trust and Institution
➢ The CBDT vide Notification No. 106/2023 dated December 27, 2023, notified an exemption to Ravenna Investments Holding B.V for pension funds under section 10(23FE) of the Income Tax Act, 1961.
➢ The government has revised the rate of Interest for the Small Savings Scheme with the approval of the competent authority.
➢ CBDT has notified the Income-tax (Twenty-Ninth Amendment) Rules, 2023, to amend Rules 10TA and 10TD for revising the definition of intra-group loans and circumstances in which they are treated as Safe Harbour.
➢ Extension of due date of GSTR 3B for the month of November 2023.
➢ Government issued time limit for issuing order under sec 73.
➢ GSTN issues advisory for pilot project of biometric-based Aadhaar authentication and document verification
➢ Advisory related to amnesty for taxpayer who missed to file appeal for the order passed on or before 31st march 2023.
➢ GSTN has given advisory on Two factor authentication (2FA).
➢ Mandatory Pre-Requisite For E-filing Matters in NCLT
➢ Foreign Exchange Management (Manner of Receipt and Payment) Regulations, 2023
➢ RBI modifies MSME lending norms
➢ RBI issues revised instructions for inoperative accounts/unclaimed deposits in Banks
➢ Employees’ State Insurance (Central) Amendment Rules, 2023
➢ Filing of Announcements Related to Loss of Share Certificate, Issue of Duplicate Share, Certificate Closure of Trading Window and CIRP- NSE
➢ SEBI (Listing Obligations and Disclosure Requirements) (Seventh Amendment) Regulations, 2023
➢ SEBI (Issue of Capital and Disclosure Requirements) (Third Amendment) Regulations, 2023
➢ CBDT extends the Time Limit for Processing Validly Filed Income Tax Returns with Refund Claims up to Assessment Year 2017-18 until January 31, 2024
Central Board of Direct Taxes (Board) vide its order under section 119 of the Income-tax Act,1961 dated July 05, 2021 and September 30, 2021 on the captioned subject relaxed the timeframe prescribed in second proviso to subsection (1) of Section 143 of the Act. It was directed that all validly filed returns up to Assessment Year 2017-18 with refund claims, which could not be processed under section 143(1) of the Act and which had become time barred, should be processed by November 30, 2021, subject to the conditions exceptions specified therein.
The matter has been re-considered by Board in view of pending taxpayer grievances related to issue of refund. To mitigate the genuine hardship being faced by the taxpayers on this issue, Board, by virtue of its power under section 119 of the Act and in partial modification of its earlier order under section 119 of the Act dated July 05, 2021 and September 30, 2021, supra, hereby further extends the time frame mentioned in the para no. 2 of the order dated September 30, 2021 till January 31, 2024 in respect of returns of income validly filed electronically. All other contents of the said order u/s 119 of the Act dated July 05, 2021 will remain unchanged.
Above relaxation shall not be applicable to the following returns:
(i) returns selected in scrutiny
(ii) returns remain unprocessed, where either demand is shown as payable in the return or is likely to arise after processing it
(iii) returns remain unprocessed for any reason attributable to the assessee.
➢ Guidelines Prescribed by CBDT for withholding Tax u/s 194-O.
The guidelines contemplate following situations and explains in detail how section 194- O would operate in such cases, including illustrations.
• In case of a platform or network ( e.g., the open network for digital commerce) wherein multiple ECOs are participating in a single transaction of sale of goods / services through the platform / network. For example, there could be a buyer side ECO involved in buyer side functions and a seller side ECO involved in seller side functions.
Example 1 – Where the seller-side ECO is not the actual seller of goods / services. In this situation, withholding of tax u/s 194-O is required to be done by the seller side ECO who finally makes the payment to the seller. The seller-side ECO would file the requisite withholding tax return in Form 26Q and issue certificate to the seller in Form 16A.
Example 2 – Where the seller-side ECO is the actual seller of goods / services. In this situation, withholding of tax u/s 194-O is required to be done by the ECO which finally makes the payment to the seller for goods / services sold, which in the case mentioned below is ECO-2. The ECO 2 would file the requisite withholding tax return in Form 26Q and issue certificate to the seller in Form 16.
• ECOs may be levying convenience fees or charging commission for each transaction and seller might levy logistics and delivery fees for the transaction. Payments may also be made to the platform or network provider for facilitating the transaction. Whether these would form part of ‘gross amount’ for the purpose of withholding tax u/s 194-O of the Act?
• How will GST, various state levies and taxes other than GST (such as Value Added Tax / Sales tax / Excise duty / Central Sales Tax) be treated when calculating ‘gross amount’ of sale for the purpose of section 194-O?
• How will adjustment for purchase -returns take place?
• How will discounts given by seller as an E -Commerce Participant or by any of the multiple ECOs be treated while calculating ‘gross amount’ for the purpose of section 194-O?
➢ CBDT has notified ITR-1 and ITR-4 for Assessment Year 2024-25
CBDT has notified ITR1 SAHAJ and ITR4 SUGAM for Assessment Year 2024-25 for filing return for Financial Year 2023-24.
➢ Central Government notifies Godavari River Management Board of Hyderabad for exemption in exercise of the powers conferred by clause (46) of section 10 of the Income-tax Act, 1961.
Central Government in pursuance of section 85 of the Andhra Pradesh Re-Organization Act, 2014, in respect of the following specified income arising to the said Authority, as follows:
(a) Grants/Subsidies received from CG and from the SG of Andhra Pradesh and Telangana and
(b) Interest from bank deposits, including savings account.
Above notification shall be effective subject to the conditions that Godavari River Management Board, Hyderabad-
(a) shall not engage in any commercial activity;
(b) activities and the nature of the specified income shall remain unchanged throughout the financial years; and
(c) shall file return of income in accordance with the provision of clause (g) of sub- section (4C) of section 139 of the Income-tax Act, 1961.
This notification shall be deemed to have been applied for assessment years 2020-21 to 2023-2024.
➢ Sovereign Gold Bond Scheme 2023-24 (Series III) will be opened for subscription during the period December 18-22, 2023.
The Gold Bonds issued under this Scheme may be held by a Trust, HUFs, Charitable Institution, University or by a person resident in India, being an individual, in his capacity as such individual, or on behalf of minor child, or jointly with any other individual.
The issue price of the Bond during the subscription period shall be ₹6,199 per gram . The Government of India in consultation with the Reserve Bank of India has decided to allow discount of ₹50 per gram from the issue price to those investors who apply online and the payment is made through digital mode. For such investors the issue price of Gold Bond will be ₹6,149 per gram of gold.
Interest on the Gold Bonds shall commence from the date of issue and shall be paid at a
fixed rate of 2.50 percent per annum on the nominal value of the bond and the interest shall be payable in half-yearly rests and the last interest shall be payable along with the principal on maturity and these Gold Bonds shall be repayable on the expiration of eight years from the date of the issue of the Bonds.
➢ PowerGrid Infrastructure Investment Trust to be recognized as a mode for continuity of tax exemption for Charitable Trust and Institution
Charitable Trusts / Institutions enjoying Income-tax exemption u/s 11(5) of the Income- tax Act are required to invest their surplus funds in prescribed modes, such as savings certificates, post office savings, deposit in an account with a scheduled bank or co- operative society, units of Unit Trust of India, deposit in any public sector company of India, etc. the CBDT has added investment in units of PowerGrid Infrastructure Investment Trust as one of the recognised modes for continuity of tax exemption for such trusts / institutions.
➢ The CBDT vide Notification No. 106/2023 dated December 27, 2023, notified an exemption to Ravenna Investments Holding B.V for pension funds under section 10(23FE) of the Income Tax Act, 1961.
The notified funds are eligible to claim an exemption for eligible investments made in India on or before March 31, 2024, subject to following conditions.
i. The assessee shall file a return of income, for all the relevant previous years falling within the period beginning from the date in which the said investment has been made and ending on the date on which such investment is liquidated.
ii. the assessee shall furnish along with such return a certificate in Form No. 10BBC in respect of compliance with the provisions of clause (23FE) of section 10 of the Act.
iii. the assessee shall intimate the details in respect of each investment made by it in India during the quarter within a period of one month from the end of the quarter in Form No. 10BBB.
iv. the assessee shall maintain a segmented account of income and expenditure in respect of such investment which qualifies for exemption under clause (23FE) of section 10 of the Act;
v. the assessee shall continue to be regulated under the laws of the Government of the Netherlands;
vi. the assessee shall not have any loans or borrowings directly or indirectly, for the purposes of making investment in India and
vii. the assessee shall not participate in the day-to-day operations of investee but the monitoring mechanism to protect the investment with the investee shall not be considered as participation in the day-to-day operations of the investee and
viii. any other conditions as may be prescribed.
Violation of any of the conditions as stipulated in clause (23FE) of section 10 of the Act and this notification shall render the assessee ineligible for the tax exemption.
➢ Government has revised the rate of Interest for Small Savings Scheme with the approval of competent authority.
The rates of interest on various Small Savings Schemes for the fourth quarter of financial year 2023-24 starting from 1 st January, 2024 and ending on 31 st March, 2024 have been revised as detailed below:
➢ CBDT has notified the Income-tax (Twenty-Ninth Amendment) Rules, 2023, to amend Rules 10TA and 10TD for revising the definition of intra-group loans and circumstances in which they are treated as Safe Harbour.
Intra-group loan definition has been revised to include loans extended to “Associate Enterprise” rather than wholly owned subsidiaries and the condition for the loans to be advanced must be sourced in Indian Rupees has been omitted. The updated definition of intra-group loan is now stated as follows:
Intra-group loan means a loan advanced to an associated enterprise being a non-resident, where the loan
(i) is not advanced by an enterprise, being a financial company including a bank or a financial institution or an enterprise engaged in lending or borrowing in the normal course of business, and
(ii) does not include a credit line or any other loan facility which has no fixed term for repayment;
Rule 10TD has been amended to replace the conditions for safe harbor in the event of the advancement of intra-group loans denominated in a foreign currency. The reference to “CRISIL” credit rating has been omitted from Rule 10TD. Thus, the credit rating of any other entities can be used while determining Safe Harbour.
➢ As per Notification No. 56/2023 Dated 28 th December, 2023 – The Government, on the recommendations of the Council, hereby, extends the time limit specified under sub- section (10) of section 73 for issuance of order under sub-section (9) of section 73 of the said Act, for recovery of tax not paid or short paid or of input tax credit wrongly availed or utilized, relating to the period as specified below, namely: –
• For the financial year 2018-19, up to the 30th day of April, 2024;
• For the financial year 2019-20, up to the 31st day of August, 2024
➢ As per Notification NO. 55/2023 Dated 20 th December, 2023
The Commissioner, on the recommendations of the Council, hereby extends the due date for furnishing the return in FORM GSTR-3B for the month of November, 2023 till the twenty-seventh day of December, 2023, for the registered persons whose principal place of business is in the districts of Chennai, Tiruvallur, Chengalpattu and Kancheepuram in the state of Tamil Nadu
.
➢ The GSTN on has issued an advisory 1 st December 2023 for applicants of GST registration in the state of Andhra Pradesh, for pilot project of biometric-based Aadhaar authentication and document verification.
The functionality now also provides for the document verification and appointment booking process Once the applicant has applied to Form GST REG- 01, it will receive an email either of the following:
• A link for OTP based Aadhaar authentication, or
• A link for booking an appointment with GST Suvidha Kendra (GSK) for authentication/verification
If the applicant receives the link for OTP-based Aadhaar authentication as per above,
He/she can proceed with the application as per the existing process. however, If the applicant receives the link for booking appointment with GSK, he / she will be required to book the appointment to visit the designated GSK, using the link provided in the e-mail. Once the applicant gets the confirmation of appointment through e-mail, he / she will be able to visit the designated GSK as per the chosen schedule.
At the time of the visit of GSK, the applicant is required to carry the following details.
• Copy of confirmation e -mail (for booking of appointment)
• Details of jurisdiction as mentioned in the e -mail
• Aadhaar number
• Original documents that were uploaded with the application. The biometric authentication and document verification will be done at the GSK, for the individuals as per the GST application Form REG-01.
➢ The GSTN has issued the following advisory on 28 November 2023 the GST Council, in its 52nd meeting held in October 2023, recommended granting amnesty to taxpayers who could not file an appeal (u/s 107 of the CGST Act, 2017), against the demand order (u/s 73 or 74 of the CGST Act, 2017) passed on or before March 31, 2023, or whose appeal against the said order was rejected due to not being filed within the specified time limit.
• In compliance with this recommendation the government has issued notification No. 53/2023 on November 2, 2023.
• Considering the pre-requisite to deposit the admitted amount of tax, interest and penalty, it is the responsibility of the taxpayer to select the appropriate ledgers and make the payment correctly (the GST portal allows taxpayers to choose the correct mode of payment – electronic credit / cash ledger). An appeal filed without proper payment of tax, interest or penalty, may be rejected or dealt with as per the legal provisions
• In case taxpayer has already filed an appeal and wants it to be covered by the benefit of amnesty scheme, it would be required to make the differential payment to comply with Notification no. 53/2023. The payment should be made against the demand order using the ‘Payment towards demand’ facility available on the GST portal. The navigation step for making this payment is: Login >> Services >> Ledgers >> Payment towards Demand.
• Taxpayers who have previously filed an appeal, but it was rejected as time barred in APL-02 by the appellate authority, are entitled to refile the appeal. In case taxpayer faces any issue in re-filing of appeal, a ticket shall be raised on the grievance redressal portal (https://selfservice.gstsystem.in). The taxpayer shall select the category ‘Amnesty Scheme’ and the sub-category ‘Amnesty scheme- Issue in appeal filing’ while raising a ticket.
• If the appellate authority has issued a rejection order in APL-04 due to the application for appeal being time-barred, the taxpayer has to approach the respective appellate authority office well in advance to comply with the dates in the said notification. The appellate authority after checking the eligibility of the taxpayer for the amnesty scheme will forward the case to GSTN through the state nodal officer.
• For the APL 04 issued cases, no direct representations will be entertained by GSTN or through the grievance redressal portal. APL 04-issued cases have to be compulsorily forwarded through the state nodal officer.
• Post receiving the case from the state nodal officer, GSTN will enable the taxpayer to file an appeal against the concerned order.
➢ GSTN has issued an advisory on 1 December 2023 for implementation of 2FA on the GST portal nationwide starting 1 December 2023 onwards.
The 2FA helps in strengthening the login security in the GST portal. The initial rollout of 2FA has been successfully conducted in Haryana. In the 1st phase, 2FA will be implemented in Punjab, Chandigarh, Uttarakhand, Rajasthan and Delhi. The 2nd phase will include the remaining states across India. Taxpayers would need to provide a one-time password (OTP) post entering user ID and password. The OTP will be delivered to the primary authorized signatory’s mobile phone number and email address. Accordingly, taxpayers have been advised to keep their email addresses and mobile numbers of authorized signatories updated on the GST portal for receiving the OTP communication.
➢ Mandatory Pre-Requisite For E-filing Matters in NCLT
The National Company Law Tribunal has informed that all Litigants/Advocates/parties have to follow the pre-requisite outline on formatting, proper book marking Petition/Applications/Pleadings/Documents, electronic signature using e-sign, retention of originals, etc. at the time of e-filing in NCLT portal with effect from January 01, 2024.
➢ Foreign Exchange Management (Manner of Receipt and Payment) Regulations, 2023
The Reserve Bank of India has introduced Foreign Exchange Management (Manner of Receipt and Payment) Regulations, 2023 in supersession of Notification No. FEMA 14(R)/2016-RB dated May 02, 2016.
The core of the regulations addresses how residents in India can make or receive payments from individuals outside the country. It emphasizes the role of Authorised Banks and Authorised Persons. The provision allows residents to seek the Reserve Bank’s permission for specific transactions under the Act.
➢ RBI modifies MSME lending norms
The RBI has notified amendment in Paragraph 2.2 of the Master Direction- Lending to Micro, Small & Medium Enterprises (MSME) Sector. Now, it has been directed that for Priority Sector Lending (PSL) purposes, banks shall be guided by the classification recorded in the Udyam Registration Certificate (URC). All the MSMEs are required to register online on the Udyam Registration portal and obtain a ‘Udyam Registration Certificate’.
➢ RBI issues revised instructions for inoperative accounts/unclaimed deposits in Banks
The RBI issued revised guidelines w.r.t. inoperative accounts /unclaimed deposits in banks. The central banks called for steps to trace the customers of inoperative accounts or unclaimed deposits including their nominees or legal heirs for re-activation of accounts, settlement of claims, or closure. RBI also stressed a periodic review and measures to prevent fraud in such accounts. No charges must be levied for the activation of inoperative accounts.
➢ Employees’ State Insurance (Central) Amendment Rules, 2023
The Ministry of Labour of Employment has issued a notification to further amend Employees’ State Insurance (Central) Rules, 1950 wherein, in Rule 29(2) Proviso, for the words “rupees five crores”, the words “rupees twenty–five crores” shall be substituted.
SEBI
➢ Filing of Announcements Related to Loss of Share Certificate, Issue of Duplicate Share, Certificate Closure of Trading Window, and CIRP- NSE
The National Stock Exchange of India has advised the listed entity to file the disclosures intimating the following announcements under SEBI (Listing Obligations and Disclosure Requirements) Regulations, 2015 (‘SEBI LODR’) will be made available in XBRL format. with from December 09, 2023:
1. Loss of Share Certificate/Issue of Duplicate Share Certificate
2. Closure of Trading Window
3. Corporate Insolvency Resolution Process.
➢ SEBI (Listing Obligations and Disclosure Requirements) (Seventh Amendment) Regulations, 2023
The Securities and Exchange Board of India has amended the Securities and Exchange Board of India (Listing Obligations and Disclosure Requirements) Regulations, 2015.
➢ SEBI (Issue of Capital and Disclosure Requirements) (Third Amendment) Regulations, 2023
The Securities and Exchange Board of India has amended the Securities and Exchange Board of India (Issue of Capital and Disclosure Requirements) Regulations, 2018.
CBDT has introduced certain changes in Form ITR-7, to accommodate the taxable income of individuals under the tax rates applicable to AOP, which aligns with the slab rates applicable to individuals. The amendment is applicable from Assessment Year (AY) 2023-24 onwards.
(a) Changes in Part B- TI: Sl No. 16 to be substituted as below:
(b) in Part B-TTI, against serial number 1, for item a and entries relating thereto, the following item and entered thereto, shall be substituted, namely: —
“a Tax at normal rates on [Sl. No. 17 of Part B1 of Part B-TI] OR [Sl. No. (13 -14) of Part B2 of Part B-TI] OR [Sl. No. 13 of Part B3 of Part B-TI] 1a”.
Telecom operators at the time of set-up of telecom infrastructure incur two types of license fees – Fixed and Variable. The fixed license fee is a one-time fee paid to acquire the right to operate the telecommunication services. Variable license fees are paid annually as a percentage of gross revenue. As per section 35ABB of the Income-tax Act, payments made for acquiring any right to operate telecommunication services (whether such payment is made before the commencement of the business to operate or thereafter at any time during the year) will be allowed as a tax deduction in amortized manner.
Supreme Court invoked the test of ‘nature of original obligation’ to determine the nature of the variable annual license fee, and held that while classifying the nature of the expense, it is important to analyze whether the subsequent payment made in installments has a direct nexus with the original obligation or not. In the instant case, the successive payment of a variable annual license fee has a nexus with the original obligation, i.e. consideration for the right to establish, maintain, and operate telecommunications services. The nature of payment that was made for the same purpose cannot have a different characterization merely because of a change in the manner of payment.
In view of the above, the one-time entry fee as well as the variable annual license fee paid by the taxpayer are capital in nature and will be amortized under section 35ABB of the Act.
The notified funds shall be eligible to claim the exemption in respect of eligible investment made in India on or before 31-03-2024 subject to prescribed conditions. Some of them are
(i) The assessee shall file a return of income, for all the relevant previous years falling within the period beginning from the date in which the said investment has been made and ending on the date on which such investment is liquidated, on or before the due date specified for furnishing the return of income under sub-section (1) of section 139 of the Act;
(ii) the assessee shall furnish along with such return a certificate in Form No. 10BBC in respect of compliance to the provisions of clause (23FE) of section 10 of the Act, during the financial year, from an accountant as defined in the Explanation below sub-section.
(2) of section 288 of the Act, as per the provisions of clause (vi) of rule 2DB of the income-tax Rules, 1962;
(iii) the assessee shall intimate the details in respect of each investment made by it in India during the quarter within one month from the end of the quarter in Form No. 10BBB, as per the provisions of clause (v) of rule 2DB of the Income-tax Rules, 1962;
(iv) The assessee shall maintain a segmented account of income and expenditure in respect of such investment which qualifies for exemption under clause (23FE) of section 10 of the Act;
(v) The assessee shall continue to be regulated under the law of the Government of Ontario, Canada; and any other conditions as prescribed.
The monetary limit for applying provisions of section 245(2) of the Income-tax Act, 1961 will hereinafter be where the value of the refund is Rs. 10 lakhs or more. In any case where section 245(2) of the Act is applicable, the Faceless Assessing Officer (FAO), on receipt of communication from CPC, shall intimate the Jurisdictional Assessing Officer (JAO) about demand likely to be raised in the pending assessment(s). The JAO, based on such information shall record in writing, with proper application of mind, and after analyzing the factual matrix of the case seek approval of the jurisdictional Principal Commissioner of Income-tax. The reasons recorded shall not be cursory. Such reasons should reflect the factual analysis of the case by the JAO. The JAO will communicate the final decision regarding the release of the refund to the CPC. To finish this process, the time limit is hereby revised to 20 days for the Faceless Assessment Unit and to 30 days for Jurisdictional Assessing Officer.
(i) Retirement benefits may now be invested in the SCSS within three months of retirement for a retired person who is over 55 but under 60. Formerly, after receiving retirement benefits, a retired person had to invest within a month.
(ii) The financial aid amount may now be invested in the program by a spouse of a government employee who passed away while performing their duties. If the deceased government employee was employed and reached the age of fifty, then this will be permitted. This benefit is being given to all central and state government employees eligible for retirement benefits or death compensation.
(iii) As per changes defined, Retirement benefit means any payment due to the account holder on account of retirement on superannuation or otherwise and includes Provident Fund dues, retirement or superannuation or death gratuity, commuted value of pension, cash equivalent of leave, savings element of Group Savings Linked Insurance Scheme payable by the employer on retirement, retirement-cum-withdrawal benefit under the Employees’ Family Pension Scheme and ex-gratia payments under a voluntary or a special voluntary retirement scheme and in case, if the employee dies in harness, the “retirement benefits” shall also mean the above-mentioned benefits to an employee who died in harness.
(iv)According to the new regulations, if the account is closed before the investment’s one-year term expires, one percent of the deposit will be withheld. Prior regulations stated that interest on the account’s deposit should be recouped from the deposit and the account holder would receive the whole amount if the account was closed before a year had passed.
(v) The account holder may keep extending the account for an unlimited number of blocks, each lasting three years. Furthermore, for each extension, the application must be submitted. The extension could only be granted once in the past. Regardless of when the application was received, the extension shall be taken into consideration as of the date of maturity or the conclusion of each three-year block term.
(vi)The deposit made at the time of opening of the account shall be paid on or after the expiry of five years or after the expiry of each block period of three years where the account was extended from the date of opening of the account. Provided that after the closure of the existing account or accounts, new accounts or accounts may be opened again as required by the depositor subject to the maximum deposit limit.
In the exercise of the powers conferred by section 3A of the Government Savings Promotion Act, the Central Government substituted Paragraph 8 regarding the Premature closure of the account. Premature closure of an account shall be allowed on an application by the account holder in
Form-4 is subject to the following conditions, namely:—
Account for the completed months;
c) where a deposit in a two-year or three-year account is withdrawn prematurely after the expiry of one year from the date of deposit, interest on such deposit shall be payable to the account holder for the completed years and months, commencing on the date of deposit and ending with the date of withdrawal, and such interest shall be calculated at the rate which shall be less by two percent. points than the rate specified for a deposit of one year or two, as the case may be, and interest for the completed year shall be calculated on the quarterly compounding basis per the provisions of paragraph 7, and for any part of a year, interest shall be payable as per the provisions of subparagraph (b);
d) Where a deposit in a five-year account is withdrawn prematurely after four years from the date of opening of an account, interest shall be payable at the rate applicable to Post Office Savings Account; and
e) any interest already paid on the deposit under paragraph 7 shall be recovered from the amount of repayment of the deposit and the interest payable under this paragraph.
In exercise of the powers conferred by section 3A of the Government Savings Promotion Act, 1873, the Central Government hereby makes a Scheme to further amend the Public Provident Fund Scheme, 2019, in paragraph 13, in the second proviso, for the words “or the date of extension of the account”, the words “or from the date of commencement of the current block period of five years” shall be substituted.
This means that the interest will be allowed in the account at a rate that will be 1% less than the interest that has been periodically credited to the account from the date of commencement of the current block period of five years.
CBDT has issued a corrigendum to notifications no 3 and 4 published in April 2021, amending the norms relating to the filing of SFTs as below:-
As per Notification No. 52/2023–Dated 26/10/2023 The Central Government on the recommendation of the council makes the following amendments in CGST Rules 2017 namely—
As per Circular No. 202/14/2023-Dated 27/10/2023, It provides clarification related to exports of services through the Vostro account for consideration of supply under section 2(6) of the IGST act 2017.
As per Circular No. 203/15/2023-Dated 27/10/2023, It provides clarification on the Place of Supply in the case of Exports under section 13 of the IGST Act 2017, Representations have been received from the trade and field formations seeking clarification on certain issues concerning the determination of place of supply in case of –
(ii) There may be another case where the advertising company wants to display its advertisement on hoardings/billboards at a specific location availing the services of the vendor. Therefore, such services provided by the Vendor to the advertising company are purely in the nature of advertisement services in respect of which the Place of Supply shall be determined in terms of Section 12(2) of the IGST Act.
However, in cases where the agreement between the supplier and the recipient is restricted to providing physical space on rent along with basic infrastructure without components of Hosting and IT Infrastructure provisioning services, the place of supply shall be the location of immovable property.
As per Circular No. 204/16/2023-DATED 27-10-2023 It deals with taxability and valuation of the activity of providing corporate guarantee by a related person to banks/financial institutions for another related person, as well as by a holding company in order to secure credit facilities for its subsidiary company.
As per Circular No. 205/17/2023- DATED 31-10-2023, It provides clarification on the GST rate on imitation Zari thread or yarn based on the recommendation of the GST council in its 52nd meeting held on 7-10-2023 The GST Council has recommended clarifying that imitation Zari thread or yarn made from metalized polyester film/plastic film falling under HS 5605 are covered by Sl. No. 218AA of Schedule I attracting 5% GST. The GST Council has also recommended that no refund will be permitted on polyester film (metalized)/plastic film on account of the inversion of the tax rate.
As per Circular No. 206/18/2023-GST -Dated 31-10-2023 The clarifications with reference to GST levy, related to the following issues are being issued through this circular.
As per Notification No. 53/2023- DATED- 2-11-2023 It Provides special for the class of persons who failed to file an appeal against the order passed by the proper officer under sections 73 and 74 within the prescribed time limit the said person shall file an appeal against the the said order in FORM GST APL-01 per sub-section (1) of Section 107 of the said Act, on or before the 31st day of January 2024-
No appeal under this notification shall be admissible for a demand not involving tax and no refund will be processed until the appeal is disposed-off.
As per Notification No. 54/2023- DATED 17-11-2023 Section 25 of the Central Goods and Services Tax act, 2017, read with rule 8 of the Central Goods and Services Tax rules, 2017 – registration – procedure for – specified states or union territories for the words, “State of Gujarat and the State of Puducherry”, the words “States of Andhra Pradesh, Gujarat, and Puducherry” shall be substituted.
SBOs behind LLPs are all set to surface
The new LLP SBO rules, akin to what companies currently, follow, introduce a similar framework for Limited Liability Partnerships (LLPs). This means that LLPs will now be required to adhere to SBO declarations and maintain registers, just like companies. The objective remains the same i.e. to ensure transparency and accountability by identifying and disclosing the individuals who ultimately hold the beneficial interest and steer the decision-making within LLPs. The idea is to uncover the intricate networks of holdings and cross-holdings, a practice commonly employed to hide the identity of the individual (s) owning an entity.
MCA appoints the date of enforcement for Section 5 of the Companies (Amendment) Act,2020
Ministry of Corporate Affairs appoints 30th October 2023 as the date of enforcement for Section 5 of the Companies (Amendment) Act,2020 relating to the amendment of Section 23 (Public officer and private placement) of the Companies Act,2013.
RBI issues Master Direction (Non-Banking Company – Scale Based Regulation) Directions, 2023
The Reserve Bank of India (RBI) issued the much-awaited Master Direction – Reserve Bank of India (Non-Banking Financial Company – Scale Based Regulation) Directions, 2023 (MD) on 19 October 2023. The MD has been issued in supersession of the existing Master Directions Systemically Important and Non-Systemically Important NBFCs.
RBI has followed a streamlined approach by consolidating the provisions of the Master Directions applicable to Systemically and Non-Systemically important NBFCs, certain provisions of the Scale Based Regulatory Framework for NBFCs, and the related circulars released by the RBI periodically, into one single Master Direction. All the NBFCs, except the expressly exempt ones shall be governed by this MD.
RBI has established a layered approach with incremental obligations being assigned to each layer, as the NBFC progresses based on its asset size, scale of activity, and perceived riskiness. For ease of reference, the MD is divided into sections applicable to different categories of NBFCs, viz. NBFC-Base Layer, NBFC-Middle Layer, NBFC-Upper Layer, etc. depending upon size and function.
SEBI Board Meeting: Key Approvals for Social Stock Exchange, Index Providers & Real Estate Investments
The SEBI Board’s recent decisions mark a significant shift in regulatory dynamics, aiming to foster transparency, inclusivity, and investor protection. These changes not only reflect SEBI’s commitment to adapt to evolving market needs but also set the stage for a more robust and responsive securities market in India. Investors, NPOs, and market participants can anticipate a more flexible and dynamic landscape with these forward-thinking regulatory adjustments.

Disclaimer: Information in this note is intended to provide only a general update on the subjects covered. It is not intended to be a substitute for detailed research or the exercise of professional judgment. KNM accepts no responsibility for loss arising from any action taken or not taken by anyone using this publication. Updates are till the period 26 November 2023.
On consideration of the matter, to avoid genuine hardship for the domestic companies in exercising the option u/s 115BAA of the Act, CBDT in exercise of the powers conferred under section 119(2)(b) of the Act, hereby directs that:-
The delay in filing Form No. 10-IC as per Rule 21AE of the Rules for the previous year relevant to A.Y. 2021-22 is condoned in cases where the following conditions are satisfied:
(I) The return of income for the relevant assessment year has been filed on or before the due date specified under section 139(1) of the Act;
(ii) The assessee company has opted for taxation u/s 115BAA of the Act in item (e) of “Filing Status” in “Part A-GEN” of the Form of Return of Income ITR-6; and
(iii) Form No. 10-IC is filed electronically on or before 31.01.2024 or 3 months from the end of the month in which this Circular is issued, whichever is later.
Direct Tax collection, net of refunds, stands at Rs. 9.57 lakh crore which is 21.82% higher than the net collections for the comparable period of last year. This collection is 52.50% of the total Budget Estimates of Direct Taxes for FY 2023-24.
Central Board of Direct Taxes (CBDT) issued a notification notifying that the provisions of clause (vii) of sub-section (2) of section 56 of the Act shall not apply to consideration received by a company for the issue of shares that exceed the face value of such shares, if the said consideration has been received from a person, being a resident, by a company which fulfills the following conditions
(i) Where The case of such a Startup Company is selected under scrutiny on the single issue of applicability of section 56 (2) (vii) of the Act, with no verification on such issues shall be done by the Assessing Officers during the proceedings u/s 143(2) or u/s 147/143(2) of the Act and contention of such recognized Startup Companies on the issue will be summarily accepted.
(ii) Where The case of such a Startup Company is selected under scrutiny with multiple issues including the issue u/s 56 (2) (vii) of the Act, the issue of applicability of section 56(2) (vii) of the Act shall not be pursued during the assessment proceedings of such a Startup Company. Due procedure be followed about other issues for which the case has been selected.
CBDT has notified the new Rule 11UA with the following significant changes viz-a-viz the draft amendment issued in May 2023 for public comments:
Bringing parity between the valuation of unlisted equity shares and CCPS (except for the NAV method which applies only to unlisted equity shares).
Clarifying the ambiguity on the window period of 90 days for the price matching facility There is no change in the safe harbor tolerance limit of 10% proposed in May 2023.
The new Rule 11UA is applicable from 25 September 2023 onwards. Applicability of the new Rule on shares issued between 1 April 2023 to 24 September 2023 may be disputed. Further, the new Rule may be disputed on some other grounds as well, such as why the 5 new methods of valuation are restricted to investment by non-residents only. This may create practical challenges and discrimination for resident investors even if the issue price is the same for both categories of investors.
Representations have been received regarding difficulties in filling details of persons who have made a ‘substantial contribution to the trust or institution’ by examining this matter it is hereby stated that for the purposes of providing details in (i) Form No. 10B in the Annexure, in row 41; and (ii) Form No. 10BB in the Annexure, in row 28, for the assessment year 2023-24:
(i) The aforesaid details (that is, of persons making substantial contributions) may be given for those persons whose total contribution during the previous year exceeds fifty thousand rupees;
(ii) details of relatives of such person, as referred to in (a) above may be provided, if available.
(iii) details of concerns in which such person, as referred to in (a) above, has substantial interest may be provided, if available.
Central Board of Direct Taxes (Board) vide its order under section 119 of the Income-tax Act, 1961 directed that all validly filed returns up to Assessment Year 2017-18 with refund claims, which could not be processed under sub-section (1) of the Section 143 of the Act and which had become time-barred, should be processed by 30-11-2021. The matter has been re-considered by the Board in view of pending taxpayer grievances related to issue of refund. To mitigate the genuine hardship being faced by the taxpayers on this issue, Board, by virtue of its power under section 119 of the Act and in partial modification of its earlier order under section 119 of the Act hereby further extends the time frame dated 30-9-2021 till 31-1-2024 in respect of returns of income validly filed electronically.
The following amendment have been made in Prescribed rules -:
(i) Rule 114B of Income tax Rules, 1962 -:
(a) A company or partnership firm (including limited liability partnership) is not required to submit Form 60
(b) A foreign company who, does not have any income chargeable to tax in India; and does not have a permanent account number, and enters into any transaction referred to at Sl. No. 2 or 12 of the Table, in an IFSC banking unit, shall make a declaration in Form No. 60
(ii) In the principal rules, in rule 114BA, the rule lists following additional situations in which a person is not required to obtain PAN:
(a) where the person, making the deposit or withdrawal of an amount otherwise than by way of cash,
(b) Opening a current account not being a cash credit account as per clause of this rule, is a non-resident (not being a company) or a foreign company;
(c) the transaction is entered into with an IFSC banking unit; and
(d) such non-resident (not being a company) or the foreign company does not have any income chargeable to tax in India.
(iii) In the principal rules, in rule 114BB, after the proviso, the following shall be inserted, namely: – “Provided further that the provisions of this sub-rule shall not apply in a case
(a) where the person, making the deposit or withdrawal of an amount otherwise than by way of cash or opening a current account not being a cash credit account, is a non-resident (not being a company) or a foreign company;
(b) the transaction is entered into with an IFSC banking unit, and such non-resident (not being a company) or the foreign company does not have any income chargeable to tax in India.
With effect from 1 January 2024 onwards Unit in an IFSC is;
(a) Exempted from the requirement to submit Form 15CA (Part D) if the payment is not taxable in India.
(b) Required to submit information in new Form 15CD online every quarter in respect of outbound remittances to non-residents.
(c) Form 15CD has been duly prescribed by CBDT and contains details such as PAN, Tax Deduction Account No. (TAN), status of the Unit, contact details, details of the remittance, etc.
CBDT has prescribed Form 10-IFA being the application form required to be submitted by a co-operative society electronically, in order to be entitled for the lower tax rate prescribed u/s 115BAE.
As per Notification No.11/2023 Dated 29/09/2023 CG on the recommendation of the council hereby makes the further amendment in Notification No. 1/2017, Dated 28/06/2023
(i) betting;
(ii) casinos;
(iii) gambling;
(iv) horse racing;
(v) lottery; or
(vi) online money gaming;
As per Notification No. 49/2023 Dated 29-09-2023
The Central Government, on the recommendations of the Council, notifies the
following supplies under section 15(5) of the Central Goods and Services Tax Act,
2017namely: —
This notification shall come into force on the 1st day of October, 2023.
As per Notification No. 50/2023 Dated 29-09-2023
The Central Government, on the recommendations of the Council makes the following amendment in Notification no. 66/2017 -Central Tax, Dated 15/11/2017 –
In the section 148 of the Central Goods and Services Tax Act, 2017, with effect from the 1st October, 2023, after the words and figures “composition levy under section 10 of the said Act”, the words and figures “, other than the registered person making supply of specified actionable claims as defined in clause (102A) of section 2 of the said Act,” shall be inserted.
As per Notification No. 51/2023 Dated 29-09-2023
The following amendments have been made in prescribed rules under CGST rules 2017-
Financial Telecommunication payment network.`
As per Circular No. 24/2023 Dated 30-09-2023
It has been notified that all goods or services may be exported on payment of integrated tax on which the supplier of such goods or services may claim the refund of tax so paid. To implement above restrictions imposed on export of goods or services on payment of IGST, DG Systems CBIC has developed a backend functionality to restrict IGST refund route for the goods, changes have been made in the system of filing of shipping bills and during amendment, with respect to the commodities mentioned in the said notification. Since IGST refund is paid at shipping bills level, the checks have been enabled at shipping bill level.
As Per Notification No. 12/2023 Dated 19-10-2023 The CG on the recommendation of council makes the following further amendments in No. 11/2017-Central Tax (Rate), Dated 28-06-2017,
This notification shall come into force with effect from the 20th day of October, 2023.
As per Notification No. 13/2023 Dated 19-10-2023 The CG on recommendation of the council makes the following further amendments in power to grant exemption from tax – CGST exempt services amendment in notification no. 12/2017-central tax, dated 28-6-2017, define–
(a) water supply;
(b) public health;
(c) sanitation conservancy;
(d) solid waste management; and
(e) slum improvement and upgradation.
This notification shall come into force with effect from the 20th day of October, 2023
As per Notification No. 14/2023 Dated 19-10-2023 The CG on recommendation of the council makes the further amendment in levy and collection of tax – reverse charge on certain specified supplies of services – amendment in notification no. 13/2017-central tax (rate), dated 28-6-2017,
This notification shall come into force with effect from the20th October, 2023.
As per Notification No. 15/2023 Dated 19-10-2023 The CG on the recommendation of the council makes the following amendments in Notification No. 15/2017-Central Tax (Rate), dated 28-06-2017,
This notification shall come into force with effect from the 20th day of October, 2023.
As per Notification No. 16/2023 Dated 19-10-2023 The Central Government, on the recommendations of the Council, hereby makes the following further amendments in the Notification No. 17/2017- Central Tax (Rate), dated 28-6-2017
This notification shall come into force with effect from the 20th day of October, 2023`
As per Notification No. 17/2023 Dated 19-10-2023 and Notification no. 18/2023, Dated 19-10-2023
This notification shall come into force with effect from the 20th day of October, 2023.
As per Notification No. 19/2023 Dated 19-10-2023 The Central Government on recommendation of the council makes the following amendment in levy and collection of tax – reverse charge on certain specified supplies of goods – amendment in Notification No. 4/2017-central tax, dated 28-6-2017
The following entry shall be substituted “Central Government [excluding Ministry of Railways (Indian Railways)], State Government, Union territory or a local authority.”
This notification shall come into force with effect from the 20th day of October, 2023.
As per Notification No. 20/2023 Dated 19-10-2023 The Central Government on the recommendation of the council makes the further amendment in notification no. 5/2017-central tax (rate), dated 28-6-2017 refund of tax – notified supplies of goods in respect of which no refund of unutilized input tax credit shall be allowed where rate of tax on input is higher than rate of tax on output supplies. In case of supply of imitation Zari thread or yarn made out of metallized polyester film /plastic film, refund of unutilized ITC due to inverted duty structure shall not be available.
This notification shall come into force with effect from the 20th day of October, 2023.
Every Co. must designate a person for furnishing information to ROC w.r.t beneficial interest in shares of company
The Govt. has notified the Companies (Management and Administration) Second Amendment Rules, 2023. As per the amended norms, every company must designate a person who shall be responsible for furnishing information, and extending cooperation in providing information to the Registrar or any other authorised officer regarding beneficial interest in shares of the company. Further, a company may designate a company secretary (CS), a KMP or every director, if there is no CS or KMP.
The Govt. has notified the Companies (Prospectus and Allotment of Securities) Second Amendment Rules, 2023. As per the amended norms, every private co. except small co. must issue the securities only in dematerialised form within 18 months from the closure of the FY i.e., march 31, 2023. Further, the company must facilitate the dematerialisation of all its securities in accordance with the provisions of the Depositories Act. These provisions shall not apply to Government Companies.
The Govt. has notified LLP (Third Amendment) Rules, 2023. As per the amended rules, a person whose name is entered in register of partners of LLP but doesn’t hold any beneficial interest in contribution must file a declaration to that effect in Form 4B within 30 days from the date on which his name is entered in the register. Further, every LLP must maintain a register of its partners in Form 4A from the date of its incorporation. The register must be kept at the registered office of LLP.
Public companies that issued share warrants before the Companies Act, 2013, and have not yet converted them into shares face new requirements. Within three months of the rules coming into force, these companies must inform the Registrar about the details of these share warrants using Form PAS-7. Within six months, they must ask the bearers of the share warrants to surrender them and have the shares dematerialized in their accounts. The company must notify the bearers via Form PAS-8 on their website and publish the same notice in a vernacular newspaper and an English newspaper. If a bearer fails to surrender the share warrants within the specified time, the company is obligated to convert them into dematerialized form and transfer them to the Investor Education and Protection Fund. This change encourages transparency and ensures that share warrants are brought in line with modern dematerialization practices.
Ministry of Corporate Affairs notifies Companies (Incorporation) Third Amendment Rules, 2023 namely by:
Ministry of Corporate Affairs informs stakeholders that Ministry of Corporate Affairs has integrated with National Single Window System (NSWS) for the Incorporation of Companies and LLPs. Incorporation services can also be availed through NSWS portal.
Given the growing complexity of the banking sector, it becomes imperative to establish an effective senior management team in the banks to navigate ongoing and emerging challenges. To address the issues and challenges, banks are advised to ensure the presence of at least two Whole Time Directors (WTDs), including the MD&CEO, on their Boards. While ensuring compliance to the above instructions, careful consideration shall also be given to meet the requirements under other applicable statutory/regulatory provisions.
RBI has issued Master Directions on ‘interest rate on deposits’ whereby it has been decided that (i) the minimum amount for offering non-callable TDs may be increased from Rs. 15 lakh to Rs. 1 crore i.e., all domestic term deposits accepted from individuals for amount of Rs. 1crore and below shall have premature-withdrawal-facility and (ii) these instructions shall also be applicable for Non-Resident (External) Rupee (NRE) Deposit / Ordinary Non-Resident (NRO) Deposits.
Earlier, SEBI issued directions to stock exchanges having commodity derivatives segment in respect of suspension of trading in derivative contracts in 7 agro commodities for a period of one year. Thereafter, suspension was extended beyond December 20, 2022 i.e. till Dec 20, 2023. Now, SEBI has further extended the suspension of trading in these contracts for one more year i.e. till December 20, 2024.
The Labour Department of Delhi has issued an order with respect to revision of rates of minimum wages in the specified Scheduled Employments for the following category of workers with effect from October, 2023, namely:
To further strengthen the regulatory framework of the liquidation process in terms of accountability of the liquidator towards stakeholders, the IBBI has issued a discussion paper on “Strengthening the Liquidation Process”. The key proposals include the mandatory holding of a meeting of the Stakeholders Constitution Committee (SCC), mandating the liquidator to place a reason for liquidation costs exceeding estimates of liquidation cost before SCC etc.
Disclaimer: Information in this note is intended to provide only a general update of the subjects covered. It is not intended to be a substitute for detailed research or the exercise of professional judgment. KNM acceptsno responsibility for loss arising from any action taken or not taken by anyone using this publication. Updates are till the period 26 October 2023.
For the purpose of clause (xiii) of sub-section (2) of section 56, where any person receives at any time during any previous year any sum under a life insurance policy, then, the income chargeable to tax under the said clause during the previous year in which such sum is received shall be computed as per new Rule “11UACA”. Computation of income chargeable to tax under clause (xiii) of sub-section (2) of section 56-:
In the Income-tax Rules, 1962 (hereinafter referred to as the principal rules), after rule 6ABBA, the following rule shall be inserted -:
For the purpose of deduction of tax at source on any income payable in foreign currency, the rate of exchange for the calculation of the value in rupees of such income payable –
| S.No | Circumstance | Where accommodation is unfurnished | Where accommodation is furnished |
| (1) | (2) | (3) | (4) |
| (1) | Where the accommodation is provided by the Central Government or any State Government to the employees either holding office or post in connection with the affairs of the Union or of such State. | The license fee determined by the Central Government or any State Government in respect of accommodation in accordance with the rules framed by such Government is reduced by the rent actually paid by the employee. |
The value of perquisite as determined under column (3) and increased by 10% per annum of the cost of furniture (including television sets, radio sets, refrigerators, other household appliances, air- air-conditioning plant or equipment) or if such furniture is hired from a third party, the actual hire charges payable for the same as reduced by any charges paid or payable for the same by the employee during the previous year. |
| (2) |
Where the accommodation is provided by any other employer and –
(a) where the accommodation is owned by the employer, or |
(i) 10% of salary in cities having a population exceeding 40 lakhs as per 2011 census |
The value of perquisite as determined under column (3) and increased by 10% per annum of the cost of furniture (including television sets, radio sets, refrigerators, other household appliances, air- air-conditioning plant or equipment or other similar appliances or gadgets) or if such furniture is hired from a third party, by the actual hire charges payable for the same as reduced by any charges paid or payable for the same by the employee during the previous year |
| (ii) 7.5% of salary in cities having a population exceeding 15 lakhs but not exceeding 40 lakhs as per 2011 census; | |||
| (iii) 5% of salary in other areas, in respect of the period during which the said The accommodation was occupied by the employee during the previous year as reduced by the rent, if any, actually paid by the employee. |
(b)where the accommodation is taken on lease or rent by the employer.
Actual amount of lease rental paid or payable by the employer or 10% of salary, whichever is lower, as reduced by the rent, if any, actually paid by the employee.
The value of perquisite as determined under column (3) and increased by 10% per annum of the cost of furniture (including television sets, radio sets, refrigerators, other household appliances, air- air-conditioning plant or equipment, or other similar appliances or gadgets) or if such furniture is hired from a third party, by the actual hire charges payable for the same as reduced by any charges paid or payable for the same by the employee during the previous year.
| (3) | Where the accommodation is provided by the employer specified in the serial number (1) or (2) in a hotel (except where the employee is provided such accommodation for a period not exceeding in aggregate fifteen days on his transfer from one place to another). | Not applicable | 24% of salary paid or payable for the previous year or the actual charges paid or payable to such hotel, which is lower, for the period during which such accommodation is provided as reduced by the rent, if any, actually paid or payable by the employee |
In exercise of the powers conferred by sub-section (1F) of section 197A, read with clause (c) of sub-section (2) of section 80LA, of the Income-tax Act, 1961 the Central Government hereby specifies that no deduction of tax shall be made under section 194-I of the Income-tax Act on payment in the nature of lease rent or supplemental lease rent, as the case may be, made by a person (hereinafter referred as ‘lessee’) to a person being a Unit of an International Financial Services Centre (hereinafter referred as ‘lessor’) for the lease of a ship subject to the following-
The Central Government hereby makes the following Scheme further to amend the National Savings Time Deposit Scheme, 2019, namely: —
| S.No | Category | Rate of Interest (p.a.) |
| 1 | One-year | 6.9 |
| 2 | Two-years | 7.0 |
| 3 | Three-years | 7.0 |
| 4 | Five-years | 7.5* |
| S.No | Particulars | Details |
| (a) | Name of the bond | Ten-Year Zero-Coupon Bond of REC Ltd. |
| (b) | Period of life of bond | Ten years one month |
| (c) | The time schedule of the issue | To be issued on or before the 31st day of March of bond 2025; |
| (d) | The amount to be paid on maturity or redemption of the bond | 1 lakh rupees for each bond |
| (e) | The discount | Rs. 2517.85 crores |
| (f) | The number of bonds to be issued | Five lakh |
In the said notification, in the fourth proviso: —
In the said notification, in the first paragraph, in the fifth proviso: —
In the said notification, in the first paragraph, in the fifth proviso: —
However, it is clarified that no refund will be granted where GST has already been paid in any of the above cases.
The Ministry of Corporate Affairs in order to promote ease of doing business, through General Circular No. 08/2023 dated August 23 2023, has decided to grant a one-time relaxation in additional fees to the LLPs who could not file their forms within the due date and provide them an opportunity to update their filings and get their compliances done. Forms included in this scheme :
The Ministry of Corporate Affairs vide notification dated 2nd August 2023 has issued the Companies (Incorporation) Second Amendment Rules, 2023. The Rules has revised Form No. RD-1 to be used by companies for filing applications to Central Government (Regional Director) for approval of Compromises, Arrangements, Amalgamations, and conversions.
RBI has issued comprehensive lending guidelines from time to time with the intention of creating clarity, choice, and fairness in lending practices. These circulars and Master Directions pertain to Scheduled Commercial Banks (SCBs), Non-Banking Financial Companies (NBFCs), and Housing Finance Companies (HFCs). EMI loans form the cornerstone of these rules which aim to inform, empower, and provide viable loan repayment solutions throughout borrowers’ loan duration. Recently, RBI has issued guidelines to allow flexibility in interest rate offerings for borrowers paying EMIs under a floating rate.
Securities and Exchange Board of India (SEBI) introduced the Third Amendment to its Listing Obligations and Disclosure Requirements Regulations, 2023. The provisions are broadly applicable to all entities that wish to voluntarily delist non-convertible debt securities or redeemable preference shares. The latest regulations are aimed at Addressing the voluntary delisting process of non-convertible debt securities or non-convertible redeemable preference shares. Setting clear parameters on which entities can or cannot opt for voluntary delisting. Ensuring transparency, clarity, and protection for investors.
The Securities and Exchange Board of India (SEBI), in its continuous effort to bolster investor protection and ensure fair market practices, released a significant notification on 16th August 2023. This notification revolves around the “Securities and Exchange Board of India (Facilitation of Grievance Redressal Mechanism) (Amendment) Regulations, 2023.” The aim is to streamline and expedite the process of resolving investor grievances across various domains falling under SEBI’s purview.
The Securities and Exchange Board of India (SEBI) has recently issued a notification on August 16, 2023, amending the Securities and Exchange Board of India (Real Estate Investment Trusts) Regulations, 2014. The amendments, known as the Securities and Exchange Board of India (Real Estate Investment Trusts) (Second Amendment) Regulations, 2023, bring notable changes to various aspects of real estate investment trusts. These changes aim to refine the regulatory framework, enhance investor protection, and facilitate smoother functioning of real estate investment trusts.
The Securities and Exchange Board of India (SEBI) has released the Securities and Exchange Board of India (Foreign Portfolio Investors) (Second Amendment) Regulations, 2023. This amendment focuses on altering ownership and control criteria for foreign portfolio investors (FPIs), aiming to enhance transparency and regulatory compliance
The Securities and Exchange Board of India has mandated additional disclosures by Foreign Portfolio Investors (FPIs) that require obtaining granular information of persons having any ownership, economic interest, or control in some objectively identified FPIs under the PML Act.
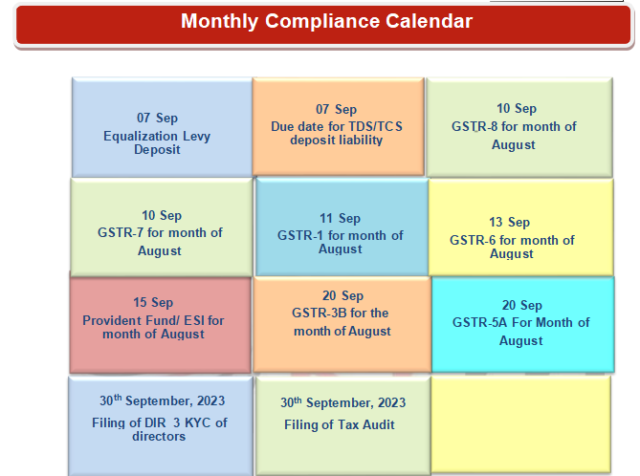
Disclaimer: Information in this note is intended to provide only a general update of the subjects covered. It is not intended to be a substitute for detailed research or the exercise of professional judgment. KNM accepts no responsibility for loss arising from any action taken or not taken by anyone using the publication. Updated are till the period 26 August 2023.
In exercise of the powers conferred by sub-section (1F) of section 197A, read with clause (34B) of section 10 of the Income-tax Act, 1961 (43 of 1961) (hereinafter the Income-tax Act), the Central Government hereby specifies that no deduction of income tax shall be made under section 194 of the Income-tax Act from any income in the nature of dividends paid by any unit of an International Financial Services Centre, primarily engaged in the business of leasing an aircraft (hereinafter referred to as the payer) to a company, being a Unit of an International Financial Services Centre primarily engaged in the business of leasing of an aircraft (hereinafter referred as the payee) subject to the following-
The payee shall, —
The payer shall, —
Central Government has notified ‘Yamuna Expressway Industrial Development Authority’, (PAN AAALT0341D), an authority constituted by the State Government of Uttar Pradesh, in respect of the following specified income arising to that Authority, namely: —
National Savings (Monthly Income Account) Scheme, 2019 has been amended through National Savings (Monthly Income Account) (Amendment) Scheme, 2023 and the maximum investment limit has been raised from ₹ four lakh fifty thousand to ₹ nine lakh for a single account and from ₹ nine lakh to ₹ 15 lakh for a joint account with effect from 1st April 2023. Likewise, Senior Citizen Savings Scheme, 2019 has been amended through Senior Citizens Savings (Amendment) Scheme, 2023 and the maximum investment limit has been raised from ₹ 15 lakh to ₹ 30 lakh.
To encourage co-operative movement in sugar sector, a new clause (xvii) was inserted to amend sub-section (1) of section 36 of the Income-tax Act to provide that the amount paid for purchase of sugarcane by the co-operative societies engaged in the manufacture of sugar at a price which is equal to or less than the price fixed by or fixed with the approval of the Government shall be allowed as deduction for computing business income of the sugar co-operative factories.
To extend the benefit of the abovementioned relief to all the applicable years, section 155 of the Act has been amended to insert a new subsection (19) vide Finance Act, 2023, w.e.f. 1st April 2023. It provides that in the case of a sugar mill cooperative, where any deduction in respect of any expenditure incurred for the purchase of sugarcane has been claimed by an assessee and such deduction has been disallowed wholly or partly in any previous year commencing on or before the 1st day of April, 2014, the Assessing Officer shall, on the basis of an application made by such assessee in this regard, recompute the total income of such assessee for such previous year.
In order to standardize the manner of filing application to the Jurisdictional Assessing Officer under sub-section (19) of section 155 of the Act and its disposal by the Jurisdictional Assessing Officer under the said section, following SOP has been outlined;
The CBDT, in exercise of its powers under section 119 of the Income-tax Act, 1961, hereby issues the following clarification with respect to reporting of accounts other than U.S. reportable accounts.
A Treaty Qualified Retirement Fund is a non-reporting financial institution under sub-clause
(b) of clause (5) of Rule 114F of the Rules. However, under the Common Reporting Standard (CRS) which involves exchange of information in respect of reportable accounts other than U.S reportable accounts, a Treaty Qualified Retirement Fund is not treated as a Non-Reporting Financial Institution. It is clarified that a Treaty Qualified Retirement Fund shall not be treated as a non-reporting financial institution for the purposes of maintaining and reporting information in respect of any reportable account other than a U.S. reportable account defined in clause (11) of Rule 114F of the Rules.
Under the CRS, a non-public fund of the armed forces is in the nature of an active non- financial entity (NFE). In view of this, it is hereby clarified that a non-public fund of the armed forces shall not be treated as a financial institution in case of any reportable account other than a U.S. reportable account defined under clause (11) of Rule 114F of the Rules.
A gratuity fund is a non-reporting financial institution under sub-clause (c) of clause (5) of Rule 114F of the Rules, provided that it is also a financial institution under Rule 114F of the Rules. Gratuity funds which are only managed by either individual(s) and/or entity(ies)
that is not a financial institution, are not capable of being classified as a managed Investment Entity Rules. Hence, such gratuity funds will qualify as a passive non-financial entity as per clause (D) (i) of Explanation to clause 6 of Rule 114F of the Rules.
Generally, accounts held in gratuity funds will be treated as excluded accounts if they qualify as retirement or pension accounts as per clause h(i) of Explanation to clause 1 of the Rule 114F, subject to satisfaction of all the conditions laid out in that clause including, inter alia, the monetary limits in respect of contributions to the said funds.
However, accounts held in gratuity funds may also involve withdrawals conditioned on meeting specific criteria in circumstances beyond death, disability or retirement (e.g., gratuity funds that permit withdrawals upon resignation after a certain period of continuous service). Such accounts can be treated as excluded accounts under clause h(ii) of Explanation to clause 1 of the Rule 114F subject to satisfaction of all the conditions laid out in that clause including, inter alia, annual monetary limits in respect to contributions to the said funds.
In view of the above, in the event that a gratuity fund is a reporting financial institution, relevant accounts held with such a gratuity fund fulfilling the conditions specified in clause (h)(i) or h(ii) of the Explanation to clause 1 of Rule 114F of the Rules, will be treated as excluded accounts.
In exercise of the powers conferred by Section 15 of the Government Savings Promotion Act, 1873, the Central government t hereby makes the following rules further to amend the Government Savings Promotion General Rules, 2018, namely: —
In the said notification, in the fourth proviso: — for the words, letter and figure “tax periods April 2023 and May 2023”, the words, letter and figure “tax periods April 2023, May 2023 and June 2023” shall be substituted; for the words, letters and figure “thirtieth day of June, 2023”, the words, letter and figure “thirty-first day of July, 2023” shall be substituted.
This notification shall be deemed to have come into force with effect from the 30th day of June, 2023.
Month of April 2023, May 2023 and June 2023″ shall be substituted; For the words, letters and figure ” thirtieth day of June, 2023″, the words, letter and figure ” thirty-first day of July,2023″ shall be substituted. This Notification deemed to have come into force with effect from 30th June 2023.
For the words, letter and figure “month of April, 2023 and May 2023″ the words, letter and figure ” months of April 2023, May 2023 and June 2023 ” shall be substituted;
For the words, letters and figure “thirty-first day of May, 2023”, the words, letter and figure “thirty first day of July, 2023” shall be substituted. This Notification deemed to have come into force with effect from 30 June 2023.
This notification shall be deemed to have come into force with effect from the 30th day of June, 2023.
This notification shall be deemed to have come into force with effect from the 30th day of June, 2023.
This notification shall be deemed to have come into force with effect from the 30th day of June, 2023.
This notification shall be deemed to have come into force with effect from the 30th day of June, 2023.
In the said notification, for the words, letter and figure “30th day of June, 2023” the words, letter and figure “31st day of August, 2023” shall be substituted.
This notification shall be deemed to have come into force with effect from the 30th day of June, 2023.
Credit of compensation cess available in electronic credit ledger cannot be taken into account while considering the balance of electronic credit ledger for the purpose of calculation of interest.
In a situation where multiple ECOs are involved in a single transaction of supply of goods or services or both through ECO platform and the Supplier-side ECO is himself the supplier of the said supply, TCS is to be collected by the Buyer-side ECO while making payment to the supplier for the particular supply being made through it.
supply or before the expiry of the standard warranty period in this case if manufacturer enter in agreement at the time of original supply than no GST would be chargeable separately as it already charged at the time of original supply however in case of customer enter after the original supply than it is separate contract and GST would be charged on it.
The functionality compares the liability declared in GSTR-1/IFF with the liability paid in GSTR-3B/3BQ for each return period. If the declared liability exceeds the paid liability by a predefined limit or the percentage difference exceeds the configurable threshold, taxpayer will receive an intimation in the form of DRC-01B.
Upon receiving an intimation, the taxpayer must file a response using Form DRC-01B Part
To further help taxpayers with the functionality, a detailed manual containing the navigation details is available on the GST portal. It offers step-by-step instructions and addresses various scenarios related to the functionality.
It has come to the notice of this Ministry that many members of the three institutes viz. Institute of Chartered Accountants of India, Institute of Cost Accountants of India and Institute of Company Secretaries of India have created multiple user IDs while transacting on existing MCA21 V2 portal. For this, MCA has issued General Circular No. 07/2023 dated 12th July 2023 for Merger of Multiple User IDs in V-2 Portal with New User ID in V-3 and Deactivation of Old User ID in V-2 Portal.
The Centre issued a notification to include the Goods and Services Tax Network (GSTN) under the ambit of the Prevention of Money Laundering Act (PMLA). With this, the GSTN is among those entities that have been mandated to share information with the Enforcement Directorate (ED) and the Financial Intelligence Unit (FIU) under the PMLA Act. These changes have been made under Section 66 of the PMLA, which provides for disclosure of information.
SEBI has directed market infrastructure institutions (MIIs) to set up and operate a common Online Dispute Resolution (ODR) portal. The portal will harnesses online conciliation and online arbitration for resolution of disputes arising in the Indian securities markets. The MIIs
i.e. stock exchanges, depositories and CCs will have to make joint efforts to develop and operationalize the ODR Platform. Also, this circular supersedes the earlier circulars issued by the Board relating to this.
SEBI has prescribed a detailed framework for the Corporate Debt Market Development Fund (CDMDF). The CDMDF shall comply with the Guarantee Scheme for Corporate Debt (GSCD) as notified by MoF. The CDMDF shall deal only in low duration G-sec, Treasury bills, Tri-party Repo on G-sec, guaranteed corporate bond repo with maturity not exceeding 7 days.
SEBI has mandated the requirement of providing Legal Entity Identifier (LEI) details for all non-individual FPIs. Currently, FPIs are required to provide their LEI details in the Common Application Form (CAF), used for registration, KYC and account opening of FPIs on a voluntary basis. Further, all existing FPIs that haven’t provided their LEIs to their DDPs must do so within 180 days from the date of issuance of this circular.This circular shall be effective from 27th July,2023.
The regulatory fee under the (Insolvency Resolution Process for Corporate Persons) Regulations, 2016, shall not be payable in cases where the approved resolution plan in respect of insolvency resolution of a real estate project is from an association or group of allottees in such real estate project.”
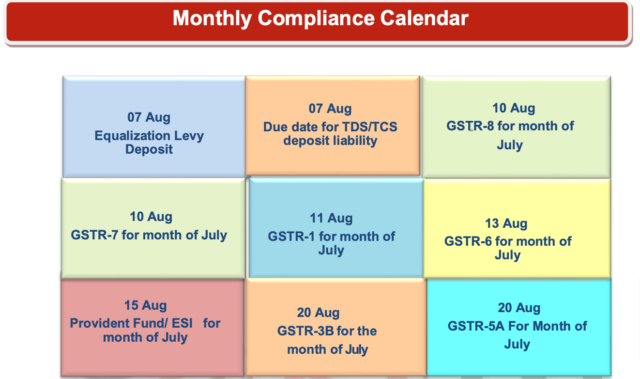
Disclaimer: Information in this note is intended to provide only a general update of the subjects covered. It is not intended to be a substitute for detailed research or the exercise of professional judgment. KNM accepts no responsibility for loss arising from any action taken or not taken by anyone using this publication. Updates are till the period July 2023.
G.S.R. 438(E).––In exercise of the powers conferred by clause (iii) of Section 3 of the Government Securities Act, 2006 (38 of 2006), the Central Government hereby makes the Sovereign Gold Bond Scheme 2023-24
Who can hold these bonds-
The Gold Bonds issued under this Scheme may be held by a Trust, HUFs, Charitable Institution, University or by a person resident in India, being an individual, in his capacity as such individual, or on behalf of minor child, or jointly with any other individual
Minimum and maximum holding-
The bonds will be issued in denominations of one gram of gold or multiples thereof. Provided that the minimum limit of subscription for the Bonds issued shall be of one gram and maximum limit of subscription per fiscal year shall be of four kg for individuals, four kg for Hindu Undivided Family (HUF) and 20 kg for trusts and similar entities notified by the Government from time to time
Nominal value: –
The nominal value of Gold Bonds shall be in Indian Rupees fixed on the basis of simple average of closing price of gold of 999 purity, published by the India Bullion and Jewellers Association Limited, for the last 3 working days of the week preceding the subscription period.
The issue price of the Gold Bonds will be less than the nominal value by ₹50 per gram to those investors applying online and making the payment against the application through digital mode.
Interest–
(i) The interest on the Gold Bonds shall commence from the date of issue and shall be paid at a fixed rate of 2.50 percent per annum on the nominal value of the bond. (ii) The interest is payable half-yearly and the last interest shall be payable along with the principal on maturity.
Redemption- (i) The Gold Bonds shall be repayable on the expiration of eight years from the date of the issue of the Bonds: www.taxmann.com
Loan against Bonds–
Tax Treatment–
The interest received on the Gold Bond shall be taxable as per the provisions of the Income-tax Act, 1961 (43 of 1961). The capital gains tax arising on redemption of these bonds to an individual is exempted.
Companies Act 2013/ Other Laws

 • CBDT vide Press Release dated 19.05.2023 has clarify that the use of international credit cards for meeting his/her expenses by a person when he is abroad will come under the purview of LRS, earlier only Debit card was covered. Further, to avoid any procedural ambiguity, it has been decided that any payments by an individual using their international Debit or Credit cards upto Rs. 7 lakhs per financial year will be excluded from the LRS limits and hence, will not attract any TCS. Existing beneficial TCS treatment for education and health payments will also continue.
Instances have come to notice where the LRS payments are disproportionately high when compared to the disclosed incomes. Therefore, TCS rates are increased. Primary Impact only on investment in assets such as real estate, bonds, stocks outside India by HNI and tour travel packages or gifts to non-residents.
TCS rates with the changes brought about in Finance Act, 2023 are tabulated as under
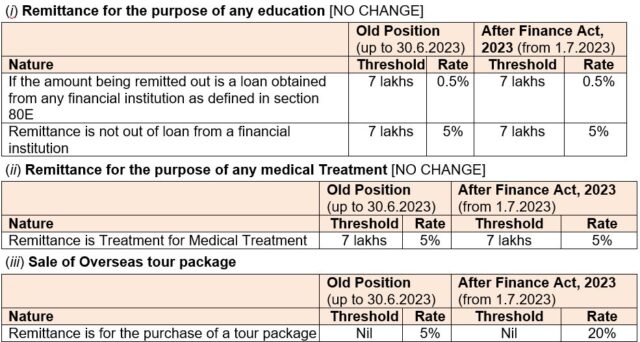
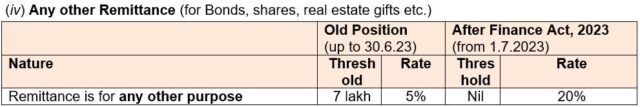
Proposed changes in Rule 11 UA :
Further, where any consideration is received by a company for issue of shares , from any non-resident entity notified by the Central Govt , the price of the equity shares corresponding to such consideration may be taken as the FMV of the equity shares for resident and non-resident investors subject to the following:
The draft Rules on the above lines will be shared for public comments for 10 days, after which these will be notified.
Net winnings = A-(B+C), where
A = Amount withdrawn from the user account;
B = Aggregate amount of non-taxable deposit made in the user account by the owner of such account during the financial year, till the time of such withdrawal; and
C = Opening balance of the user account at the beginning of the financial year

*******

As per Notification No.11/2023 Dated 24/05/2023 CG on the recommendation of council make following amendment in the Notification NO 83/2020 In the said notification, after the third proviso, the following proviso shall be inserted, namely:-―Provided also that the time limit for furnishing the details of outward supplies in FORM GSTR-1of the said rules for the tax period April, 2023, for the registered persons required to furnish return under sub-section (1) of section 39 of the said Act whose principal place of business is in the State of Manipur, shall be extended till the thirty-first day of May, 2023..This notification shall be deemed to have come into force with effect from the 11thday of May, 2023.
GSTN issues advisory on Deferment of Implementation of Time Limit on Reporting Old e-Invoices that it has been decided by the competent authority to defer the imposition of time limit of 7 days on reporting old e-invoices on the e-invoice IRP portals for taxpayers with aggregate turnover greater than or equal to 100 crores by three months. The next date of implementation will be shared by them.
*******

The Ministry of Corporate Affairs notified the Companies (Removal of Names of Companies from the Register of Companies) Amendment Rules, 2023 to amend the Companies (Removal of Names of Companies from the Register of Companies) Rules, 2016. The provisions will come into force on 1-5-2023.
Key Points:
2. Rule 4 (3-A) relating to Application for removal of name of company has been inserted. The Registrar, Centre for Processing Accelerated Corporate Exit will be established under Section 396 (1) and this Registrar of Companies has the power of exercising functional jurisdiction of processing and disposal of applications made in Form No. STK-2 and all matters related to Section 248 having territorial jurisdiction all over India.
4. Form No. STK- 6 (Public Notice) has been revised.
The Ministry of Corporate Affairs notified the Companies (Removal of Names of Companies from the Register of Companies) Second Amendment Rules, 2023 to amend the Companies (Removal of Names of Companies from the Register of Companies) Rules, 2016. The provisions came into force on 10-5-2023.
Key Points:
The Ministry of Corporate Affairs notified the Companies (Compromises, Arrangements and Amalgamations) Amendment Rules, 2023 to amend the Companies (Compromises, Arrangements and Amalgamations) Rules, 2016.
Key Points:
*******

The Reserve Bank of India (RBI) on 19.05.2023 announced the withdrawal of the Rs 2,000 banknote from circulation with the public being “encouraged” to deposit or exchange the notes at bank branches until September 30, 2023. At the same time, the central bank maintained that these notes will enjoy legal tender status even beyond the September 30 deadline.
In furtherance to the RBI’s direction on the withdrawal of Rs. 2,000 notes from circulation, the banks have been advised to provide appropriate infrastructure at the branches such as shaded waiting space, drinking water facilities, etc. considering the summer season.
Further, Banks shall have to maintain daily data on the deposit and exchange of Rs. 2000 banknotes in the prescribed format (specifying date, bank name, and amount deposited/exchanged) and submit the same as and when required.
.
*******

The SEBI has notified amendment in SEBI (ICDR) Regulations, 2018. As per the amended norms, if the issuer making an IPO, desires to have the issue underwritten, it shall, prior to the filing of the prospectus, enter into an underwriting agreement with the merchant bankers or stock brokers, indicating the maximum number of specified securities they shall subscribe to, at a predetermined price which shall not be less than the issue price
Earlier, SEBI issued circulars prescribing norms relating to Core Settlement Guarantee Fund (SGF), Min. Reqd. Corpus of core SGF, etc. for Clearing Corporations (CCs) and Stock Exchanges. SEBI recently received representations to review the target corpus level & to harmonise the methodology for computation of core SGF corpus in Commodity Derivatives Segment. Now, after receiving representations, SEBI directed that the CCs can now align their core SGF in terms of earlier issued SEBI circulars.
*******

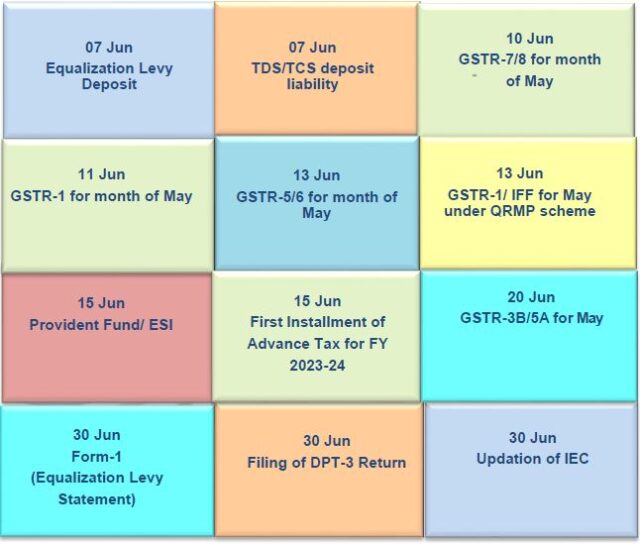
Disclaimer: Information in this note is intended to provide only a general update of the subjects covered. It is not intended to be a substitute for detailed research or the exercise of professional judgment. KNM accepts no responsibility for loss arising from any action taken or not taken by anyone using this publication. Updates are for the period from 26th Apr till 25th May. 2023.
© KNM Management Advisory Services Pvt. Ltd All rights reserved. Copyright by KNM Management Advisory Services Pvt. Ltd All rights reserved. KNM Management Advisory Services Pvt. Ltd.Corporate Office
Connect with us
KNM Management Advisory Services Pvt. Ltd.Corporate Office
Connect with usOUR LOCATIONSWhere to find us?
CONNECT WITH USKNM Social Links
Get Connected