CBDI authorizes ‘CPC Bengaluru’ to rectify mistakes and issue notice of demand u/s 156 of the Income-Tax Act, 1961
CBDT extends due date for furnishing return of income for AY 2025-26 under the Income-Tax Act, 1961
Goods And Service Tax (GST)
Instruction no. 06/2025 – GST [F. No. CBIC – 20006/4/2025 – GST], Section 54 of the Central Goods and Services Tax Act, 2017 – Refund of tax – provisional sanction of refund claims because of identification and evaluation of risk by the system, dated 03-10-2025
Press release, CBIC introduces system-based auto-approval for IFSC code registration to enhance ease of doing business, dated 07-10-2025
Companies Act 2013/ Other Laws
MCA Amends IEPF Refund Rules for Unclaimed Securities
MCA extended the deadline for filing the directors’ KYC forms
MCA extends last date for filing Financial Statements and Annual Return
SEBI Rationalizes RPT Disclosure for Listed Entities
Draft Regulations on Establishment of Branch/Office in India by Overseas Entities
A. GOVERNMENT NOTIFIES REVISED INDIA-QATAR DTAA [24-10-2025]
The Government of the Republic of India and the Government of the State of Qatar, desiring to conclude an Agreement for the avoidance of double taxation and the prevention of fiscal evasion with respect to taxes on income and with a view to promoting economic cooperation between the two countries. The Agreement and Protocol between the Republic of India and the State of Qatar for the avoidance of double taxation and the prevention of fiscal evasion with respect to taxes on income, was signed at New Delhi on the 18th day of February, 2025. And whereas, the said Agreement and Protocol entered into force on the 10th day of September, 2025 in accordance with paragraph 2 of Article 30 of the said Agreement and Protocol.
B. CBDT AUTHORIZES ‘CPC BENGALURU’ TO RECTIFY MISTAKES AND ISSSUE NOTICE OF DEMAND U/S 156 OF THE INCOME-TAX ACT, 1961 [27-10-2025]
In exercise of the powers conferred by sub-sections (1) and (2) of section 120 of the Income-tax Act, 1961 (43 of 1961), the Central Board of Direct Taxes hereby directs that the Commissioner of Income-tax, shall exercise the concurrent powers –(a) to rectify u/s 154 of the IT Act 1961, the mistakes which are apparent from records including any refund issued earlier under the provisions of the Act and/or non-consideration of any pre-paid tax credit and/or non-consideration of any relief eligible and/or calculation of interest u/s 244A of the IT Act 1961, in passing any order under the Income-tax Act resulting in error in computation of the tax and/or refund determined and/or demand;(b) to issue notice of demand under section 156 of the Income-tax Act, 1961 in such cases covered under (a) above.
C. CBDT EXTENDS DUE DATE FOR FURNISHING RETURN OF INCOME FOR AY 2025-26 UNDER THE INCOME-TAX ACT, 1961 [29-10-2025]
The CBDT has decided to extend the due date of furnishing of return of income u/s 139 of the Act for AY 2025-26, which is October 31, 2025 in the case of assessees referred in clause (a) of Explanation 2 to sub-section (1) of Section 139 of the Act, to December 10, 2025.The ‘specified date’ of furnishing of the report of audit under the provisions of the Income Tax Act, 1961 for Previous Year 2024-25 (AY 2025-26), originally due on September 30, 2025 was extended to October 31, 2025. The CBDT has decided to further extend the said ‘specified date’ from October 31, 2025 to November 10, 2025.
A. INSTRUCTION NO. 06/2025 – GST [F. NO. CBIC – 20006/4/2025 – GST], SECTION 54 OF THE CENTRAL GOODS AND SERVICES TAX ACT, 2017 – REFUND OF TAX – PROVISIONAL SANCTION OF REFUND CLAIMS BECAUSE OF IDENTIFICATION AND EVALUATION OF RISK BY THE SYSTEM, DATED 03-10-2025
Summary of Key Instructions on Risk-Based Provisional Refund Processing
The 56th GST Council Meeting (3rd Sept 2025) recommended amendment to Rule 91(2) of the CGST Rules, 2017, allowing 90% provisional refund based on system-generated risk evaluation. The amendment (effective 1st Oct 2025, via Notification No. 13/2025–CT, dated 17-09-2025) introduces a proviso empowering officers to withhold provisional refunds on a case-by-case basis, with recorded reasons.
Notification No. 14/2025–CT (17-09-2025) also specifies categories of taxpayers not eligible for provisional refund for zero-rated supplies under Section 54(6).
Key Guidelines:
Low-risk applications (as per system score) – 90% refund to be sanctioned provisionally.
High-risk applications – no provisional refund; detailed scrutiny required.
Provisional refund denial only in justified cases (e.g., pending appeal, SCN issued, prosecution, or notified category).
Proper officer may issue SCN (RFD-08) if excess refund is later detected.
Timelines for issuing RFD-02/RFD-03 must be strictly followed.
Refunds under Inverted Duty Structure (IDS):
Pending formal amendment to Section 54(6), 90% provisional refund may also be sanctioned for IDS claims filed on or after 1-10-2025, following the same risk-based process.
Monitoring:
Jurisdictional Commissioners to ensure implementation and report compliance. Any operational difficulties to be reported to the Board.
B. PRESS RELEASE, CBIC INTRODUCES SYSTEM-BASED AUTO-APPROVAL FOR IFSC CODE REGISTRATION TO ENHANCE EASE OF DOING BUSINESS, DATED 07-10-2025
CBIC Introduces System-Based Auto-Approval for IFSC Code Registration
In a major step toward trade facilitation and ease of doing business, the Central Board of Indirect Taxes and Customs (CBIC) has implemented system-based auto-approval for IFSC code registration under the Customs Automated System.
Under the new mechanism, once a particular bank account–IFSC code combination is approved for an Importer Exporter Code (IEC) at one Customs location, the same combination will be auto-approved at other locations—eliminating manual approval by Port officers.
Key Benefits:
Faster processing of bank account and IFSC code approvals.
Simplified registration across multiple Customs ports.
Quicker and seamless credit of export incentives to exporters’ bank accounts.
Enhanced overall trade efficiency and transparency.
Previously, exporters had to seek approval at each port separately, leading to delays and duplication. This initiative reduces manual intervention and supports CBIC’s ongoing commitment to leveraging technology for simplified, paperless, and efficient Customs operations.
A. MCA AMENDS IEPF REFUND RULES FOR UNCLAIMED SECURITIES
The Ministry of Corporate Affairs (MCA) published amendment rules for the Investor Education and Protection Fund Authority (IEPF) — though not strictly an amendment of the Act itself, this touches companies’ obligations regarding unclaimed dividends, investor protection and transfers to IEPF, and should be treated as a compliance-adjacent update.
B. MCA EXTENDED THE DEADLINE FOR FILING THE DIRECTORS’ KYC FORMS
The MCA extended the deadline for filing directors’ KYC (forms DIR-3 KYC and DIR-3 KYC-WEB) by directors from 15 October to 31 October 2025, giving companies and their company secretaries additional time to ensure all director KYC compliance is in place.
C. MCA EXTENDS LAST DATE FOR FILING FINANCIAL STATEMENTS AND ANNUAL RETURNS
The MCA granted a further extension for the filing of annual returns (for FY 2024-25) by companies, allowing filings without additional late fees until 31 December 2025. This provides operational relief and should prompt companies to update their internal compliance calendars.
D. SEBI RATIONALIZES RPT DISCLOSURE FOR LISTED ENTITIES
On 13 October 2025, SEBI issued a circular on disclosures by listed entities in respect of transactions with related parties. The circular introduces a tiered-disclosure framework: for listed companies, related‐party transactions up to ₹1 crore are exempt from detailed disclosures, whereas larger transactions will still require full disclosures.
E. DRAFT REGULATIONS ON ESTABLISHMENT OF BRANCH/OFFICE IN INDIA BY OVERSEAS ENTITIES
On 3 October 2025, the RBI released the draft Foreign Exchange Management (Establishment in India of a Branch or Office) Regulations, 2025, proposing to replace the existing regulations for branch/liaison/project offices of foreign entities in India. Major proposals include:
Simplifying the framework: consolidating different categories (Branch, Liaison Office, Project Office) into fewer categories and moving from prescriptive eligibility criteria (net worth, profit track record) to a principle-based approach.
Delegation of more powers to authorised dealer (AD) banks for approvals, thereby reducing direct regulatory approval burdens.
The draft aims to enhance ease of doing business for overseas entities wanting to establish presence in India, subject to FDI policy compliance.
Implication: For corporates with foreign parent/affiliate entities wanting to set up branches/offices in India, this signals an anticipated easing of formalities—review structures and be prepared for transition once final regulations are notified.
F. IBBI (LIQUIDATION PROCESS) (SECOND AMENDMENT) REGULATIONS, 2025
In October 2025, the IBBI issued two significant sets of amendments that impact the insolvency resolution and liquidation processes under the Insolvency and Bankruptcy Code, 2016 (IBC). On 14 October, it notified the “IBBI (Liquidation Process) (Second Amendment) Regulations, 2025”, which remove the provisions in the Liquidation Process Regulations, 2016 for sale of the corporate debtor as a going‐concern (Regulation 32A and related clauses). On the same date, it also notified the “IBBI (Insolvency Resolution Process for Corporate Persons) (Sixth Amendment) Regulations, 2025”, which amend the CIRP Regulations, 2016, notably omitting Regulation 39C (relating to sale of the corporate debtor as a going concern) and modifying Form H and other related provisions. These changes are effective prospectively and reflect IBBI’s push to streamline insolvency and liquidation procedures, aligning them more closely with the resolution-first mandate of the IBC and limiting the ability to shift into liquidation via going concern sales as a standard path.
MONTHLY COMPLIANCE CALENDAR
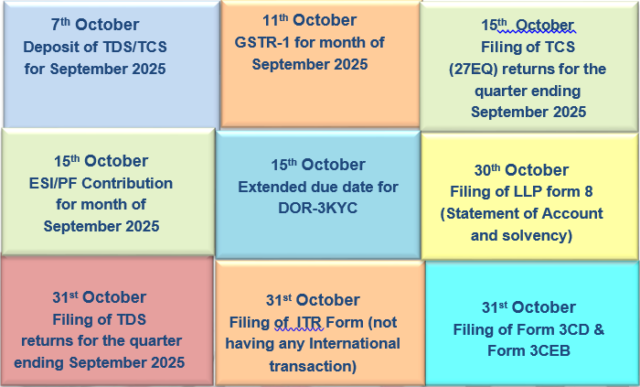
7th November – Deposit of TDS/TCS for October 2025
10th November – Extended due date for Tax audit
10th November – GSTR-8/ GSTR-7 for month of October
11th November – GSTR-1 for month of October 2025
15th November – ESI/PF Contribution for month of October 2025
15th November – Quarterly TDS certificate for the quarter ending September 30, 2025
20th November – GSTR-3B for month of October 2025
29th November – File Form MGT-7/7A for companies and OPCs for FY 2024-25
30th November – File Form No. 3CEAA by a constituent entity of an international group for FY 2024-25
30th November – Due Date for ITR filing ( TP Cases)
Disclaimer: Information in this note is intended to provide only a general update of the subjects covered. It is not intended to be a substitute for detailed research or the exercise of professional judgment. KNM accepts no responsibility for loss arising from any action taken or not taken by anyone using this publication. Updates for the period 30.10.2025
CBDT extends specified date for filing of various reports of audit for the assessment year 2025-26
Section 220, read with section 119 of the Income-tax Act, 1961 – waiver of interest payable under section 220(2) due to late payment of demand
Goods And Service Tax (GST)
Circular No. 251/08/2025 – GST [F. No CBIC – 0001/3/2025 – GS – GST]: Clarification on various doubts related to treatment of secondary or post-sale discounts under GST, dated 12-09-2025
Notification No. 13/2025-Central Tax, dated 17-09-2025, makes amendments to CGST Rules 2025 (rules 31A, 39, 91, 110, 111, 113), inserts Rule 110A, updates Forms GSTR-9 & 9C, adds Forms GST APL-02A & 04A, and substitutes Forms GST APL-05, 06 & 07
Notification S.O. 4220(E), dated 17-09-2025, extends the time to file GST Tribunal appeals till 30-06-2026 for orders communicated before 01-04-2026, and sets a 3-month limit for orders communicated after 01-04-2026
Press release, dated 24-09-2025: Union minister of finance and corporate affairs Smt. Nirmala Sitharaman launches goods and services tax appellate tribunal in New Delhi
Companies Act 2013/ Other Laws
Fast-track mergers: Expansion of scope
Companies (Incorporation) Second Amendment Rules, 2025
MCA extends last date for filing DIR-3 KYC and DIR-3-KYC-WEB
Ease of Doing Investment – Smooth Transmission of Securities from Nominee to Legal Heir
Investor Protection and Education Fund (IPEF) Regulations, 2025
Share Based Employee Benefits (SBEB) Regulations
Compliance Guidelines for Digital Accessibility Circular ‘Rights of Persons with Act, 2016 and rules made thereunder
A. CBDT EXTENDS SPECIFIED DATE FOR FILING OF VARIOUS REPORTS OF AUDIT FOR THE ASSESSMENT YEAR 2025-26 [25-09-2025]
The ‘specified date’ of furnishing of the report of audit under any provision of the Income-tax Act, 1961, for the Previous Year 2024-25 (Assessment Year 2025-26), in the case of assessee referred to in clause (a) of Explanation 2 to sub-section (1) of section 139 of the Act, is 30th September 2025. However, keeping in view representations by Tax practitioners and submissions before Hon’ble Courts, the ‘specified date’ is extended to 31st October, 2025.
B. SECTION 220, READ WITH SECTION 119 OF THE INCOME-TAX ACT, 1961 – WAIVER OF INTEREST PAYBLE UNDER SECTION 220(2) DUE TO LATE PAYMENT OF DEMAND [19-09-2025]
The provisions of section 115BAC(1A) of the Income-tax Act, 1961 are subject to other provisions of Chapter XII. Incomes chargeable to tax at special rates under Chapter XII are excluded while determining tax liability under section 115BAC(1A). Clause (b) proviso to section 87A applies to incomes chargeable under section 115BAC(1A).
In certain cases, returns were processed allowing rebate under section 87A erroneously on incomes taxed at special rates; rectifications to disallow rebate will cause demands to be raised. Payment delays will attract interest under section 220(2).
The Board, under section 119, directs waiver of interest under section 220(2) if payment of demands raised by rectification orders is made on or before 31.12.2025. Failure to pay will attract interest from next day after expiry of this period.
A. CIRCULAR NO. 251/08/2025 – GST [F. NO CBIC – 0001/3/2025 – GS – GST]: CLARIFICATION ON VARIOUS DOUBTS RELATED TO TREATMENT OF SECONDARY OR POST-SALE DISCOUNTS UNDER GST, DATED 12-09-2025
Clarifications on Secondary / Post-Sale Discounts (u/s 168 of CGST Act, 2017)
ITC on Financial/Commercial Credit Notes
Recipients eligible for full ITC even if supplier issues financial/commercial credit notes
Suppliers cannot reduce tax liability; recipient need not reverse ITC
Post-Sale Discounts – Treatment as Consideration
Normally, discount is not considered for dealer’s sale to end customer (principal-to-principal basis)
If manufacturer has agreement with end customer (dealer passing discount), discount is a reward and part of consideration
Post-Sale Discounts vs. Promotional Services
Discount reduces sale price; not treated as payment for promotional services
GST applies only if dealer provides specific promotional services with separate consideration
Action Points
Trade notices to be issued for uniformity
Difficulties, if any, to be reported to Board
B. NOTIFICATION NO. 13/2025-CENTRAL TAX, DATED 17-09-2025
Rule / Form
Old Provision
New / Amended Provision (2025)
Effective From
Short title & commencement
N/A
Called CGST (Third Amendment) Rules, 2025
22nd Sept 2025
Rule 31A (2)
Figure 128
Figure 140
22nd Sept 2025
Rule 39 (1A)
Section 9 CGST only
Section 9 CGST and Section 5(3)/(4) IGST
1st April 2025
Rule 91 (2)
Refund order timelines not specified clearly
FORM GST RFD-04 to be issued within 7 days; officer may deny provisional refund; no revalidation needed
1st Oct 2025
Rule 110
FORM GST APL-02; provisos included
Part A / Part B of FORM GST APL-02A; provision omitted
22nd Sept 2025
Rule 110A (new)
N/A
Single Member Bench for appeals; question of law sent back; ₹50 lakh cumulative limit for ITC/tax/fine considered
22nd Sept 2025
Rule 111
FORM GST APL-02; provisos included self-certified copy
Part A / Part B of FORM GST APL-02A; provisos omitted; self-attested copy
22nd Sept 2025
Rule 113 (2)
No specific summary form
Summary of order in FORM GST APL-04A with final demand
Added rows for e-commerce tax (s. 9(5)); “paid” → “payable”; “cash” → “cash or ITC”; late fee row added
FY 2024-25
New/ Substituted Forms
APL-02, APL-04, APL-05, APL-06, APL-07
FORM GST APL-02A, APL-04A, revised APL-05, APL-06, APL-07
22nd Sept 2025
C. NOTIFICATION S.O. 4220(E), DATED 17-09-2025
Extends the time to file GST Tribunal appeals till 30-06-2026 for orders communicated before 01-04-2026
Sets a 3-month limit for orders communicated after 01-04-2026
D. PRESS RELEASE, DATED 24-09-2025: UNION MINISTER OF FINANCE AND CORPORATE AFFAIRS SMT. NIRMALA SITHARAMAN LAUNCHES GOODS AND SERVICES TAX APPELLATE TRIBUNAL IN NEW DELHI
Independent forum for GST dispute resolution ensuring fair, fast, and transparent justice
Tribunal structure: 31 State Benches + Principal Bench in New Delhi; Bench composition: 2 Judicial + 1 Centre Technical + 1 State Technical Member
Digital features: GSTAT e-Courts portal for online filings, case tracking, virtual hearings; filing window extended to 30th June 2026
Benefits: Swift resolution, reduced delays, consistent rulings, and strengthened trust between taxpayers and government
A. FAST-TRACK MERGERS: EXPANSION OF SCOPE
Through MCA notification G.S.R. 603(E) dated 4th September 2025, the scope of fast-track mergers under Section 233 was expanded through the Companies (Compromises, Arrangements and Amalgamations) Amendment Rules, 2025. The amendment allows a wider range of companies to adopt the fast-track route, reducing burden on NCLTs and shifting simpler cases to Regional Directors. Inclusions include mergers between holding and subsidiary companies (not wholly owned, if transferor not listed), mergers between unrelated unlisted companies as per borrowing/compliance thresholds, and mergers between fellow subsidiaries under common control. This facilitates quicker restructuring and ease of doing business.
B. COMPANIES (INCORPORATION) SECOND AMENDMENT RULES, 2025
MCA notified Companies (Incorporation) Second Amendment Rules, 2025 effective 15th September 2025, substituting the existing Form RD-1 with a revised format, streamlining filings with Regional Director. These reflect efforts to simplify corporate procedures and enhance governance under Companies Act, 2013.
C. MCA EXTENDS LAST DATE FOR FILING DIR-3 KYC AND DIR-3-KYC-WEB
MCA issued General Circular No. 04/2025 dated 29 September 2025, extending due date for e-Form DIR-3 KYC and DIR-3 KYC-WEB without late fee from 30 September 2025 to 15 October 2025, responding to stakeholder requests for more compliance time.
A. EASE OF DOING INVESTMENT – SMOOTH TRANSMISSION OF SECURITIES FROM NOMINEE TO LEGAL HEIR
In India, securities holders nominating persons leads securities to pass first to nominee, who must transmit to legal heirs.
Transmission from nominee to legal heir sometimes treated as capital gain transfer, causing tax complications and delays, though section 47 clause (iii) excludes this transmission from transfer definition.
SEBI circular SEBI/HO/MIRSD/MIRSD-PoD/P/CIR/2025/130 (dated 19 September 2025) clarifies and simplifies this process.
B. INVESTOR PROTECTION AND EDUCATION FUND (IPEF) REGULATIONS, 2025
On 2 September 2025, SEBI amended IPEF Regulations, revising categories for Fund credit (Reg 4) and streamlining utilization framework (Reg 5) for investor education, awareness, and protection. The amendments reflect SEBI’s focus on retail investor confidence and market safeguarding.
C. SHARE BASED EMPLOYEE BENEFITS (SBEB) REGULATIONS
SEBI notified amendments on 8 September 2025, refining governance, transparency, and disclosure for employee stock options and benefit schemes, tightening compliance and clarifying disclosures to protect employees and shareholders.
D. COMPLIANCE GUIDELINES FOR DIGITAL ACCESSIBILITY CIRCULAR ‘RIGHTS OF PERSONS WITH ACT, 2016 AND RULES MADE THEREUNDER
SEBI circular dated 31 July 2025 mandated digital accessibility for Regulated Entities’ digital platforms per the Rights of Persons with Disabilities Act, 2016. The 25 September 2025 circular (No. 131) provides compliance guidelines including clarifications, roadmap, reporting, and responsibilities to remove barriers for investors with disabilities.
Disclaimer: Information in this note is intended to provide only a general update of the subjects covered. It is not intended to be a substitute for detailed research or the exercise of professional judgment. KNM accepts no responsibility for loss arising from any action taken or not taken by anyone using this publication. Updates for the period 30.09.2025
Section 143- Processing of Return filed under section 139 beyond the prescribed time limit.
Section 143- Guidelines for compulsory selection of returns for complete scrutiny during FY 2025-26.
Goods And Service Tax (GST)
Generation and quoting of document identification number (DIN) on any communication issued by the officers of the central board of indirect taxes and customs to taxpayers and other concerned persons, Circular no. 249/06/2025-gst [F No. GST/INV/UTILITY/2022-23], dated 9-6-2025
Guidelines for mandatory conduct of personal hearings through virtual mode in all proceedings under the Delhi GST Act, 2017 and the Rules framed there under, Circular No. F.3 (640)/GST/ P & R/2025/348-55, dated 13-06-2025
Circular No. 250/07/2025-GST dated 24-06-25, Reviewing authority, Revisional Authority and Appellate Authority in respect of orders passed by Common Adjudicating Authority (CAA) for show cause notices issued by DGGI
Companies Act 2013/ Other Laws
MCA revamps corporate reporting with new disclosure norms effective July 14, 2025
Companies (audit and auditors) amendment rules, 2025 – amendment in rule 13; substitution of forms ADT-1, ADT-2, ADT-3 and ADT-4
Companies (registration offices and fees) amendment rules, 2025 – substitution of form GNL-1
Companies (filing of documents and forms in extensible business reporting language) amendment rules, 2025 – amendment in rule 3; substitution of E-form AOC-4 XBRL
Limited relaxation from compliance with certain provisions of the SEBI (listing obligations and disclosure requirements) regulations, 2015
Modifications Under The International Financial Services Centres Authority (Anti Money Laundering, Counter-Terrorist Financing And Know Your Customer) Guidelines, 2022
A. Section 143, Read with sections 119 and 139 of the Income Tax Act, 1961- Assessment- Processing of Return filed under Section 139 beyond prescribed time limit, Dated 09-06-2025
Central Board of Direct Taxes, in exercise of its powers under section 119(2)(a) of the Income-tax Act,1961, hereby relaxes the time-frame prescribed in second proviso to sub-section (1) of section 143 of the Act and directs that electronically filed valid returns of income filed u/s 139 of the Act for Assessment Years (AY) 2023-24, for which date of sending intimation under sub-section (1) of section 143 of the Act has lapsed, shall be processed now and intimation under sub-section (1) of section 143 of the Act shall be sent to the assessee concerned by 31-11-2025.
The relaxation accorded above shall not be applicable to the following returns:
returns selected in scrutiny;
returns remain unprocessed for any reason attributable to the assessee.
B. Section 143 of the Income Tax Act, 1961 – Scrutiny Assessment- Guidelines for compulsory selection of returns for complete scrutiny during FY 2025-26, Dated 13-06-2025
It is clarified that where return has been furnished in response to notice u/s 142(1) of the Act and such notice u/s 142(1) of the Act was issued due to the information contained in NMS Cycle/ AIS/ Statement of Financial Transactions (SFT)/ CPC-TDS information/ information received from Directorate of I&CI, such return will notbe taken up for compulsory scrutiny. Selection of such cases for scrutiny will be done through the CASS cycle.
Jurisdictional Assessing Officers (JAOs) shall upload the underlying documents for access by NaFAC in the following cases which are to be completed by NaFAC on or before 31-03-2026 and Notice u/s 143(2)/142(l) of the Act calling for information shall be served on the assessee through NaFAC in these cases’.
Cases (other than search & seizure/survey) in which notices u/s 148 of the Act have been issued where return is either furnished or not furnished in response to notice u/s 148 of the Act.
Cases in which notices u/s 142(1) of the Act calling for return, have been issued & no returns have been furnished.
Cases, where notices u/s 148 of the Act have been issued pursuant to search & seizure/survey actions conducted on or after the 1-04-2021 but before 1-09-2024, if lying outside Central Charges,
where return is furnished, the Jurisdictional Assessing Officer (JAO) concerned shall serve the Notice u/s 143(2) of the Act and Pr.CIT/Pr.DIT/CIT/DIT concerned shall ensure that such cases are transferred to central charges u/s 127 of the Act.
Where return is not furnished, these cases shall be transferred to central charges for further necessary action.
A.Generation and quoting of document identification number (DIN) on any communication issued by the officers of the central board of indirect taxes and customs to taxpayers and other concerned persons, Circular no. 249/06/2025-gst [F No. GST/INV/UTILITY/2022-23], dated 9-6-2025
CBIC had earlier made quoting of Document Identification Number (DIN) mandatory through Circulars 122/41/2019-GST and 128/47/2019-GST to ensure transparency. However, since GST portal-generated documents already contain a verifiable Reference Number (RFN) providing full details and are considered valid under Section 169(1)(d) of the CGST Act, 2017, and as per Instruction No. 4/2023-GST, it is now clarified that quoting DIN is not required for such communications. The presence of both DIN and RFN creates duplication, which is unnecessary.
B.Guidelines for mandatory conduct of personal hearings through virtual mode in all proceedings under the Delhi GST Act, 2017, and the Rules framed thereunder, Circular No. F.3 (640)/GST/ P & R/2025/348-55, dated 13-06-2025
All personal hearings to be conducted only through virtual mode (e.g., Webex, Google Meet).
Link, date & time shared in advance via email/mobile.
Taxpayers must share ID proof, vakalatnama, and ensure technical readiness.
Maintain proper decorum; hearings are legally valid under the GST & IT Act.
Hearing records sent via email, adjournments via BO portal.
Emails allowed for additional documents; physical copies if specifically needed.
In-person hearings are only in rare cases, with the Zonal In-Charge’s approval
C. Corrigendum G.S.R. 389 (E) [F.No. A-50050/264/2024-GSTAT-DOR], dated 18-6-2025, Goods and services tax appellate tribunal (procedure) rules, 2025
Background: CAA (Joint/Addl. Commissioner) adjudicates SCNs issued by DGGI (as per Notification 02/2017 & Circular 239/33/2024-GST). Earlier circulars didn’t clarify review, revision, and appeal procedure for such orders.
Clarifications Issued:
Reviewing Authority (Section 107, CGST Act): Principal/Commissioner of Central Tax under whom the CAA is posted.
Revisional Authority (Section 108, CGST Act): Same Principal/Commissioner of Central Tax under whom the CAA is posted.
Appellate Authority (Section 107, CGST Act): Commissioner (Appeals) with territorial jurisdiction of the CAA’s reporting Commissionerate (as per Table III of Notification 02/2017).
Department Representation in Appeals:
Concerned, the Principal/Commissioner shall represent the department.
May nominate a subordinate officer for filing appeals
DGGI comments on the Orders-in-Original (O-I-O) can be sought before review/revision.
D. Circular No. 250/07/2025-GST dated 24-06-25, Reviewing authority, Revisional Authority and Appellate Authority in respect of orders passed by Common Adjudicating Authority (CAA) for show cause notices issued by DGGI
Joint/Addl. Commissioners act as Common Adjudicating Authorities (CAA) for DGGI SCNs (as per Notification 02/2017 & Circular 239/33/2024-GST).
Principal/Commissioner under whom CAA is posted will be: Reviewing Authority (Sec. 107) and Revisional Authority (Sec. 108)
Appeals to be filed before the Commissioner (Appeals) of CAA’s jurisdiction.
Same Principal/Commissioner to represent the department and can authorize subordinates.
DGGI comments on the order may be taken before review/revision.
Trade notices to be issued; implementation issues to be reported to the Board.
A. MCA REVAMPS CORPORATE REPORTING WITH NEW DISCLOSURE NORMS EFFECTIVE JULY 14, 2025
The Ministry of Corporate Affairs (MCA) has notified the Companies (Accounts) Second Amendment Rules, 2025, effective from July 14, 2025, introducing significant changes to corporate disclosures and filings. Key updates include mandatory detailed disclosures in the Board’s Report on sexual harassment complaints and a statement of compliance under the Maternity Benefit Act, 1961. Companies must also submit new e-Forms capturing extracts of the Board’s Report and Auditor’s Reports in a machine-readable format alongside the full financial statements. The rules formalize the shift to electronic filing by replacing all references from “Form” to “e-Form.” These amendments aim to enhance corporate governance, ensure accountability, and enable better data analysis by regulators. Companies must promptly align their internal processes and ensure compliance, with strict penalties for false filings under Sections 448 and 449 of the Companies Act, 2013.
B. COMPANIES (AUDIT AND AUDITORS) AMENDMENT RULES, 2025 -AMENDMENT IN RULE 13; SUBSTITUTION OF FORMS ADT-1, ADT-2, ADT-3 AND ADT-4
The Companies (Audit and Auditors) Amendment Rules, 2025, notified on May 30, 2025, and effective from July 14, 2025, introduce key updates to Rule 13 of the Companies (Audit and Auditors) Rules, 2014. The amendment mandates electronic filing of the auditor’s report in Form ADT-4 by substituting clause (d) and omits clauses (e) and (f) of Rule 13(2). Additionally, Forms ADT-1, ADT-2, ADT-3, and ADT-4 have been completely revised and replaced with updated versions in the Annexure. These changes align with the government’s push for digital compliance and streamlined reporting under the Companies Act, 2013.
C.COMPANIES (REGISTRATION OFFICES AND FEES) AMENDMENT RULES, 2025 – SUBSTITUTION OF FORM GNL-1
The Companies (Registration Offices and Fees) Amendment Rules, 2025, notified via G.S.R. 360(E) on May 30, 2025, and effective from July 14, 2025, introduce a key change to the Companies (Registration Offices and Fees) Rules, 2014. The amendment substitutes the existing Form GNL-1 with a revised version in the Annexure. This change is part of the government’s continued efforts to modernize and streamline company filings under the Companies Act, 2013.
D. COMPANIES (FILING OF DOCUMENTS AND FORMS IN EXTENSIBLE BUSINESS REPORTING LANGUAGE) AMENDMENT RULES, 2025 – AMENDMENT IN RULE 3; SUBSTITUTION OF EFORM AOC-4 XBRL
The Companies (Filing of Documents and Forms in Extensible Business Reporting Language) Amendment Rules, 2025, notified on June 6, 2025, and effective from July 14, 2025, introduce key changes to XBRL filings. Companies filing financial statements in eForm AOC-4 XBRL must now also attach a signed PDF copy of the complete financial statements, including the Board’s Report, Auditor’s Report, and other documents as per Section 134 of the Companies Act, 2013. Additionally, the format of eForm AOC-4 XBRL in Annexure-I has been substituted with a revised version. These changes aim to enhance the authenticity and completeness of digital filings.
A. MODIFICATIONS UNDER THE INTERNATIONAL FINANCIAL SERVICES CENTRES AUTHORITY (ANTI MONEY LAUNDERING, COUNTER-TERRORIST FINANCING AND KNOW YOUR CUSTOMER) GUIDELINES, 2022
IFSCA’s circular dated June 5, 2025, updates its AML/CFT and KYC Guidelines to align with amended PML Rules. Key updates include:
Removal of “city council tax receipts” as address proof.
Customers using alternate address documents must submit updated OVDs within 3 months.
Regulated Entities must use KYC Identifiers from CKYCR and avoid duplicate KYC unless necessary.
Any KYC updates must be shared with CKYCR within 7 days; CKYCR will inform other linked entities.
Applies to banks, insurers, brokers, fund managers, and other financial entities.
Indian nationals’ KYC must be uploaded to CKYCR; for foreign nationals, specified documents are acceptable.
A.LIMITED RELAXATION FROM COMPLIANCE WITH CERTAIN PROVISIONS OF THE SEBI (LISTING OBLIGATIONS AND DISCLOSURE REQUIREMENTS) REGULATIONS, 2015
SEBI, via Circular No. SEBI/HO/DDHS/DDHS-PoD-1/P/CIR/2025/83 dated June 5, 2025, has extended relaxation from compliance with Regulation 58(1)(b) of the SEBI LODR Regulations for listed entities with non-convertible securities. This regulation mandates sending hard copies of salient financial document summaries to security holders without registered email IDs.
In line with MCA’s General Circular No. 9/2024, SEBI has:
Exempted penal action for non-sending of hard copies during the period October 1, 2024 to June 5, 2025, provided MCA conditions are met.
Extended similar relaxation from June 6 to September 30, 2025, on the condition that web-links to the financial summaries are provided in advertisements as per Regulation 52(8).
This circular is effective immediately and aims to reduce compliance burden while ensuring digital accessibility of financial information.
Disclaimer:Information in this note is intended to provide only a general update of the subjects covered. It is not intended to be a substitute for detailed research or the exercise of professional judgment. KNM accepts no responsibility for loss arising from any action taken or not taken by anyone using this publication. Updates for the period 31.05.2025
MCA issued Companies (Cost Records and Audit) Amendment Rules, 2025
Ministry of Corporate Affairs amends Annual Filing Forms MGT-7, MGT-7A, and MGT-15
Insolvency and Bankruptcy Board of India amends The Insolvency and Bankruptcy Board of India (Insolvency Resolution Process for Corporate Persons) Regulations, 2016
Reporting on Firms Portal – Issuance of Partly Paid Units by Investment Vehicles
Process for appointment, Re-appointment, termination, or acceptance of resignation of specific Key Management
Personnel (KMPs) of a Market Infrastructure Institution (MII) – Cooling-Off Period for KMPs of an MII joining a Competing MII – Provision relating to re-appointment of Public Interest Directors (PIDs)
A. Section 37(1) of the Income Tax Act, 1961- Enforcement of Section 152 and 153, Dated 06-05-2025
In exercise of the powers conferred by section 151 of the Finance Act, 2017 (7 of 2017), the Central Government hereby appoints the 9th day of May, 2025 as the date on which sections 152 and 153 of the said Act, relating to amendments in the Payment and Settlement Systems Act, 2007 (51 of 2007), shall come into force.
B. Section 139 of the Income Tax Act, 1961 – Extension of Due Date for furnishing Return of Income for A.Y. 2026-27, Dated 27-05-2025
The Central Board of Direct Taxes (CBDT), in exercise of its powers under Section 119 of the Income-tax Act, 1961 (‘the Act\ extends the due date of furnishing of Return of Income under sub-section (1) of section 139 of the Act for the Assessment Year 2025-26 in the case of assessees referred in clause (c) of Explanation 2 to sub-section (1) of section 139 of the Act, which is 31st July, 2025 to 15th September, 2025.
C. Income Tax Amendment Rules, 2025 – Substitution of ITR Forms
In exercise of the powers conferred by section 139, read with section 295 of the Income-tax Act, 1961 (43 of 1961), the Central Board of Direct Taxes hereby makes the following rules further to amend the Income-tax Rules, 1962, namely:
Income-Tax Twelfth Amendment Rules, 2025- Substitution of Forms- ITR 1 and ITR 4
Income-Tax Thirteenth Amendment Rules, 2025- Substitution of Forms- ITR 3
Income-Tax Fourteenth Amendment Rules, 2025- Substitution of Forms- ITR 5
Income-Tax Fifteenth Amendment Rules, 2025- Substitution of Forms- ITR 2
Income-Tax Sixteenth Amendment Rules, 2025- Substitution of Forms- ITR 6
Income-Tax Seventeenth Amendment Rules, 2025- Substitution of Forms- ITR V
Income-Tax Eighteenth Amendment Rules, 2025- Substitution of Forms- ITR 7
Income-Tax Nineteenth Amendment Rules, 2025- Substitution of Forms- ITR U
A. Grievance redressal mechanism for processing of application for GST registration, Instruction no. 4/2025 – GST [F.No. CBIC – 20016/24/2025 – GST], dated 02-05-2025
Grievance Redressal for GST Registration – Central Jurisdiction
As per CBIC Instruction No. 3/2025 dated 17.04.2025:
Applicants under Central Jurisdiction facing issues with queries or rejection of GST registration can contact the Zonal Principal Chief Commissioner/Chief Commissioner.
For faster grievance redressal:
Zones must share a dedicated email ID for grievance submission.
Applicants should email ARN, jurisdiction (Centre/State), and the issue briefly.
If it concerns State jurisdiction, it will be forwarded to the State authority and the GST Council Secretariat.
Chief Commissioners must:
Ensure timely resolution and inform applicants.
Advise applicants if queries are valid.
Send a monthly report to DGGST for Board review.
Any implementation issues should be reported to the Board.
B. Timely production of records/information for audit Instruction no. 5/2025 – GST [F. No. CCB-20015/2/2025 – GST], dated 02-05-2025
Submission of Records to the Comptroller and Auditor General of India, Audit Teams
Report 7 of 2024 flagged non/partial sharing of records with audit teams.
As per Article 149, the Comptroller and Auditor General of India has the authority to audit the government. accounts and entities.
Field officers must provide all required records/information to the Comptroller and Auditor General of India’s audit teams without delay.
If records are with the taxpayer, send them a request letter and follow up to ensure timely submission. These issues are with the approval of the Chairman, CBIC.
A. MCA Issued Companies (Indian Accounting Standards) Amendment Rules, 2025
The Ministry of Corporate Affairs (MCA) issued a notification on May 7, 2025, enacting the Companies (Indian Accounting Standards) Amendment Rules, 2025. These rules amend the Companies (Indian Accounting Standards) Rules, 2015, primarily focusing on Indian Accounting Standard (Ind AS) 21, which deals with the effects of changes in foreign exchange rates. The amendments introduce detailed guidance on assessing whether a currency is exchangeable into another currency, estimating the spot exchange rate when a currency is not exchangeable, and the required disclosures in such circumstances. Definitions and application guidance are added to clarify terms and processes related to exchangeability for different purposes, such as reporting foreign currency transactions or translating foreign operations. Corresponding amendments are also made to Ind AS 101 regarding first-time adoption of Ind AS in the context of severe hyperinflation and non-exchangeable currencies. These amendments are applicable for annual reporting periods beginning on or after April 1, 2025, with specific transitional provisions outlined.
Effective April 1, 2025, companies delaying payments to Micro and Small Enterprises (MSEs) beyond 45 days will face.
B. MCA issued Companies (Cost Records and Audit) Amendment Rules, 2025.
The Ministry of Corporate Affairs (MCA) has issued a new notification, G.S.R. 361(E), bringing important changes to how companies manage and report their cost audits. These changes are part of the Companies (Cost Records and Audit) Amendment Rules, 2025, and will come into effect from July 14, 2025. The focus of this amendment is to replace and modernize two key forms used by companies: Form CRA-2 and Form CRA-4. These forms are used to appoint cost auditors and to file cost audit reports with the Central Government.
C. Ministry of Corporate Affairs amends Annual Filing Forms MGT-7, MGT-7A, And MGT-15
The Ministry of Corporate Affairs (MCA) has recently released an official notification dated 30th May, 2025, regarding some rules further added to amend the Companies (Management and Administration) Rules, 2014, by the Central Government of India, in exercise of its powers granted under sub-sections (1) and (2) of section 469 of the Companies Act, 2013 (18 of 2013), specifically:
These amended rules may now be called the Companies (Management and Administration) Amendment Rules, 2025.
These amendments will be made effective from the 14th day of July, 2025.
In the Companies (Management and Administration) Rules, 2014, the forms MGT-7, MGT-7A, and MGT-15 are being replaced with new e-forms.
Insolvency and Bankruptcy Board of India amends The Insolvency and Bankruptcy Board of India (Insolvency Resolution Process for Corporate Persons) Regulations, 2016
The Insolvency and Bankruptcy Board of India (IBBI/Board) has notified the Insolvency and Bankruptcy Board of India (Insolvency Resolution Process for Corporate Persons) (Fourth Amendment) Regulations, 2025 (Amendment Regulations) on 26th May, 2025. The amendments, which come into immediate effect, aim to further streamline and strengthen the corporate insolvency resolution process.
Key highlights of the Amendment Regulations are as follows:—
(i)
Facilitating part-wise resolution of Corporate Debtor: The resolution professional, with the approval of the CoC, can invite expression of interest for submission of resolution plans for the corporate debtor as a whole, or sale of one or more of the assets of the corporate debtor, or for both. By enabling concurrent invitations, the resolution process can reduce timelines, prevent value erosion in viable segments, and encourage broader investor participation.
(ii)
Harmonizing timelines for payment under the resolution plan: Where a resolution plan provides for payment in stages, the financial creditors who did not vote in favour of the resolution plan shall be paid at least pro rata and in priority over financial creditors who voted in favour of the plan, in each stage. This approach balances the legitimate rights of dissenting creditors with the practical constraints of phased implementations.
(iii)
Facilitating the providers of interim finance: CoC has been empowered to direct the resolution professional to invite the providers of interim finance to attend CoC meetings as observers without voting rights. This measure is intended to provide interim finance providers with a better understanding of the corporate debtor’s operational status, thereby enabling them to make well-informed decisions regarding funding requirements.
(iv)
Presentation of all plans before the Committee of Creditors (CoC): Resolution professionals are now required to present all resolution plans received, including those that are non-compliant, to the CoC along with relevant details. This provision ensures that the CoC has access to comprehensive information for decision-making, which may lead to more informed choices and ultimately contribute to a more transparent and effective resolution process.
FEMA
Reporting on Firms Portal – Issuance of Partly Paid Units by Investment Vehicles
Investment vehicles issuing partly paid units to non-residents must report these transactions on the FIRMS (Foreign Investment Reporting and Management System) portal using Form InVI. A special one-time window allows for reporting within 180 days from the date of the circular for issuances before May 23, 2025, without late submission fees. Issuances made on or after May 23, 2025, must be reported within 30 days, as per existing regulations.
A. Process for appointment, Re-appointment, termination, or acceptance of resignation of specific Key Management Personnel (KMPs) of a Market Infrastructure Institution (MII) – Cooling-Off Period For KMPs of an MII joining a Competing MII – Provision relating to re-appointment of Public Interest Directors (PIDs)
Market Infrastructure Institutions (MIIs) such as stock exchanges, clearing corporations, and depositories. Here’s an overview of the key provisions concerning the appointment, reappointment, termination, and cooling-off periods for Key Management Personnel (KMPs) and Public Interest Directors (PIDs
Appointment, Reappointment, and Termination of Specific KMPs
SEBI has mandated that the appointment, reappointment, or termination of specific KMPs—including the Compliance Officer (CO), Chief Risk Officer (CRO), Chief Technology Officer (CTO), and Chief Information Security Officer (CISO)—must receive approval from the Governing Board of the MII. Previously, these decisions were within the purview of the Nomination and Remuneration Committee (NRC) of the MII.
Cooling-Off Period for KMPs and Directors Joining Competing MIIs
The Governing Board of an MII may prescribe a minimum cooling-off period for its KMPs and Directors—including the Managing Director (MD) and PIDs—before they can join a competing MII. However, SEBI will no longer prescribe a mandatory cooling-off period for PIDs transitioning from one MII to another.
Reappointment of Public Interest Directors (PIDs)
The existing process for the appointment of PIDs, which requires prior approval from SEBI but does not mandate shareholder approval, will continue. If the Governing Board of an MII decides not to reappoint an existing PID after their first term, it must record the rationale for this decision and communicate it to SEBI.
DisclaimerInformation in this note is intended to provide only a general update of the subjects covered. It is not intended to be a substitute for detailed research or the exercise of professional judgment. KNM accepts no responsibility for loss arising from any action taken or not taken by anyone using this publication. Updates for the period 31.05.2025
Enhanced Disclosures by Foreign Portfolio Investors (FPIs)
A. SECTION 37(1) OF THE INCOME-TAX ACT, 1961 – BUSINESS EXPENDITURE – ALLOWABILITY OF – NO DEDUCTION OF ALLOWANCE IN RESPECT OF EXPENSES INCURRED TO SETTLE PROCEEDINGS UNDER NOTIFIED LAWS, DATED 23-04-2025
In exercise of the powers conferred by clause (iv) of Explanation 3 of sub-section (1) of section 37 of the Income-tax Act, 1961 (43 of 1961), the Central Government hereby notifies that any expenditure incurred to settle proceedings initiated about contravention or defaults under the following laws shall not be deemed to have been incurred for business or profession and no deduction or allowance shall be made in respect of such expenditure, namely: —
(a) The Securities and Exchange Board of India Act, 1992 (15 of 1992);
(b) The Securities Contracts (Regulation) Act, 1956 (42 of 1956);
(c) The Depositories Act, 1996 (22 of 1996);
(d) The Competition Act, 2002 (12 of 2003).
This notification shall come into force on the date of its publication in the Official Gazette.
B. SECTION 89(1)(L) OF THE FINANCE (NO.2) ACT, 2024 – LAST DATE FOR FILING DECLARATION IN RESPECT OF TAX ARREAR TO DESIGNATED AUTHORITY, DATED 08-04-2025
In exercise of the powers conferred by clause (l) of sub-section (1) of section 89 of the Finance (No. 2) Act, 2024 (15 of 2024), the Central Government hereby notifies under the Direct Tax Vivad se Vishwas Scheme, 2024, the 30th day of April, 2025 as the last date, on or before which a declaration in respect of tax arrears shall be filed by the declarant to the designated authority, per the provisions of section 90 of the said Act.
C. SECTION 54EC OF THE INCOME-TAX ACT, 1961 – CAPITAL GAINS NOT TO BE CHARGED ON INVESTMENT IN CERTAIN BONDS – NOTIFIED BONDS, DATED 07-04-2025
In exercise of the powers conferred by clause (ba) of Explanation to section 54EC of the Income-tax Act, 1961 (43 of 1961), the Central Government hereby notifies that bonds redeemable after five years and issued on or after 1st day of April, 2025, by the Housing and Urban Development Corporation Limited (HUDCO) (a public financial institution notified by the Central Government under section 2(72) of the Companies Act, 2013), as ‘long-term specified asset’ for the said section.
HUDCO shall utilize the proceeds from such bonds only for those infrastructure projects that can service the debt out of the project revenues without being dependent on the State Governments for the service of debts.
D. INCOME-TAX (NINTH AMENDMENT) RULES, 2025 – AMENDMENT IN RULE 114, DATED 03-04-2025
In exercise of the powers conferred by sub-section (2A) of section 139AA, read with section 295 of the Income-tax Act, 1961 (43 of 1961), the Central Board of Direct Taxes hereby makes the following rules further to amend the Income-tax Rules, 1962, namely:—
(1) These rules may be called the Income-tax (Ninth Amendment) Rules, 2025.
(2) They shall come into force with effect from the date of their publication in the Official Gazette.
In the Income-tax Rules, 1962, in rule 114, after sub-rule (5A), the following shall be inserted, namely:—
“(5AA) Every person who has been allotted permanent account number on the basis of Enrolment ID of Aadhaar application form filed prior to the 1st day of October, 2024, shall intimate his Aadhaar number to the Principal Director General of Income-tax (Systems) or Director General of Income-tax (Systems) or the person authorized by the said authorities.”
Such intimation shall be made on or before the 31st day of December, 2025 or such date as may be specified by the Central Board of Direct Taxes in this behalf.
E. INCOME-TAX (TENTH AMENDMENT) RULES, 2025 – INSERTION OF RULE 12AE AND FORM ITR-B, DATED 07-04-2025
In exercise of the powers conferred by section 158BC, read with section 295 of the Income-tax Act, 1961, the Central Board of Direct Taxes hereby makes the following rules further to amend the Income-tax Rules, 1962, namely:—
(1) These rules may be called the Income-tax (Tenth Amendment) Rules, 2025.
(2) They shall be deemed to have come into force on the 1st day of September 2024.
In the Income-tax Rules, 1962, after rule 12AD, the following rule shall be inserted, namely: ––
“12AE. Return of income under section 158BC.—
(1) The return of income required to be furnished by any person under clause (a) of sub-section (1) of section 158BC, relating to any search initiated under section 132 or requisition made under section 132A on or after the 1st day of September, 2024 shall be in the Form ITR-B and be verified in the manner indicated therein.
(2) The return of income referred to in sub-rule (1) shall be furnished by a person, mentioned in column (2) of the Table below in the manner specified in column (3) thereof: ––
S.
No.
Person
Manner of furnishing return of income
1
(a) person whose accounts are required to be audited under section 44AB of the Act;
(b) Company;
(c) Political party.
Electronically under a digital signature.
2
Any person other than a person mentioned in column (2) of Sl. No. (1) above.
(A) Electronically under a digital signature;
(B) Transmitting the data electronically in the return under an electronic verification code.
(3) The Principal Director-General of Income-tax (Systems) or Director-General of Income-tax (Systems) shall specify the procedures, formats and standards for ensuring secure capture and transmission of data and shall also be responsible for evolving and implementing appropriate security, archival and retrieval policies in relation to furnishing the return in the manners specified in column (3) of the Table.
(4) In a case where the claim of credit of the tax payments is made against undisclosed income of the block period other than by way of self-assessment tax for the block period, claim of such credits and the allowability thereof shall be subject to the verification by and satisfaction of, the Assessing Officer.”
F. INCOME-TAX (ELEVENTH AMENDMENT) RULES, 2025 – AMENDMENT IN FORM NO. 27EQ, DATED 21-04-2025
In exercise of the powers conferred by section 295, read with section 206C of the Income-tax Act, 1961 (43 of 1961), the Central Board of Direct Taxes hereby makes the following rules further to amend the Income-tax Rules, 1962, namely: —
(1) These rules may be called the Income-tax (Eleventh Amendment) Rules, 2025.
(2) They shall come into force on the date of their publication in the Official Gazette.
In the Income-tax Rules, 1962, in Form No. 27EQ, in the Annexure, in the Notes thereto, in Note 11, in the table, after the row relating to “Collection at source on sale of motor vehicle”, the following shall be inserted, namely:—
206C
Collection at source on the sale of a wristwatch
6C
MA
206C
Collection at source on sale of art pieces such as antiques, paintings, sculptures
6C
MB
206C
Collection at source on sale of collectibles such as coins, stamps
6C
MC
206C
Collection at source on sale of a yacht, rowing boat, canoe, and a helicopter
6C
MD
206C
Collection at source on the sale of a pair of sunglasses
6C
ME
206C
Collection at source on the sale of bags such as handbags, purses
6C
MF
206C
Collection at source on the sale of a pair of shoes
6C
MG
206C
Collection at source on sale of sportswear and equipment such as golf kit, ski wear
6C
MH
206C
Collection at source on the sale of a home theatre system
6C
MI
206C
Collection at source on the sale of horses for horse racing in race clubs, and horses for polo
6C
MJ”.
G. SECTION 206C OF THE INCOME TAX ACT, 1961 – TCS- NOTIFIED GOODS EXCEEDING SPECIFIED VALUE IN RESPECT OF WHICH COLLECTION OF TAX SHALL BE MADE UNDER SUB-SECTION (1F) OF SAID SECTION, DATED 22-04-2025
In exercise of the powers conferred by clause (ii) of sub-section (1F) of section 206C of the Income-tax Act, 1961 (43 of 1961), the Central Government hereby notifies the following goods of the value exceeding ten lakh rupees for collection of tax at source as specified therein —
Sl. No.
Nature of goods
1.
Any wristwatch
2.
Any art piece, such as antiques, paintings, sculptures
3.
Any collectibles such as coins, stamps
4.
Any yacht, rowing boat, canoe, or helicopter
5.
Any pair of sunglasses
6.
Any bag, such as a handbag, purse
7.
Any pair of shoes
8.
Any sportswear and equipment such as golf kit, ski wear
9.
Any home theatre system
10.
Any horse for horse racing in race clubs and horses for polo
This notification shall come into force on the date of its publication in the Official Gazette.
A. NOTIFICATION NO. 11/2025- CENTRAL GOODS AND SERVICES TAX (SECOND AMENDMENT) RULES, 2025 – AMENDMENT IN RULE 164, DATED 27-03-2025
Central Goods and Services Tax (Second Amendment) Rules, 2025 – Key Changes:
Amendments to Rule 164:
Changes in Sub-rule (4):
No Refund: No refund will be granted for any tax, interest, or penalty already paid for periods before the 2025 amendment.
Partial Withdrawal of Appeal: If an appeal involves both eligible (1st July 2017 – 31st March 2020) and non-eligible periods, the applicant can choose to opt out only for the eligible period.
Changes in Sub-rule (7):
No Need to Fully Withdraw Appeal: The applicant does not have to withdraw the entire appeal; they only need to inform the authority about opting out for the eligible period.
Deemed Withdrawal: The appeal will be considered withdrawn only to the extent of the eligible period (1st July 2017 to 31st March 2020).
CIRCULAR NO. 248/05/2025 – GST, VARIOUS ISSUES RELATED TO AVAILMENT OF BENEFIT OF SECTION 128A OF THE CGST ACT, 2017, DATED 27-03-2025
Sno.
Section
Details
1
Background
Section 128A and Rule 164 inserted w.e.f. 1st November 2024 to provide waiver of interest/penalty for demands under Section 73 for period 1st July 2017 – 31st March2020. Circular No. 238/32/2024-GST issued earlier for implementation.
2
Issues Raised
1. Eligibility where payment made through GSTR-3B instead of DRC-03.
2. Treatment of appeals covering periods inside and outside Section 128A.
3
Issue 1: GSTR-3B Payments
– Payments made through GSTR-3B before 1st November 2024 are eligible for benefit under Section 128A.
– Payments after 1st November 2024 must be made via DRC-03 as per Rule 164.
– Eligibility is subject to verification by the proper officer.
4
Issue 2: Mixed Period Appeals
– If notice/order covers both eligible (FY 2017–18 to FY 2019–20) and non-eligible periods:
→ Taxpayer files SPL-01 or SPL-02 after payment.
→ Intimate appellate authority that appeal is not pursued for eligible period.
→ Appellate authority to pass order only for non-eligible period.
INSTRUCTION NO. 3.2025 – GST, INSTRUCTIONS FOR PROCESSING APPLICATIONS FOR GST REGISTRATION, , DATED 17-04-2025
Sl. No.
Topic
Key Points
1
Background
Complaints of delays; extra documents asked; aim to stop fake firms and protect genuine applicants.
2
Problems Identified
Irregular checks; unnecessary clarifications; issues around PPOB, Business Constitution, Identity proofs.
3
Documents Officers Can Ask
(As per FORM GST REG-01) – Owned Premises: Property Tax/Katha/Electricity/Water Bill. – Rented Premises: Rent Agreement + Lessor’s property proof. – Shared Premises: Consent Letter + Property + ID Proof. – No Agreement: Affidavit + Electricity/Water Bill. – SEZ: SEZ Authorization. – No PAN, Aadhaar, or property photos needed; one document sufficient.
4
Business Constitution Proof
– Partnership Firm: Partnership Deed. – Society/Trust/Club/Govt Bodies: Registration Certificate. – No need for MSME, Udyam, Trade License.
5
Processing Applications
– Non-risky: Approve in 7 working days. – Risky (flagged/Aadhaar issues): Approve post physical verification within 30 working days. – Verification must include GPS photos, uploaded 5 days before the 30-day limit. – Verify address through public records.
6
Clarifications (Form REG-03)
Only for incomplete, illegible, mismatched, vague address or cancelled GSTIN cases.
7
Applicant Response (Form REG-04)
You must reply within 7 working days; else application can be rejected.
8
Officer Action
If reply is OK ➔ Approve in 7 working days; if not ➔ Reject via REG-05 with reasons.
9
Timely Action
No deemed approvals allowed; officers must act promptly.
10
Restrictions on Queries
No minor/irrelevant queries unless approved by Deputy/Assistant Commissioner.
11
Senior Officer Supervision
Regular monitoring of registration, physical verifications, and compliance.
12
Adequate Staffing
Staff must be sufficient to avoid delays.
13
Trade Notices
Issue local clarifications for acceptable documents.
PRESS RELEASE, GOVERNMENT IS NOT CONSIDERING LEVYING GOODS AND SERVICES TAX (GST) ON UPI TRANSACTIONS OVER INR 2000, DATED 18-04-2025
No GST is being proposed on UPI transactions above INR 2,000; claims are false and baseless.
GST is charged only on payment service charges like MDR (Merchant Discount Rate),not on UPI transactions.
Since January 2020, MDR has been removed for Person-to-Merchant (P2M) UPI transactions by CBDT.
As no MDR is charged on UPI P2M payments, no GST applies on such transactions.
Government promotes UPI growth through an Incentive Scheme supporting low-value P2M transactions:
FY 2021-22: INR 1,389 crore
FY 2022-23: INR 2,210 crore
FY 2023-24: INR 3,631 crore
India leads in digital payments: 49% of global real-time transactions (as per ACI Worldwide Report 2024).
UPI transaction value has grown massively:
From INR 21.3 lakh crore (FY 2019-20) ➔ to INR 260.56 lakh crore (FY 2024-25).
Applicable from 24th April 2025 for GSTAT procedures.
2
Appeal Filing
Appeals must be filed electronically on the GSTAT Portal with certified copies.
3
Registrar’s Role
Registrar to manage appeal registration, hearings, and records.
4
Hearings
Hearings can be physical, virtual, or hybrid; dismissal if parties absent.
5
Conduct Rules
Tribunal members and representatives must follow the dress code and conduct standards.
6
Applications
Stay, rectification, and other applications to be filed via GSTAT Form-01.
7
Document Management
Proper record maintenance; special rules for affidavits and evidence.
8
Order Pronouncement
Tribunal to pronounce orders within 30 days after final hearing.
9
Fees and Costs
Prescribed fees for filing/inspection; no fees for government cases.
10
Record Retention
Case records to be retained for 15 years; special procedural directions allowed.
STRICTER COMPLIANCE FOR DELAYED PAYMENTS TO MSMEEffective April 1, 2025, companies delaying payments to Micro and Small Enterprises (MSEs) beyond 45 days will face.
Mandatory MCA Filings: Companies must file a half-yearly return (Form MSME-1) detailing outstanding dues exceeding 45 days.
Interest Penalties: Compound interest at three times the RBI bank rate (approximately 18%) will be levied on delayed payments.
Tax Disallowance: Interest paid on delayed payments will not be allowed as a business expense under Section 43B(h) of the Income Tax Act.
Applicability:
Applies to companies procuring goods or services from MSEs registered under Udyam Registration.
Does not apply to medium enterprises.
A. SECOND AMENDMENT TO CIRP REGULATIONS
On April 3, 2025, the IBBI introduced the Second Amendment to the Insolvency Resolution Process for Corporate Persons (CIRP) Regulations, 2016. The key change involves the revision of Form H (Compliance Certificate), requiring resolution professionals to provide more detailed disclosures. This includes information on the successful resolution applicant, plan implementation strategies, and income tax loss details, aiming to enhance transparency in the resolution process.
B. FOCUS ON REAL ESTATE IN CIRP
In amendments effective from February 3, 2025, the IBBI addressed challenges in real estate insolvency cases. Notable provisions include:
Allowing resolution professionals to hand over possession of properties to homebuyers during the resolution process.
Permitting land authorities to participate in the Committee of Creditors (CoC) meetings.
Mandating resolution professionals to prepare a report on real estate development rights within 60 days to aid informed decision-making.
FEMA
A. CAPPING OF PENALTIES FOR FEMA VIOLATIONS
The RBI has amended its compounding framework under FEMA, introducing a cap of ₹2 lakh per contravention for specific regulatory violations. This move aims to simplify compliance and encourage voluntary disclosures.
Key Highlights:
Applicable Violations: Includes delays in repatriation of export proceeds, non-repatriation of Liberalised Remittance Scheme (LRS) proceeds within 180 days, and issuance of high-value shares as gifts without RBI approval.
Discretionary Powers: Compounding authorities have the discretion to impose reduced penalties based on the nature of the contravention and public interest considerations.
Legal Framework: Guided by Section 15 of FEMA, 1999, allowing the RBI to compound contraventions upon application by the violator.
A. ENHANCED DISCLOSURES BY FOREIGN PORTFOLIO INVESTORS (FPIs)
On April 9, 2025, SEBI amended its circular mandating additional disclosures by FPIs that meet certain objective criteria. This amendment aims to bolster transparency and regulatory oversight of foreign investments in Indian markets.
Disclaimer:Information in this note is intended to provide only a general update of the subjects covered. It is not intended to be a substitute for detailed research or the exercise of professional judgment. KNM accepts no responsibility for loss arising from any action taken or not taken by anyone using this publication. Updates for the period 30.04.2025.
Revised Income Tax Slab under Section 115BAC rates effective from April 1st, 2025.
Changes in provisions of Tax Deducted at Source.
Key changes in Tax Collected at Source (TCS) provisions effective April 1st, 2025.
New Limits for Partnership Firms under Section 40b.
Other Changes made in the Income Tax Act, 1961, effective from April 1st, 2025.
Goods And Service Tax (GST)
Section 3, read with section 5 of the Central Goods and Services Tax Act, 2017, and section 3 of the Integrated Goods and Services Tax Act, 2017 – officers under this act – powers of officers – appointment of officers – amendment in notification no. 2/2017-central tax, dated 19-6-2017
Notification No. 16/2024-Central Tax, dated August 6, 2024, which makes ISD provisions mandatory from April 1, 2025.
Companies Act 2013/ Other Laws
directs all companies to submit a half-yearly MCA return for delayed MSE payments exceeding 45 days
Revises investment and turnover criteria for classifying enterprises as MSMEs
IBBI Mandates Detailed Disclosure of Carry Forward Losses in Information Memorandum
SEBI Amends LODR Regulations, 2015; Increases HVDLE Threshold to ₹1,000 Crore
SEBI Amends PIT Regulations, Expands Scope of Unpublished Price Sensitive Information (UPSI)
INCOME TAX CHANGES EFFECTIVE FROM APRIL 1ST, 2025:
The Budget 2025 introduced some major changes to the Income Tax Act 1961 to simplify the tax structure in India. These changes will come into effect on 1st April 2025 and will be relevant from FY 2025-26 onwards.
A. REVISED INCOME TAX SLAB RATES
The Budget 2025 proposed new tax slab rates under section 115BAC, i.e., the New Tax Regime or the Default Tax Regime. This was to ensure that individuals save more and increase their spending capacity. These revised tax slab rates will be applicable for income earned in FY 2025-26 onwards.
Sl .No.
Total Income (in lacs)
Rate of tax u/s 115BAC(1A)
1.
Upto 4,00,000
Nil
2.
4,00,001 to 8,00,000
5%
3.
8,00,001 to 12,00,000
10%
4.
12,00,001 to 16,00,000
15%
5.
16,00,001 to 20,00,000
20%
6.
20,00,001 to 24,00,000
25%
7.
Above 24,00,000
30%
Rebate under Section 87A has been increased to ₹60,000 (previously ₹25,000). The threshold has been increased from Rs. 7,00,000 to 12,00,000
B. CHANGES IN TDS THRESHOLDS
Significant changes in the provisions of Tax Deducted at Source (TDS) will take effect from April 2025. One of the key proposals includes an increase in the threshold limits for various TDS sections, benefiting both individuals and businesses. The revised TDS thresholds for different sections are as follows:
Section
Description
Previous Thresholds (in INR)
Revised Thresholds (in INR)
193
Interest on Securities
Nil
10,000
194A
Interest
– Senior Citizens
– When payer is bank, Cooperative society & post office
– Others
50,000
40,000
5,000
100,000
50,000
10,000
194
Dividend
50,000
10,000
194K
Income in respect of units of a Mutual Fund
5,000
10,000
194B
Winnings from the Lottery
10,000 yearly (Aggregate)
10,000 in respect of the single transaction
194BB
Winnings from Horse race
10,000 yearly (Aggregate)
10,000 in respect of the single transaction
194D
Insurance Commission
15,000
20,000
194G
Income by way of commission, prize, etc. on lottery tickets
15,000
20,000
194H
Commission or brokerage
15,000
20,000
194-I
Rent
240,000 yearly
50,000 per month
194J
Professional fees or Technical Services
30,000
50,000
194LA
Income by way of Enhanced Compensation
250,000
500,000
194T
Remuneration, Interest, and Commission Paid to Partners
Sections 206AB and 206CCA, which mandated a higher TDS/TCS rate for non-filers of income tax returns, have been removed. Previously, taxpayers who had not filed their income tax returns for the last two years faced higher deduction rates. With the removal of these sections, businesses and individuals will no longer be subject to higher TDS/TCS rates for non-compliance.
C. TCS AMENDMENTS
Key changes in Tax Collected at Source (TCS) provisions effective from April 1st 2025, are as below:
Section
Description
Previous Thresholds (in INR)
Revised Thresholds (in INR)
206C(1G)
LRS/Overseas Tour
700,000
1,000,000
206C(1G)
Education Loan (LRS)
700,000
Nil (NO TCS)
206C(1H)
Purchase of Goods
5,000,000
Nil (NO TCS)
D. NEW LIMITS FOR PARTNER REMUNERATION
Revised remuneration limits for partners in firms:
The government has extended the tax holiday for eligible startups under Section 80-IAC until March 31, 2030. Startups that qualify under this section will continue to enjoy a 100% deduction on profits for three consecutive assessment years out of their first ten years of incorporation, provided they meet the prescribed conditions.
IFSC Benefits – Extended Tax Concessions:
To promote financial activities in the International Financial Services Centre (IFSC), the government has extended tax concessions until March 31, 2030. This includes exemptions and tax benefits for units operating in the IFSC, making it an attractive destination for global financial businesses.
Unit Linked Insurance Plans (ULIPs) – Taxation on Proceeds:
Proceeds from Unit Linked Insurance Plans (ULIPs) will now be taxed as capital gains if:
The annual premium paid exceeds 10% of the sum assured or
The total premium across policies exceeds ₹2.5 lakh per year
This change aims to curb the misuse of high-premium ULIPs as a tax-free investment avenue while maintaining their original purpose as an insurance product.
A. SECTION 3, READ WITH SECTION 5 OF THE CENTRAL GOODS AND SERVICES TAX ACT, 2017 AND SECTION 3 OF THE INTEGRATED GOODS AND SERVICES TAX ACT,2017- OFFICERS UNDER THIS ACT- POWERS OF OFFICERS- APPOINTMENT OF OFFICERS- AMENDMENT IN NOTIFICATION NO. 2/2017- CENTRAL TAX, DATED 19-6-2017
Key Amendments to Notification No. 02/2017-Central Tax:
The Central Government hereby amends Notification No. 02/2017-Central Tax, published in the Gazette of India (G.S.R. 609(E)) dated 19th June 2017.
Madurai, Ramanathapuram, Sivagangai, Virudhunagar, Tuticorin, Tirunelveli, Tenkasi, Kanyakumari, Theni, Dindigul (excluding D. Gudalur Village of Palayam Firka of Vedasandur Taluk), Includes Tamil Nadu’s territorial waters and adjoining Puducherry waters
6.
Tiruchirapalli (Serial No. 100)
Tiruchirappalli, Perambalur, Ariyalur, Karur, Pudukottai, Thanjavur, Thiruvarur, Nagapattinam, Mayiladuthurai, Cuddalore, D. Gudalur village of Palayam Firka of Vedasandur Taluk (Dindigul District)
B.NOTIFICATION NO. 16/2024- CENTRAL TAX, DATED AUGUST 6,2024, WHICH MAKES ISD PROVISIONS MANDATORY FROM APRIL 1ST,2015
From April 1, 2025, businesses receiving input service invoices for multiple branches must register as an Input Service Distributor (ISD) and distribute ITC accordingly. This applies to shared services like audit fees, legal consultation, and software subscriptions.
Previously optional, ISD registration is now mandatory under Notification No. 16/2024-Central Tax, dated August 6, 2024. Non-compliance may lead to ITC disallowances or penalties.
Input Service Distributor
Purpose: Distributes ITC on input services (not goods or capital goods) to branches with different GSTINs under the same PAN.
Distribution Rule: ITC is allocated in proportion to branch turnover.
Tax Types: ITC is distributed as CGST, SGST, or IGST based on the recipient’s location.
Compliance:
Requires a separate GST registration.
Must file a GSTR-6 by the 13th of the following month; recipients view ITC in GSTR-6A and claim it in GSTR-3B.
GSTR-9 annual return is not required for ISD.
RCM invoices should be addressed to normal registration and not ISD registration.
The time limit to avail of ITC is based on the date of the original invoice. For example, ITC related to FY 2024-25 must be availed by November 2025.
Businesses must align SOPs, automate ITC tracking, and train staff for seamless compliance.
Documents required: Certificate of Incorporation, PAN of applicant, Identity/Address proof of Directors, Address proof of Business, Bank details, details of all GST registrations.
A. GOVERNMENT DIRECTS ALL COMPANIES TO SUBMIT HALF-YEARLY MCA RETURN FOR DELAYED MSE OAYMENTS EXCEEDING 45 DAYS (PROSPECTUS AND ALLOTMENTS OF SECURITIES) AMENDMENT RULES, 2025
The Central Govt. has directed all Companies receiving goods or services from micro and small enterprises to submit a half-yearly return to the MCA if payments exceed 45 days from the acceptance or deemed acceptance date. The return must include (a) the outstanding payment amounts and (b) the reasons for the delay.
B. GOVERNMENT REVISES INVESTMENT AND TURNOVER CRITERIA FOR CLASSIFYING ENTERPRISES AS MSMEs
The Central Government, under the Micro, Small and Medium Enterprises Development Act, 2006, has amended the notification S.O. 2119 (E) dated 26th June 2020, following the recommendations of the Advisory Committee. The amendments revise the investment and turnover limits for classifying enterprises as Micro, Small, and Medium Enterprises (MSMEs). Key changes include:
Micro Enterprises: The Investment limit increased from ₹1 crore to ₹2.5 crore, and the turnover limit from ₹5 crore to ₹10 crore.
Small Enterprises: The Investment limit was raised from ₹10 crore to ₹25 crore, and the turnover limit from ₹50 crore to ₹100 crore.
Medium Enterprises: The Investment limit was revised from ₹50 crore to ₹125 crore and the turnover limit from ₹250 crore to ₹500 crore.
These changes will come into effect from April 1, 2025.
IBBI MANDATES DETAILED DISCLOSURE OF CARRY FORWARD LOSSES IN INFORMATION MEMORANDUM
The Insolvency and Bankruptcy Board of India (IBBI) has instructed Insolvency Professionals to incorporate a dedicated section in the Information Memorandum (IM), explicitly outlining carry forward losses under the Income Tax Act, 1961. The disclosure must include the quantum of losses, a breakdown by specific heads, and the applicable time limits. This directive has been issued under Section 196 of the Insolvency and Bankruptcy Code (IBC), 2016.
A. SEBI AMENDS LODR REGULATIONS, 2015; INCREASES HVDLE THRESHOLD TO RS. 1,000 CRORE
The Securities and Exchange Board of India (SEBI) has revised the LODR Regulations, 2015, strengthening compliance requirements for High-Value Debt Listed Entities (HVDLEs). The threshold for HVDLE classification has been raised from ₹500 crore to ₹1,000 crore, with entities exceeding this limit required to comply within six months. Other key amendments cover the Board of Directors (BoD), Audit Committee, Nomination and Remuneration Committee, Related Party Transactions (RPTs), Secretarial Audit, and Secretarial Compliance Reports.
B. SEBI AMENDS PIT REGULATIONS, EXPANDS THE SCOPE OF UNPUBLISHED PRICE SENSITIVE INFORMATION (UPSI)
The Securities and Exchange Board of India (SEBI) has amended the Prohibition of Insider Trading (PIT) Regulations, 2015, broadening the definition of Unpublished Price Sensitive Information (UPSI). Key amendments include:
Addition of new UPSI events such as award or termination of contracts, rating changes, fundraising plans, forensic audits, and litigation outcomes.
Strengthened disclosure requirements related to fraud, defaults, insolvency proceedings, and regulatory actions.
Introduction of a 2-day deadline for recording non-internal information in structured digital databases.
Clarification that the trading window need not be closed for UPSI not originating within the listed company.
These regulations will come into effect 90 days from their publication in the Official Gazette.
DisclaimerInformation in this note is intended to provide only a general update of the subjects covered. It is not intended to be a substitute for detailed research or the exercise of professional judgment. KNM accepts no responsibility for loss arising from any action taken or not taken by anyone using this publication. Updates for the period 28.03.2025
Section 192 of the Income-Tax Act, 1961 – Deduction at source – Salary- Clarification on Income-Tax Deduction from Salaries during FY 2024-25.
Executive Summary on the comprehensive simplification of the Income-Tax Act, 1961.
New slabs in the proposed new regime introduced by Finance Bill, 2025
Goods And Service Tax (GST)
Circular no. 246/03/2025 – GST – Clarification on applicability of late fee for delay in furnishing of Form GSTR-9C, dated 30-01-2025
Circular F. no. 190341/12/2025, dated 31-01-2025- The Ministry of Civil Aviation (MOCA) has shared details about Gazette Notification No. 08/2024 – IGST (Rate), dated 08-10-2024, issued by the Department of Revenue.
Instruction no. 2/2025 – GST, dated 07-02-2025 – Section 128, along with Section 73 of the CGST Act, 2017, deals with waiving interest or penalties for certain tax demands and the procedure for department appeals related only to interest or penalties under Section 128A.
Circular no. 247/04/2025 – GST, dated 14-02-2025 – Section 9 of the CGST Act, 2017, Clarification covers GST levy and collection on GST rates and the classification (Goods) based on the GST Council’s 55th meeting on 21-12-2024.
Companies Act 2013/ Other Laws
Companies (Prospectus and Allotment of Securities) Amendment Rules, 2025
Relaxation in the timeline for reporting of differential rights issued by AIFs
A. SECTION 192 OF THE INCOME-TAX ACT, 1961 – DEDUCTION AT SOURCE – SALARY – CLARIFICATION ON INCOME-TAX DEDUCTION FROM SALARIES DURING FINANCIAL YEAR 2024-25 UNDER SECTION 192
Amendments made vide the Finance (No. 2) Act of 2024, Finance (No. 1) Act of 2024 and Finance Act of 2023 in respect of rates of deduction of income-tax from the payment of income under the head “Salaries” under section 102 of the Income-tax Act, 1961, during the financial year 2024-25
The term “Salary” has been defined in section 15 of the Act. As per the amendment in section 17(1) of the Act vide the finance Act, 2023. “salary”, inter alia, includes the following:
“The contribution made by the Central Government in the previous year, to the Agniveer Corpus Fund account of an individual enrolled in the Agnipath Scheme referred to in section 80CCH.”
As per the amendment vide the Finance Act, 2023 in section 17(2) of the Act, “perquisite”, inter alia, includes the following:
“(i) The value of rent-free accommodation provided to the employee by his employer
(ii) The value of any accommodation provided to the assessee by his employer at a concessional rate.”
B. Executive summary on the Comprehensive Simplifiaction of the Income-Tax Act,1961 The Income-tax Bill, 2025 has been tabled in Parliament on 13th February 2025, marking a significant step toward simplifying the language and structure of the Income-tax Act, 1961.The simplification exercise was guided by three core principles:
Textual and structural simplification for improved clarity and coherence.
No major tax policy changes to ensure continuity and certainty.
No modifications of tax rates, preserving predictability for taxpayers.
Quantitative Impact
The review has substantially reduced the Act’s volume, making it more streamlined and navigable. Key reductions are summarized below:
Item
Existing Income-tax Act, 1961
Proposed in the Income-tax Bill,2025
Change (Reduction/Addition)
Words
512,535
259,676
Reduction:252,859 words
Chapters
47
23
Reduction:24 chapters
Sections
819
576
Reduction:283 sections
Tables
18
57
Addition: 39 tables
Formulae
6
46
Addition: 40 formulae
C. New slabs in the proposed new regime introduced by Finance Bill, 2025
The new tax regime applies to a person, being an individual or Hindu undivided family or association of persons [other than a co-operative society], or body of individuals, whether incorporated or not, or an artificial juridical person referred to in sub-clause (vii) of clause (31) of section.
Any individual earlier was required to pay a tax of Rs 80,000 (in the new regime) for an income of Rs. 12 lacs. Now he will be required to pay nil tax on such income.
Sl .No.
Total Income (in lacs)
Rate of tax u/s 115BAC(1A)
1.
Upto 4,00,000
Nil
2.
4,00,001 to 8,00,000
5%
3.
8,00,001 to 12,00,000
10%
4.
12,00,001 to 16,00,000
15%
5.
16,00,001 to 20,00,000
20%
6.
20,00,001 to 24,00,000
25%
7.
Above 24,00,000
30%
A. Circular no. 246/03/2025 – GST – Clarification on applicability of late fee for delay in furnishing of Form GSTR-9C, dated 30-01-2025
Clarification has been issued regarding late fees for the delay in filing GSTR-9C:
Key Point: If a taxpayer is required to file both GSTR-9 (Annual Return) and GSTR-9C, the annual return is considered complete only when both forms are submitted.
Late Fee Applicability: If GSTR-9C is not submitted along with GSTR-9, the late fee under Section 47(2) of CGST Act applies from the due date until both forms are filed.
Waiver of Late Fee: A special waiver has been granted through Notification No. 08/2025, allowing taxpayers to submit pending GSTR-9C for FY 2022-23 and earlier by March 31, 2025, without additional late fees beyond what was due for GSTR-9.
No Refund: Any late fee already paid for delayed GSTR-9C submission will not be refunded.
Trade notices are to be issued for public awareness, and any difficulties should be reported to the Board.
B. Circular F. no. 190341/12/2025, dated 31-01-2025- The Ministry of Civil Aviation (MOCA) has shared details about Gazette Notification No. 08/2024 – IGST (Rate), dated 08-10-2024, issued by the Department of Revenue
Clarification on GST Exemption for Foreign Airlines’ Import of Services:
GST Exemption: As per the 54th GST Council meeting (09-09-2024), foreign airline establishments in India importing services from related persons abroad without consideration are exempt from GST, subject to these conditions:
GST is paid on passenger & goods transport services in India.
MoCA certifies that the establishment is a designated airline under a bilateral air service agreement.
MoCA certifies that Indian airlines receive reciprocal tax exemption in the foreign country
MoCA’s Role:
Provided a list of designated foreign airlines operating in India for Winter 2024-25 (Annexure I).
Consulted Air India, IndiGo, and Akasa Air on reciprocal tax exemptions (Annexure II).
Action: The MoCA’s Office Memorandum (O.M.) and annexures are available on the CBIC website for reference.
C. Instruction no. 2/2025 – GST, dated 07-02-2025 – Section 128, along with Section 73 of the CGST Act, 2017, deals with waiving interest or penalties for certain tax demands and the procedure for department appeals related only to interest or penalties under Section 128A
Clarification on Section 128A – Waiver of Interest & Penalty:
Provision: Section 128A of CGST Act (with Rule 164) allows waiver of interest/penalty for demands under Section 73 for FY 2017-18 to 2019-20, subject to conditions.
Clarification Sought: Whether benefits apply if:
Tax is fully paid, but the department appealed due to incorrect interest calculation.
Penalty is not imposed or is below the threshold.
Decision:
If full tax is paid and only interest/penalty is disputed, taxpayers are eligible for Section 128A benefits.
Appeals should be withdrawn or not filed if the only dispute is interest/penalty miscalculation.
Action: Proper officers should withdraw appeals or accept the order if under review.
D. Circular no. 247/04/2025 – GST, dated 14-02-2025 – Section 9 of the CGST Act, 2017, Clarification covers GST levy and collection on GST rates and the classification (Goods) based on the GST Council’s 55th meeting on 21-12-2024.
Key Clarifications from the 55th GST Council Meeting:
GST on Pepper (Genus Piper)
HS Code: 0904
Rate: 5% GST (S. No. 38, Notification 1/2017-CT)
Exemption: Agriculturists supplying dried pepper are not liable for GST under Section 23(1).
GST on Raisins by Agriculturists
Exemption: Raisins supplied by agriculturists are not liable for GST under Section 23(1).
Past Period up to 14-2-2025: Issue regularized on an “as-is where-is”
Implementation Issues: Report difficulties to the Board.
Companies (Prospectus and Allotment of Securities) Amendment Rules, 2025
The Ministry of Corporate Affairs (MCA) has issued the Companies (Prospectus and Allotment of Securities) Amendment Rules, 2025, under the Companies Act, 2013. This amendment modifies Rule 9B of the Companies (Prospectus and Allotment of Securities) Rules, 2014, granting a compliance extension for certain private companies.
Private companies (excluding Producer companies) that were not classified as small companies as of March 31, 2023, now have until June 30, 2025, to comply with the relevant sub-rule.
The Insolvency and Bankruptcy Board of India (IBBI) has issued the Voluntary Liquidation Process (Amendment) Regulations, 2025, effective January 28, 2025.
Key amendments include:
The Board is now mandated to maintain a Corporate Voluntary Liquidation Account with a scheduled bank.
New Regulation Introduces mandatory electronic filing of forms for different stages of liquidation, with specified timelines. Liquidators must ensure accurate and timely submissions, failing which a penalty of ₹500 per form per month will be imposed.
Liquidators are now mandated to file the final report, including Form H, with the Adjudicating Authority when a scheme of compromise or arrangement under Section 230 of the Companies Act, 2013, is approved.
These amendments aim to enhance transparency, accountability, and compliance within the Voluntary Liquidation Process.
IBBI Amends CIRP Regulations 2025
The Insolvency and Bankruptcy Board of India (IBBI) has introduced amendments to the Insolvency Resolution Process for Corporate Persons (CIRP) Regulations, effective February 3, 2025. These changes aim to streamline insolvency proceedings, particularly in the real estate sector.
Key Amendments:
Resolution professionals (RPs) can now transfer property possession to homebuyers during the resolution process.
Land authorities are now permitted to participate in Committee of Creditors (CoC) meetings.
RPs must submit a report on real estate development rights within 60 days to aid decision-making.
A monitoring committee may be formed to oversee resolution plan execution and submit quarterly progress reports to the Adjudicating Authority.
MSME Status Disclosure: Corporate debtors must now disclose their MSME registration status to facilitate participation from eligible resolution applicants.
These amendments aim to enhance efficiency, transparency, and stakeholder confidence in the insolvency resolution process.
SEBI (Mutual Funds) (Amendment) Regulations, 2025
The Securities and Exchange Board of India (SEBI) has introduced the Mutual Funds (Amendment) Regulations, 2025, bringing key changes to the Mutual Funds Regulations, 1996, effective April 1, 2025. The amendments require Asset Management Companies (AMCs) to invest a portion of their employees’ remuneration in mutual fund schemes based on their roles, as specified by SEBI. Additionally, AMCs must conduct stress tests on specific schemes and disclose the results in a prescribed format. The regulations also mandate that funds raised through New Fund Offers (NFOs) be deployed within a specified timeframe. Furthermore, AMCs must ensure that charges, commissions, or fees related to mutual fund distribution are paid in accordance with SEBI’s guidelines. These changes aim to enhance transparency, risk management, and accountability in the mutual fund industry.
Relaxation in the timeline for reporting of differential rights issued by AIFs
The Securities and Exchange Board of India (SEBI) has extended the deadline for Alternative Investment Funds (AIFs) to report differential rights issues to March 31, 2025. This extension, from the original February 28, 2025 deadline, comes after requests from the AIF industry for additional time to comply with the reporting requirements.
The extension aims to provide AIFs with additional time to ensure compliance with these regulatory guidelines, thereby promoting fair and equal treatment of investors.
DisclaimerInformation in this note is intended to provide only a general update of the subjects covered. It is not intended to be a substitute for detailed research or the exercise of professional judgment. KNM accepts no responsibility for loss arising from any action taken or not taken by anyone using this publication. Updates are for the period 28.02.2025
Income-Tax (First Amendment) Rules, 2025 – Insertion of New Rule 6GB
Income-Tax (Second Amendment) Rules, 2025 – Amendment in Rule 21AIA – Insertion of Rules 2DAA and 21ACA
Guidance for Application of the Principal Purpose Test under India’s Double Taxation Avoidance Agreement.
CBDT notifies Amendments in Income- Tax Rules,1962 to prescribe conditions for applicability of Presumptive Taxation regime for Non- Resident Cruise Ship Operators.
Section 197A, read with Section 194A of the Income-Tax Act,1961- No Deduction in certain cases.
Goods And Service Tax (GST)
Circular No. 240/34/2024 clarifies the availability of Input Tax Credit for electronic commerce operators when services specified under Section 9(5) of the CGST Act, 2017
Circular No. 241/35/2024 clarifies the availability of Input Tax Credit for goods delivered by the supplier at his place of business under an ex-works contract as per Section 16(2)(b) of the CGST Act, 2017.
Clarification on place of supply of online services supplied by the suppliers of services to unregistered recipients, Circular No. 242/36/2024 – GST [F. No. CBIC-20001/14/2024 – GST], dated 31-12-2024
Clarification on various issues pertaining to GST treatment of vouchers, Circular No. 243/37/2024 – GST [F. No. CBIC-20001/14/2024 – GST], dated 31-12-2024
Section 69, read with section 132 of the Central Goods and Services Tax Act, 2017 – power to arrest – guidelines for arrest and bail in relation to offences punishable amendment in instruction no. 2/2022-23 [GST- investigation], dated 17-08-2022
Section 9 of the Central Goods and Services Tax Act, 2017 – levy and collection of tax – CGST rate schedule for goods – amendment in notification no. 1/2017 – Central Tax (rate), dated 28-06-2017
Section 11 of the Central Goods and Services Tax Act, 2017 – power to grant exemption from tax – list of CGST exempt goods (nil rated goods) – amendment in notification no. 2/2017- Central Tax (rate), dated 28-06-2017
Section 9, read with sections 11, 15, and 16 of the CGST Act, 2017 – Amendment in CGST rate schedule for services in Notification No. 5/2025 – Central Tax, dated 16-01-2025.
The amendment to Notification No. 12/2017-Central Tax (Rate) revises certain exemptions for CGST exempt services, including changes to specific service categories and definitions.
The amendment to Notification No. 8/2018-Central Tax (Rate) exempts central tax on intra-state supplies of goods in excess of the specified margin of the supplier as per the updated schedule.
The amendment to Notification No. 11/2017-Central Tax (Rate) updates the CGST rate schedule for services, including changes to specified premises and new annexures for declarations.
The amendment to Notification No. 12/2017-Central Tax (Rate) revises certain exemptions for CGST exempt services, including changes to specific service categories and definitions.
Section 9 of the Central Goods and Services Tax Act, 2017 – The amendment to Notification No. 13/2017-Central Tax (Rate) updates the reverse charge mechanism on certain specified supplies of services under Section 9 of the CGST Act.
The amendment to Notification No. 17/2017-Central Tax (Rate) specifies that tax on intra-state supplies under notified categories of services shall be paid by the electronic commerce operator under Section 9 of the CGST Act.
Notification No. 1/2025-Central Excise (N.T.) appoints officers in notified jurisdictions to pass orders on excise and service tax appeals under Section 174 of the CGST Act, 2017.
Central Goods and Services Tax (amendment) rules, 2025 – amendment in rule 19 and 87, insertion of new rule 16a and substitution of Form reg-12, Notification No. 7/2025 – Central Tax, dated 23-01-2025
Notification No. 08/2025-Central Tax waives penalty for failure to file Form GSTR-9C along with Form GSTR-9 for financial years, if submitted by 31st March 2025.
CBIC cautions against fraudsters issuing fake and fraudulent summons for GST violations press release, dated 24-01-2025
Circular No. 244/01/2025 regularizes GST payment on co-insurance premium apportioned by lead insurers and on ceding/re-insurance commission deducted by insurers from reinsurance premiums.
Circular no. 245/02/2025 F. No. CBIC – 190354/2/2025 – to (tru-ii) – CBEC, clarifications regarding applicability of GST on certain services
Companies Act 2013/ Other Laws
Companies (Accounts) Second Amendments Rules,2024
IBBI amends guidelines for technical standards on core and other services under Information Utilities Regulations
Companies with turnover above Rs 250 crore must get onboard on ‘Trade Receivables Discounting Platforms by 31.03.2025
Prior Approval for Change in Control, transfer of Shareholdings among Immediate Relatives and Transmission of Shareholdings and their effect on Change in Control
SEBI updates Debenture Trustee’s due diligence certificate format for unsecured debt securities
Income – tax (First Amendment) Rules, 2025 – Insertion of New Rule 6GB
In exercise of the powers conferred by section 295, read with sub-section (1) of section 44BBC of the Income-tax Act, 1961, the Central Board of Direct Taxes hereby makes the following rules further to amend the Income-tax Rules, 1962, namely:
(1) These rules may be called the Income-tax (First Amendment) Rules, 2025.
(2) They shall come into force on the date of their publication in the Official Gazette.
In the Income-tax Rules, 1962, after rule 2DA, the following shall be inserted namely:-
“CCCB-Special provisions for computing profits and gains of business of operation of cruise ships in case of non-residents.”
Rule 6GB
Conditions for non-resident, engaged in the business of operation of cruise ships for section 44BBC–
For the purposes of section 44BBC, an assessee, being a non-resident, engaged in the business of operation of cruise ships shall, –
(i) operate a passenger ship having a carrying capacity of more than two hundred passengers or length of seventy-five meters or more, for leisure and recreational purposes and having appropriate dining and cabin facilities for passengers.
(ii) operate such ship on scheduled voyage or shore excursion touching at least two sea ports
of India or same seaports of India twice.
(iii) operate such ship primarily for carrying passengers and not for carrying cargo; and
(iv) operate such ship as per the procedure and guidelines if any, issued by the Ministry of Tourism or Ministry of Shipping.
Income – tax (Second Amendment) Rules, 2025 – Amendment in Rule 21AIA: Insertion of Rules 2DAA and 21ACA
In exercise of the powers conferred by section 295 of the Income-tax Act, 1961, the Central Board of Direct Taxes hereby makes the following rules further to amend the Income-tax Rules, 1962, namely:—
(1) These rules may be called the Income-tax (Second Amendment) Rules, 2025.
(2) They shall come into force on the date of their publication in the Official Gazette.
In the Income-tax Rules, 1962,
After rule 2DA, the following shall be inserted namely:-
“Conditions for the Venture Capital Fund for the clause (23FB) of section 10.–2DAA”
After rule 21AC, the following shall be inserted namely:-
“Conditions and activities for the Finance Company located in any International Financial Services Centre for section 94B.– 21ACA”
Guidance For Application of the Principal Purpose Test under India’s Double Taxation Avoidance Agreement
The Multilateral Convention to Implement Tax Treaty Related Provisions to Prevent Base Erosion and Profit Shifting (“MLI”) entered into force for India on 1st October, 2019. The MLI modifies some of India’s Double Taxation Avoidance Agreements (DTAAs). A key provision of the MLI is the Principal Purpose Test (PPT), which seeks to curb revenue leakage by preventing treaty abuse. While the PPT is included in most of India’s DTAAs through the MLI, it is part of some other DTAAs through bilateral processes.
The PPT envisages denial of benefits under a DTAA where it is reasonable to conclude, having considered all the relevant facts and circumstances that one of the principal purposes of an arrangement or transaction was to obtain a benefit, directly or indirectly, under a DTAA.
For DTAAs where the PPT has been incorporated through the MLI-from the date of entry into effect of the provisions of the MLI with respect to the DTAA specified in Article 35 of the MLI, as under:
With respect to taxes withheld at source on amounts paid or credited to non-residents, where the event giving rise to such taxes occurs on or after the first day of the previous year that begins on or after the latest of the dates on which the MLI enters into force for the Contracting Jurisdictions to the DTAA:
With respect to all other taxes levied by India for previous years beginning on or after the expiration of a period of six calendar months from the latest of the dates on which the MLI enters into force for the Contracting jurisdictions to the DTAA.
India has made certain treaty-specific bilateral commitments in the form of grandfathering provisions under the following DTAAs, as on date:
India-Cyprus DTAA.
India-Mauritius DTAA; and
India-Singapore DTAA
CBDT notifies Amendments in Income – Tax Rules,1962 to prescribe conditions for applicability of Presumptive Taxation Regime for Non – Resident Cruise Ship Operators
As a measure to promote investment and employment, Finance (No. 2) Act, 2024 inter-alia provided a presumptive taxation regime for non-residents, engaged in the business of operation of cruise ships. Further, exemption has been provided for any income of a foreign company from lease rentals of cruise ships, received from a related company which operates such ship or ships in India. The applicability of this presumptive taxation regime is subject to the conditions, as prescribed.
The conditions which have been prescribed for non-resident, engaged in the business of operation of cruise ships provide that such non-resident shall: —
Operate a passenger ship having a carrying capacity of more than 200 passengers or length of 75 meters or more, for leisure and recreational purposes and having appropriate dining and cabin facilities for passengers.
Operate such ship on scheduled voyage or shore excursion touching at least two sea ports of India or same sea ports of India twice;
Operate such ship primarily for carrying passengers and not for carrying cargo; and
Operate such ship as per the procedure and guidelines if any, issued by the Ministry of Tourism or Ministry of Shipping.
Section 197A, read with Section 194Q of the Income – Tax Act,1961- No Deduction in certain cases
In exercise of the powers conferred by sub-section (1F) of Section 197A of the Income-tax Act, 1961, the Central Government hereby specifies that no deduction of tax shall be made under the provisions of section 194Q of the said Act by a person, being a buyer, in respect of purchase of goods from a Unit of International Financial Services Centre, being a seller, subject to the following conditions, namely:—
The seller shall-
Furnish a statement -cum-declaration in the format provided to the buyer giving details of previous years relevant to the ten consecutive assessment years for which the seller opts for claiming deduction under subsections (1A) and (2) of section 80LA of the said Act; and
Such statement-cum-declaration so furnished shall be verified in the manner specified in the said Form, for each previous year relevant to the ten consecutive assessment years for which the seller opts for claiming deduction under sub-sections (1A) and (2) of section 80LA of the said Act;
The buyer shall-
Not deduct tax on payment made or credited to the seller after the date of receipt of copy of the statement- cum-declaration in the said Form from the seller; and
Furnish the particulars of all the payments made to the seller on which tax has not been deducted in pursuance of this notification in the statement of deduction of tax referred to in sub-section (3) of section 200 of the said Act read with rule 31A of the Income-tax Rules, 1962.
This notification shall come into force on 1st day of January, 2025.
Circular no. 240/34/2024 – GST [F. No. CBIC-20001/14/2024 – GST], dated 31-12-2024, clarifies the availability of Input Tax Credit for electronic commerce operators
The clarification confirms that electronic commerce operators (ECOs) do not need to reverse ITC for services under Section 9(5) (except for tax payments under this section, which must be in cash). ITC can still be used for the ECO’s own tax liabilities, ensuring uniform application of ITC rules.
Circular No. 241/35/2024 – GST clarification on availability of Input Tax Credit as per clause (b) of sub-section (2) of section 16 of the Central Goods and Services Tax Act, 2017
The clarification confirms that ITC is available for goods under Ex-Works (EXW) contracts when handed over to a transporter on the buyer’s behalf, as this qualifies as “receipt” under Section 16(2)(b) of the CGST Act. The same principle applies to all EXW contracts, provided goods are used for business purposes.
Clarification on place of supply of online services supplied by the suppliers of services to unregistered recipients, Circular No. 242/36/2024 – GST, dated 31-12-2024
Suppliers of online services must mention the unregistered recipient’s State on invoices to ensure correct place of supply under GST. Failure to do so may lead to revenue misallocation and penalties. Compliance measures, including system updates and enforcement, are required for uniform implementation.
Clarification on various issues pertaining to GST treatment of vouchers, Circular No. 243/37/2024 – GST [F. No. CBIC-20001/14/2024 – GST], dated 31-12-2024
Vouchers are not taxable under GST if recognized by RBI as “money” or classified as “actionable claims” (excluding betting, gambling, etc.). Trading vouchers in a P2P model is not taxable, but commission-based distribution is taxable.
Additional services related to vouchers are taxable, while unredeemed vouchers (breakage) do not attract GST.
Section 69, read with section 132 of the Central Goods and Services Tax Act, 2017 – power to arrest – guidelines for arrest and bail in relation to offences punishable under-said act – amendment in instruction no. 2/2022-23
Regarding this the Delhi High Court ruled that the grounds for arrest must be communicated in writing to the arrested person, to mandate written explanation and acknowledgment at the time of the Arrest Memo.
Section 9 of the Central Goods and Services Tax Act, 2017 – levy and collection of tax – CGST rate schedule for goods – amendment in notification no. 1/2017 – Central Tax (rate), dated 28-06-2017
The Central Government has amended the CGST Act (2017) to include Fortified Rice Kernel (FRK) under specific tax schedules and revised the definition of “pre-packaged and labelled” for retail sale up to 25 kg/liters, effective immediately.
Section 11 of the Central Goods and Services Tax Act, 2017 – power to grant exemption from tax – list of CGST exempt goods (nil rated goods) – amendment in notification no. 2/2017- Central Tax (rate), dated 28-06-2017
The CGST Act (2017) is amended to include Gene Therapy and update the definition of “pre-packaged and labelled” goods, effective immediately.
Section 9 of the Central Goods and Services Tax Act, 2017 -Notification No. 3/2025 – Central Tax (rate) [G.S.R. 56(e)F. No. 190354/2/2025 – tru, dated 16-01-2025
The CGST Act (2017) is amended to include “food inputs” under government programs for weaker sections, with a 2.5% tax rate, effective immediately.
Section 11, read with section 9 of the Central Goods and Services Tax Act, 2017 – power to grant exemption from tax – exemption of central tax on intra-state supplies of goods from so much tax as specified in schedule iv of notification no.1/2017 – dated 16-01-2025
The CGST Act (2017) is amended to increase the tax rate under S. No. 4 of Notification No. 8/2018 from 6% to 9%, effective immediately.
Section 9, read with sections 11, 15, and 16 of the CGST Act, 2017 – Amendment in CGST rate schedule for services in Notification No. 5/2025 – Central Tax, dated 16-01-2025.
The CGST Act (2017) is amended to update the definition of “specified premises”for hotel accommodation services, with new annexures for opt-in and opt-out declarations, effective from 1st April 2025.
Section 11 of the CGST Act, 2017 – Amendment in Notification No. 12/2017, Central Tax (rate), regarding CGST exempt services, in Notification No. 6/2025, dated 16-01-2025.
The CGST Act (2017) is amended to update exemptions for certain services, including transmission and distribution, motor vehicle accident fund services, and training partners approved by the National Skill Development Corporation, effective from 1st April 2025.
Notification No. 7/2025 – Central Tax (rate) dated 16-01-2025, Section 9 of the Central Goods and Services Tax Act, 2017 – levy and collection of tax – reverse charge on certain specified supplies of services – amendment in notification no. 13/2017 – Central Tax (rate), dated 28-06-2017Notification No. 7/2025 – Central Tax (rate) dated 16-01-2025
Section 9 of the Central Goods and Services Tax Act, 2017 – levy and collection of tax – notified categories of services, tax on intra-state supplies shall be paid by electronic commerce operator
The Central Government has amended Notification No. 17/2017-Central Tax (Rate) to substitute the definition of “specified premises” to align with clause (xxxvi) of paragraph 4 of Notification No. 11/2017-Central Tax (Rate). This amendment takes effect from April 1, 2025.
Notification No. 1/2025-Central Excise (N.T.) appoints officers in notified jurisdictions to pass orders on excise and service tax appeals under Section 174 of the CGST Act, 2017-The Central Board of Indirect Taxes and Customs has appointed Central Excise Officers with jurisdiction to pass orders on appeals filed after July 1, 2017, under the Central Excise Act and the Finance Act.
Central Goods and Services Tax rules, 2025 – Notification No. 7/2025 – Central Tax [F. No. CBIC-20001/15/2024 – GST], dated 23-01-2025
The CGST Rules, 2017, are amended to introduce temporary identification numbers for non-registered persons making payments, allow composition taxpayers to use FORM GST CMP-02 for intimation, and update the common portal and FORM GST REG-12 accordingly.
Section 128, read with sections 44 and 47 of the Central Goods and Services Tax Act, 2017 – A late fee waiver is granted for delayed FORM GSTR-9 filings for FY 2017-18 to 2022-23, provided FORM GSTR-9C is filed by March 31, 2025, but no refund is given for late fees already paid.
CBIC cautions against fraudsters issuing fake and fraudulent summons for GST violations press release, dated 24-01-2025-Taxpayers can verify the authenticity of CBIC communications, including summons, using the ‘VERIFY CBIC-DIN’ tool, and report fake summons for law enforcement action.
Circular no. 244/01/2025 – GST F. No. CBIC – 190354/2/2025- The 53rd GST Council meeting recommended including certain insurance-related activities in Schedule III of the CGST Act, with GST payments regularized for the period 07.2017 to 31.10.2024, effective from 01.11.2024.
Circular no. 245/02/2025 F. No. CBIC – 190354/2/2025 – to (tru-ii) – CBEC, clarifications regarding applicability of GST on certain services-The 55th GST Council meeting clarified various GST matters, including exemptions and regularizations for penal charges, payment aggregators, R&D services, skilling services, facility management, and electricity utilities, ensuring better compliance with GST laws.
Companies (Accounts) Second Amendment Rules, 2024
The amendments to the Rules extend the deadline for filing the Corporate Social Responsibility (“CSR”) report under Form CSR-2 for the financial year 2023-2024. Initially, the deadline for filing Form No. CSR-2 for the financial year 2023-2024 under the Rules was set for December 31, 2024. However, the amendment now extends the deadline and allows companies to submit their CSR reports under Form No. CSR-2 on or before March 31, 2025, after filing of Form No. AOC-4 or AOC-4 NBFC (Ind-AS) or AOC-4 XBRL, as the case may be.
IBC
IBBI amends guidelines for technical standards on core and other services under the Information Utilities Regulations
IBBI has notified amendments to the guidelines for technical standards for the performance of core services and other services under the IBBI (information utilities) regulations, 2017. The amendments include the use ofa Permanent Account Number (PAN) or other OVDs for user identity verification during registration. Additionally, IUs are required to use UIDAI’s demographic authentication facility for verifying user identities.
Other Laws
Companies with turnover above Rs. 250 crore must get onboarded on ‘Trade Receivables Discounting Platforms’ by 31.03.2025
In line with section 9 of the MSME Development Act, 2006, the Central Government has mandated that all companies registered under the Companies Act, 2013, with a turnover of more than Rs. 250 crores and all Central Public Sector Enterprises (CPSEs) be onboarded on the Trade Receivables Discounting System (TReDS) platforms as notified by the RBI. The onboarding process for these entities must be completed by March 31, 2025.
Prior Approval for Change in Control, Transfer of Shareholdings among Immediate Relatives, and Transmission of Shareholdings and their effect on Change in Control
The Securities and Exchange Board of India has issued a circular on prior approval for change in control, transfer of shareholdings among immediate relatives, and transmission of shareholdings and their effect on change in control which includes the following:
Transfer /transmission of shareholding in case of unlisted body corporate intermediary
Transfer /transmission of shareholding in case of a proprietary firm-type intermediary
Transfer /transmission of ownership interest in case of partnership firm-type intermediary
The provisions of this circular shall be applicable with immediate effect.(27.12.2024)
SEBI updates Debenture Trustee’s due diligence certificate format for unsecured debt securities
SEBI has revised the due diligence certificate format for Debenture Trustees (DTs) in unsecured debt securities under Non-Convertible Securities Regulations. Issuers must submit a due diligence certificate obtained from the Debenture Trustee during draft offer document filing and listing application, in the revised format. This circular shall be applicable with immediate effect.(29.01.2025)
Disclaimer: Information in this note is intended to provide only a general update of the subjects covered. It is not intended to be a substitute for detailed research or the exercise of professional judgment. KNM accepts no responsibility for loss arising from any action taken or not taken by anyone using this publication. Updates are for the period 31.01.2025.
Section 194N of Income Tax Act,1961- Payment of Certain amounts in cash- Approved Foreign Representations to whom provision of said section shall not apply.
Income Tax (Tenth Amendments) Rules, 2024- Insertion of Rules 10TI, 10TIA, 10TIB & 10TIC and Insertion of Form no. 3CEFC.
CBDT Launches Electronic Campaign to address Income and transaction mismatches for FY 2023-24 and FY 2021-22.
Goods And Service Tax (GST)
Notification No. 27/2024 – Central Tax [ (G.S.R. 729(E)) F. NO. CBIC-20016/2/2022-GST], Dated 25-11-2024, Officers under this act- Powers of officers – appointment of officers- Amendment in notification no. 2/2017 – Central Tax, Dated 19-6-2017
Notification No. S.O. 5063(E) [F. NO. A-50050/99/2024-GSTAT-DOR], Dated 26-11-2024[As amended by notification no. S.O. 5128(E) [F.NO. A-50050/99/2024-GSTAT-DOR], Dated 29-11-2024], appellate tribunal and benches thereof- constitution of-constitution of principal and state benches of Goods and Services Tax appellate services Tax appellate tribunal
Notification No. 28/2024- Central Tax [S.O. 5091(E)/F. NO. CBIC-20010/22/2024-GST], Dated 27-11-2024, Read with section 3 of the integrated Goods and Services Tax Act, 2017- Officers- Powers of- Appointment of officers to pass decision or orders in respect of notices issued to specified notices by officers of Directorate General Intelligence
Notification No. 29/2024 – Central Tax [G.S.R.735(E)/F. NO. CBIC-20001/9/2024-GST], Dated 27-11-2024, furnishing of returns – extension of due date to furnish return in Form GSTR-3B for month of October, 2024, for registered persons having Principal place of business in specified state
Notification No. S.O. 5128(E) [F. NO. A-50050/99/2024-GSTAT-DOR], Dated 29-11-2024, Appellate tribunal and benches thereof- Constitution of – Constitution of Principal and State benches of Goods and Services Tax Appellate Tribunal- Corrigendum to notification no. S.O. 5063(E), Dated 26-11-2024
Circular No. 239/33/2024 – GST [F. NO. CBIC-20016/2/2022-GST], Dated 4-12-2024, officers under this Act- notified proper officer under Sections 73 and 74 – Amendment in circular No. 31/05/2018-GST, Dated 9-2-2018
Notification No. 30/2024 – Central Tax [F. NO. CBIC-20001/10/2024-GST], Dated 10-12-2024, section 39 of the Central Goods and Services Tax Act, 2017 – Furnishing of returns – Extension of due date to furnish Form GSTR-3B for month of October, 2024, for registered persons having principal place of business at notified place
Notification No. 31/2024 – Central Tax [S.O. 5392(E)/F. NO. CBIC-20010/27/2024-GST], Dated 13-12-2024, officers – Powers of – appointment of officers to pass decision or orders in respect of notices issued to specified notices by officers of Directorate General of GST Intelligence
Companies Act 2013/ Other Laws
Caution to Public
Extension of Time for Filing Forms to Monitor Liquidation and Voluntary Liquidation Processes under the Insolvency and Bankruptcy Code, 2016, and the Regulations made thereunder
Securities and Exchange Board of India (Prohibition of Insider Trading) Regulations, 2015
Companies with turnover above Rs 250 crore must get onboard on ‘Trade Receivables Discounting Platforms’ by 31.03.2025
Section 194N of Income Tax Act, 1961-Payment of certain amounts in Cash- Approved Foreign Representatives to whom Provision of said section shall not apply
·In exercise of the powers conferred by the fifth proviso to section 194N of the Income-tax Act, 1961, the Central Government after consultation with the Reserve Bank of India, hereby specifies that the provisions of section 194N of the said Act shall not apply to Foreign Representations duly approved by the Ministry of External Affairs of the Government of India including Diplomatic Missions, agencies of the United Nations, International Organisations, Consulates and Offices of Honorary Consuls which are exempt from paying taxes in India as per the Diplomatic Relations (Vienna Convention) Act 1972 (43 of 1972) and the United Nations (Privileges and Immunities) Act 1947 (46 of 1947).
This notification shall come into effect from 1st day of December 2024.
Income-Tax (Tenth Amendment) Rules,2024- Insertion of Rules 10TI, 10TIA, 10TIB & 10TIC and Insertion of Form no. 3CEFC
In exercise of the powers conferred by section 295, read with sub-section (2) of section 92CB of the Income-tax Act, 1961, the Central Board of Direct Taxes hereby makes the following rules further to amend the Income-tax Rules, 1962, namely: —
Safe Harbour-10TIA
The income-tax authorities shall accept the option for safe harbour exercised by an eligible assessee in any relevant previous year under rule 10TIB, where the income declared by such assessee from an eligible business is in accordance with the circumstances as specified in sub-rule (2), unless such safe harbour is declared invalid under the provisions of sub-rule (3) of rule 10TIB.
The circumstances referred to in sub-rule (1) in respect of the eligible business mentioned in column (1) of the Table below shall be as specified in column (2) thereof, namely:-
Eligible Business
Circumstances
Selling of raw diamonds referred to in clause (b) of rule 10TI
The profits and gains of the eligible business chargeable to tax under the head “Profits and gains of business or profession” shall be 4 per cent. or more of the gross receipts from such business.
Where the eligible assessee has expired the option for safe harbour under rule 10TIB in respect of the eligible business in any relevant previous year and such option is not declared invalid under the said rule, —
Any deduction allowable under the provisions of sections 30 to 38 shall be deemed to have been already given full effect to and no further deduction under those sections shall be allowed;
the written down value of any asset of such business shall be deemed to have been calculated as if the eligible assessee had claimed and had been actually allowed the deduction in respect of the depreciation for such previous year;
no set off of unabsorbed depreciation under sub-section (2) of section 32 or carried forward loss under sub-section (1) of section 72 shall be allowed to such assessee; and
no set off loss from other business under sub-section (1) of section 70 or other head under subsection (1) or sub-section (2) of section 71 shall be allowed to such assessee for income chargeable to tax under the head “Profits and gains of business or profession” in respect of such business.
For the purposes of exercising option for safe harbour, the assessee shall furnish Form No. 3CEFC, complete in all respects, to the Assessing Officer before furnishing the return of income under section 139 for the relevant previous year.
The Assessing Officer may declare the option for safe harbour as invalid by an order in writing , where the assessee has-
Availed the safe harbour by furnishing incorrect facts; or
Concealed facts related to his business.
CBDT Launches Electronic Campaign to address Income and Transaction Mismatches for FY 2023-24 and FY 2021-22
The Central Board of Direct Taxes (CBDT) has launched an electronic campaign to assist taxpayers in resolving mismatches between the income and transactions reported in the Annual Information Statement (AIS) and those disclosed in Income Tax Returns (ITRs) for the financial years 2023-24 and 2021-22. This campaign also targets individuals who have taxable income or significant high-value transactions reported in their AIS but have not filed ITRs for the respective years. The initiative is part of the implementation of the e-Verification Scheme, 2021.
As part of this campaign, informational messages have been sent via SMS and e-mail to taxpayers and non-filers where mismatches have been identified between transactions reported in AIS and the ITRs filed. The purpose of these messages is to remind and guide individuals who may not have fully disclosed their income in their ITRs to take this opportunity to file revised or belated ITRs for FY 2023-24. The last date to file these revised or belated ITRs is December 31, 2024.
For cases pertaining to FY 2021-22, taxpayers can file updated ITRs by the limitation date of March 31, 2025.
Taxpayers can also provide their feedback, including disagreeing with the information reported in the AIS, through the AIS portal accessible via the e-filing website (https://www.incometax.gov.in/iec/foportal/).
This initiative reflects the Income Tax Department’s commitment to leveraging technology to simplify compliance and ensure transparency. By utilizing third-party data, the department aims to create a more efficient, taxpayer-friendly system that aligns with the vision of Viksit Bharat.
The CBDT encourages all eligible taxpayers to take advantage of this opportunity to fulfil their tax responsibilities and contribute to the nation’s economic development. This effort not only supports the government’s vision for a developed India but also promotes a culture of transparency, accountability, and voluntary compliance.
Notification No. 27/2024 – Central Tax [ (G.S.R. 729(E)) F. NO. CBIC-20016/2/2022-GST], Dated 25-11-2024, Officers under this act – Powers of officers – appointment of officers – Amendment in notification no. 2/2017 – Central Tax, Dated 19-6-2017
The Central Government has amended Notification No. 02/2017-Central Tax, dated 19th June 2017, under the powers of Sections 3 and 5 of the CGST Act, 2017, and Section 3 of the IGST Act, 2017.
Key Updates:
Revised Table V:
The updated table specifies the powers of Additional Commissioners or Joint Commissioners of Central Tax to pass orders or decisions on notices issued by officers of the Directorate General of Goods and Services Tax Intelligence (DGGI) under sections 67, 73, 74, 76, 122, 125, 127, 129, and 130 of the CGST Act, 2017.
Jurisdiction:
The table lists 23 Commissioners and Principal Commissioners from various locations across India, including Ahmedabad South, Bengaluru East, Delhi North, Chennai South, Kolkata North, and others, who can exercise these powers.
Effective Date:
This notification comes into effect on 1st December 2024.
Notification No. S.O. 5063(E) [F. NO. A-50050/99/2024-GSTAT-DOR], Dated 26-11-2024[As amended by notification no. S.O. 5128(E) [F.NO. A-50050/99/2024-GSTAT-DOR], Dated 29-11-2024], appellate tribunal and benches thereof- constitution of-constitution of principal and state benches of Goods and Services Tax appellate services Tax appellate tribunal
The Central Government, under the powers granted by sub-sections (1), (3), and (4) of section 109 of the Central Goods and Services Tax Act, 2017 (12 of 2017), and based on the recommendation of the GST Council, makes the following amendments to its notification dated 31st July 2024 (S.O. 3048(E)):
in clause (iii), in the Table of the said notification: –
For Serial Number 25: In Column (4), replace “Varanasi” with “Prayagraj. “In Column (5), replace “Prayagraj” with “Varanasi.”
For Serial Number 19: In Column (4), replace “Jalandhar” with “Chandigarh. “In Column (5), replace “Chandigarh” with “Jalandhar.”
Addition of New Clause:
A new clause (iv) is added to specify the districts under the jurisdiction of the State Benches of the GST Appellate Tribunal. The locations of the benches (Column 3), their jurisdictions (Column 4), and their sittings or circuits (Column 6) will take effect from the date of publication of this notification in the Gazette of India.
High Court Jurisdictions in India
Sno.
State Name
Locations
Jurisdiction
1.
Andhra Pradesh
Vijayawada, Visakhapatnam
Covers all districts in Andhra Pradesh
2.
Bihar
Patna
All districts in Bihar
3.
Chhattisgarh
Raipur
All districts in Chhattisgarh
4.
Delhi
Delhi
All districts in the Union Territory of Delhi
5.
Gujarat and DNHDD (Dadra & Nagar Haveli and Daman & Diu)
Ahmedabad, Surat, Rajkot
All districts in Gujarat and the Union Territory of DNHDD
Notification No. 28/2024- Central Tax [S.O. 5091(E)/F. NO. CBIC-20010/22/2024-GST], Dated 27-11-2024, Read with section 3 of the integrated Goods and Services Tax Act, 2017- Officers- Powers of- Appointment of officers to pass decision or orders in respect of notices issued to specified notices by officers of Directorate General Intelligence
Under the powers granted by Section 5 of the Central Goods and Services Tax Act, 2017, and Section 3 of the Integrated Goods and Services Tax Act, 2017, the Central Board of Indirect Taxes and Customs designates the officers Joint Commissioner or Additional Commissioner, CGST and Central Excise Thane Commissionerate. These officers are authorized to pass orders or decisions on notices issued to the individuals or entities by the Directorate General of Goods and Services Tax Intelligence under Sections 73, 74, 122, 125, and 127 of the Central Goods and Services Tax Act, 2017.
Notification No. 29/2024 – Central Tax [G.S.R.735(E)/F. NO. CBIC-20001/9/2024-GST], Dated 27-11-2024, furnishing of returns – extension of due date to furnish return in Form GSTR-3B for month of October, 2024, for registered persons having Principal place of business in specified state
The Commissioner, based on the recommendations of the GST Council, has extended the deadline for filing the GSTR-3B return for October 2024.
New Deadline: November 30, 2024.
Who is affected: Registered taxpayers whose primary business location is in Manipur and are required to file returns under Section 39(1) of the CGST Act, 2017, and Rule 61(1)(i) of the CGST Rules, 2017.
This notification is effective retrospectively from November 20, 2024.
Notification No. S.O. 5128(E) [F. NO. A-50050/99/2024-GSTAT-DOR], Dated 29-11-2024, Appellate tribunal and benches thereof- Constitution of – Constitution of Principal and State benches of Goods and Services Tax Appellate Tribunal- Corrigendum to notification no. S.O. 5063(E), Dated 26-11-2024
The Ministry of Finance (Department of Revenue) has issued a correction to its notification published in the Gazette of India on November 26, 2024 (S.O. 5063(E)):
In Serial No. 21, Column (1), for the Jaipur Bench (Column 3), under Sr. 1, Column (4), the word “Alwar” is replaced with “Ajmer.”
Circular No. 239/33/2024 – GST [F. NO. CBIC-20016/2/2022-GST], Dated 4-12-2024, officers under this Act- notified proper officer under Sections 73 and 74 – Amendment in circular No. 31/05/2018-GST, Dated 9-2-2018
Empowerment of Additional/Joint Commissioners:
Notification No. 2/2022-Central Tax (11th March 2022) added para 3A to empower Additional/Joint Commissioners in certain Central Tax Commissionerate’s with All India jurisdiction to adjudicate show-cause notices from the Directorate General of Goods and Services Tax Intelligence (DGGI).
Further, Notification No. 27/2024-Central Tax (25th November 2024) expanded this empowerment to more Additional/Joint Commissioners, effective from 1st December 2024.
Update to Circular No. 31/05/2018-GST:
Para 7.1 of the circular is amended for adjudication of DGGI show-cause notices when:
Notices are issued to multiple entities (same or different PANs), or
Multiple notices are issued to entities with the same PAN.
If these entities are under different Central Tax jurisdictions, adjudication can be done by any empowered Additional/Joint Commissioner with All India jurisdiction.
Adjudication is based on the highest demand of tax in the notice. If the principal place of business with the highest demand is in a specific jurisdiction, the case will be handled by the corresponding Additional/Joint Commissioner.
Notification No. 30/2024 – Central Tax [F. NO. CBIC-20001/10/2024-GST], Dated 10-12-2024, section 39 of the Central Goods and Services Tax Act, 2017 – Furnishing of returns – Extension of due date to furnish Form GSTR-3B for month of October, 2024, for registered persons having principal place of business at notified place
The due date for filing the GSTR-3B return for October 2024 is extended to 11th December 2024 for registered persons whose principal place of business is in Murshidabad, West Bengal. This applies to those required to file under section 39(1) of the Central GST Act.
This extension is effective from 20th November 2024.
Notification No. 31/2024 – Central Tax [S.O. 5392(E)/F. NO. CBIC-20010/27/2024-GST], Dated 13-12-2024, officers – Powers of – appointment of officers to pass decision or orders in respect of notices issued to specified notices by officers of Directorate General of GST Intelligence
The Central Board of Indirect Taxes and Customs has appointed officers like Additional/Joint Commissioner, CGST, Chandigarh to make decisions or pass orders regarding notices by Joint Director, DGGI, Hqrs issued to the notices listed by the Directorate General of Goods and Services Tax Intelligence under sections 73, 74, 122, 125, and 127 of the Central Goods and Services Tax Act, 2017.
Caution To Public
The Securities and Exchange Board of India (SEBI) has issued a caution to the public regarding unregistered online platforms offering unlisted debt securities. These platforms lack regulatory oversight and basic investor protection. SEBI warns that these activities violate the Companies Act, 2013, SEBI Act, 1992, Prohibition of Fraudulent and Unfair Trade Practices relating to Securities Market Regulations, 2003, and SEBI (Issue and Listing of Non-Convertible Securities) Regulations, 2021. The public is advised to exercise caution when undertaking transactions on such platforms. SEBI has issued an interim order against some entities operating such platforms. Investors are advised to use online bond platforms operated by SEBI-registered stock brokers authorized by the Bombay Stock Exchange and/or the National Stock Exchange.
IBC
Extension of Time for Filing Forms to Monitor Liquidation and Voluntary Liquidation Processes under the Insolvency and Bankruptcy Code, 2016, and the Regulations made thereunder
The Insolvency and Bankruptcy Board of India has issued circular on Extension of time for filing forms to monitor liquidation and voluntary liquidation processes under the Insolvency and Bankruptcy Code, 2016, and the Regulations made thereunder. Last date of submission of the forms relating to the liquidation process is latest by December 30, 2024.
Other Laws
Companies with turnover above Rs. 250 crore must get onboarded on ‘Trade Receivables Discounting Platforms’ by 31.03.2025
In line with section 9 of the MSME Development Act, 2006, the Central Government has mandated that all companies registered under the Companies Act, 2013, with a turnover of more than Rs. 250 crores and all Central Public Sector Enterprises (CPSEs) be onboarded on the Trade Receivables Discounting System (TReDS) platforms as notified by the RBI. The onboarding process for these entities must be completed by March 31, 2025.
Securities and Exchange Board of India (Prohibition of Insider Trading) Regulations, 2015
The Securities and Exchange Board of India has notified amendment under Securities and Exchange Board of India (Prohibition of Insider Trading) Regulations, 2015 wherein:
Regulation 2, sub-regulation (1), in clause (d), sub-clause (i) shall be read as follows:
any person who is or has been, during the six months prior to the concerned act, associated with a company, in any capacity, directly or indirectly, including by reason of frequent communication with its officers or by being in any contractual, fiduciary or employment relationship or by being a director, officer or an employee of the company or holds any position including a professional or business relationship, whether temporary or permanent, with the company, that allows such a person, directly or indirectly, access to unpublished price sensitive information or is reasonably expected to allow such access, etc.
They shall come into force on the date of their publication in the Official Gazette.
Disclaimer: Information in this note is intended to provide only a general update of the subjects covered. It is not intended to be a substitute for detailed research or the exercise of professional judgment. KNM accepts no responsibility for loss arising from any action taken or not taken by anyone using this publication. Updates are for the period 30.11.2024.
Specifying Forms prescribed in Appendix-II of The Income Tax Rules, 1962 to be furnished electronically under Sub-Rule (1) and Sub-Rule (2) of Rule 131 of the Income Tax Rules,1962.
Specifying Forms prescribed in Appendix-II of The Income Tax Rules, 1962 to be furnished electronically under Sub-Rule (1) and Sub-Rule (2) of Rule 133 of the Income Tax Rules,1962.
Section 119, Read with Section 220 of The Income Tax Act, 1961- CBDT- fixing monetary limit of Income Tax Authorities in respect of reduction or waiver of interest paid or payable u/s 220(2)
Section 119 of The Income Tax Act, 1961- CBDT- Condonation of delay u/s 119(2)(b) in filing of Form no. 10-IC and Form no. 10-ID for A.Y. 2020-21, 2021-22 and 2022-23.
Goods And Service Tax (GST)
Circular No. 237/31/2024-GST [F.NO. CBIC-20001/6/2024-GST] Clarifying the issues regarding implementation of provisions of Sub- Section (5) and Sub-Section (6) in section 16 OF CGST ACT, 2017
Circular No. 238/32/2024-GST [F. NO. CBIC-20001/6/2024-GST] Clarification of various doubts related to Section 128A OF THE CGST ACT, 2017
Notification No. G.S.R. 644(E) [NO. 109 (F. NO. A-50050/2/20… Goods and Services Tax Council Secretariat, Group ‘A’ Executive posts recruitment (Amendment) Rules, 2024 – Amendment in Rule 7 and Schedule
Corrigendum G.S.R. 652(E) [F. NO. 190354/149/2024-TO (TRU-II)-PART-I CBEC], Dated 22-10-2024, Section 9 of the Central Goods and Services Tax Act, 2017
Corrigendum to Circular No. 237/31/2024-GST [F.NO. CBIC-20001/6/2024- GST, dated 25-10-2024, Clarifying the issues regarding implementation of provisions of Sub- Section (5) and Sub-Section (6) in section 16 of CGST ACT, 2017
Notification No. 26/2024–CENTRAL TAX [G.S.R. 713(E)/F. NO CBIC-20001/8/2024-GST], Dated 18-11-2024, Section 39 of the Central Goods and Services Tax Act, 2017-Furnishing of Returns- Extension of due date to furnish form GSTR-3B for month of October 2024, for registered person having specified principal place of business.
Companies Act 2013/ Other Laws
Filing of Financial Statements of Producer Companies within 60 days of Annual General Meeting
Reporting of Foreign Exchange Transactions to Trade Repository
Operational Framework for Reclassification of Foreign Portfolio Investment to Foreign Direct Investment (FDI)
Onboarding Process on the Trade Receivables Discounting System
SEBI (Bankers to an Issue) (Amendment) Regulations, 2024.
· Specifying Forms Prescribed In Appendix-Ii Of The Income Tax Rules, 1962, To Be Furnished Electronically Under Sub Rule (1) And Sub- Rule (2) Of Rule 131 Of The Income Tax Rules, 1962
a) In exercise of the powers conferred under sub-rule (1) and sub-rule (2) of Rule 131 of the Income-tax Rules, 1962 (‘the Rules’), the Director General of Income Tax (Systems), Bengaluru with the approval of the Board, hereby specifies that the following Forms shall be furnished electronically and shall be verified in the manner prescribed under sub-rule (1) of Rule 131:
Form
Description
Form 3CEDA
Application for the rollback of an Advance Pricing Agreement
Form 3 CO
Application form for approval under sub-section (1) of section 35CCC of the Income Tax Act, 1961
This notification shall come into effect from 31st October 2024.
Specifying Forms Prescribed In Appendix-Ii Of The Income Tax Rules ,1962 To Be Fuurnished Elecctronically Under Sub-Rule (1) And Sub-Rule (2) Of Rule 133
In exercise of the powers conferred under sub-rule (1) and sub-rule (2) of Rule 131 of the Income-tax Rules, 1962 (‘the Rules’), the Director General of Income Tax (Systems), with the approval of the Board, hereby specifies that the following Forms that shall be furnished electronically and shall be verified in the manner prescribed under sub-rule (1) of Rule 131:—
Form
Description
Form 42
Appeal against refusal to recognise or withdrawal of recognition from a provident fund
Form 43
Appeal against refusal to approve or withdrawal of approval from a superannuation fund
Form 44
Appeal against refusal to approve or withdrawal of approval from a gratuity fund
This notification shall come into effect from 22-11-2024.
Section 119, Read With Section 220 Of The Income Tax Act, 1961-Cbdt-Fixing Monetary Limit Of Income–Tax Authorities In Respect Of Reduction Or Waiver Of Interest Paid Or Payable Under Section 220(2)
Section 220(2) of the Income-tax Act (‘the Act’) deals with the consequences of non-payment of income tax by a taxpayer. As per Section 220(2) of the Act, if a taxpayer fails to pay the amount specified in any notice of demand under section 156 of the Act,the person shall be liable to pay simple interest at the rate of 1 % per month or part of the month for the period of delay in making the payment. Further, section 220(2A) of the Act empowers the Principal Chief Commissioner (Pr. CCIT) or Chief Commissioner (CCIT) or Principal Commissioner (Pr. CIT) or Commissioner (CIT) for reduction or waiver of the amount paid or payable under section 220(2) of the Act in the circumstances specified therein.
The Central Board of Direct Taxes, for the proper administration of the Act, hereby specifies the following monetary limits as below:
Income-Tax Authority
Monetary limits for reduction or waiver of interest
Pr. CIT/CIT
Upto Rs. 50 lacs
CCIT/DGIT
Above Rs. 50 lacs to Rs. 1.5 crore
Pr. CCIT
Above Rs. 1.5 crore
The powers of reduction or waiver of interest paid or payable u/s 220(2) of the Act shall continue to be subject to satisfaction of all the following conditions-
Payment of such amount has caused or would cause genuine hardship to the assessee,
Default in the payment of the amount on which interest has been paid or was payable under the sub-section was due to circumstances beyond the control of the assessee; and
The assessee has co-operated in any inquiry relating to the assessment or any proceeding for the recovery of any amount due from him.
The above shall come into effect from the date of issue of this circular.
Section 119 of the income tax act,1961-cbdt-condonation of the dealy under section 119(2)(b) in filing of form no. 10-ic and from no. 10-id for assessment years 2020-21, 2021-22 and 2022-23
In exercise of the powers conferred under section 119(2)(b) of the Income-tax Act, 1961, the Central Board of Direct Taxes by Circular No. 6/2022, dated 17-03-2022 and Circular No. 19/2023, dated 23-10-2023 condoned the delay in filing of Form No. 10-IC as per Rule 21AE of the Income-tax Rules, 1962 for Assessment Years 2020-21 and 2021-22 in cases where the conditions mentioned in the said Circulars are satisfied.
With a view to avoid genuine hardship to the assessee in exercising the option, under section 115BAA of the Act, read with Rule 21AE of the Rules or under section 115BAB of the Act, read with Rule 21AF of the Rules, the CBDT in exercise of the powers conferred under section 119(2)(b) of the Act, hereby authorizes: –
the Pr. Commissioners of Income Tax (‘Pr. CsIT’)/ Commissioners of Income Tax (‘CslT’) to admit and deal with the applications for condonation of delay in filing of Form No. 10-IC or Form No. 10-ID for Assessment Years 2020-21, 2021-22 and 2022-23 where there is a delay of upto 365 days.
the Pr. Chief Commissioners of Income Tax (‘Pr. CCsIT’)/Chief Commissioners of Income Tax (‘CCsIT’)/ Directors General of Income Tax (‘DsGIT’) to admit and deal with the applications for condonation of delay in filing of Form No. 10-IC or Form No. 10-ID for Assessment Years 2020-21, 2021-22 and 2022-23 where there is a delay of more than 365 days.
The Pr. CCsIT/CCsIT/DsGIT/Pr. CsIT/CsIT shall ensure that the following conditions are satisfied, while deciding such applications: –
The return of income for relevant assessment year has been filed on or before the due date specified under the section 139(1) of the Act.
The assessee has opted for taxation, u/s 115BAA of the Act in case condonation of delay is for Form No. 10-IC and u/s 115BAB of the Act in case condonation of delay is for Form No. 10-ID, in “Filing Status” in “Part A-GEN” of the Form of Return of Income ITR-6; and
The assessee was prevented by reasonable cause from filing such Form before the expiry of the time allowed and the case is of genuine hardships on merits.
No application for condonation of delay in filing of Form No. 10-IC or Form No. 10-ID shall be entertained beyond three years from the end of the assessment year for which such application is made. The time limit for filing of such application within three years from the end of the assessment year will be applicable for application filed on or after the date of issue of this Circular. A condonation application should be disposed of, as far as possible, within six months from the end of the month in which such application is received by the Competent Authority.
Circular No. 237/31/2024-GST [F.NO. CBIC-20001/6/2024-GST] Clarifying the issues regarding implementation of provisions of Sub- Section (5) and Sub-Section (6) in section 16 OF CGST ACT, 2017
Section 16 Amendments:
The Finance (No. 2) Act, 2024 extends the time for claiming Input Tax Credit (ITC) retrospectively, especially for taxpayers affected by wrongful ITC claims under Section 16(4) of the CGST Act.
ITC can be claimed under newly inserted provisions 16(5) and 16(6) for past periods where it was previously denied.
Refunds and Appeals:
No refund for taxes or ITC reversals due to violations of Section 16(4), even if ITC is now allowed under Section 16(5) or 16(6) (as per Section 150 of the Finance Act, 2024).
Taxpayers who were denied ITC due to Section 16(4) can now apply for rectification through a special procedure (Notification No. 22/2024, dated 8th October 2024).
Rectification applications must be submitted electronically within 6 months from the notification date.
Action for Rectification:
Taxpayers can apply for rectification if ITC was wrongly denied due to Section 16(4). The rectification will be handled by the officer who issued the original order and must be completed within 3 months.
In case of adverse effects from rectification, natural justice principles will apply.
Implementation:
The tax authorities must consider the new provisions when issuing orders or rectifications for cases involving wrongful ITC claims under Section 16(4).
Suitable notices should be issued to inform the public about these changes.
Limitations:
Rectification applications under Notification No. 22/2024 can only be filed for cases where ITC was denied under Section 16(4) but is now allowed under Section 16(5) or 16(6). Other cases must follow the regular process within the set time limits.
Further Clarifications: Any difficulties in implementation should be communicated to the Board for resolution.
Circular No. 238/32/2024-GST [F. NO. CBIC-20001/6/2024-GST] Clarification of various doubts related to Section 128A OF THE CGST ACT, 2017
Waiver of Interest/Penalty: Section 128A, effective from 1-11-2024, allows taxpayers to waive interest or penalty related to tax demands under Section 73 for FY 2017-18 to 2019-20, subject to certain conditions. The waiver applies only if the taxpayer fulfills the specified conditions.
Key Provisions:
Notification & Rule: Rule 164, effective from 1-11-2024, outlines the procedure for applying for the waiver. Taxpayers must pay the demanded tax by 31-03-2025 or within six months if re-determined by a proper officer.
Application Forms: Taxpayers must file applications in FORM GST SPL-01 or FORM GST SPL-02 on the portal by 31-03-2025 or within six months in specific cases.
Payment Process:
Payment Deadlines: Tax must be paid through FORM GST DRC-03 or ELR before the waiver can be processed. Any amounts due to Section 16(4) violations, now eligible under Sections 16(5) or 16(6), are excluded from the tax amount for waiver eligibility.
Waiver Eligibility: The waiver applies only to tax demands related to the specified periods and issues like erroneous refunds.
Processing Applications:
Applications are reviewed by the proper officer. If they meet criteria, the officer issues a waiver order (FORM GST SPL-05). If not, the application may be rejected (FORM GST SPL-07).
Appeals: Appeals can be filed against rejection orders but not against approvals. The appellate authority can modify the tax liability in such cases.
Additional Clarifications:
Rejection & Appeal: If a waiver application is rejected, the taxpayer may file an appeal. If the appeal is in his favor, the liability is adjusted in the Electronic Liability Register (ELR).
Final Decisions: Once an order is passed, the taxpayer must pay any remaining interest or penalties within three months to keep the waiver valid. This process ensures clarity on tax demands and provides taxpayers with an opportunity to avoid interest and penalty payments under specified conditions.
Further, the following issues with respect to availing the benefit of waiver of interest or penalty or both provided under Section 128A, are also clarified hereby: –
Tax Paid Before Section 128A Came into Effect: Tax paid before or after Section 128A came into effect will be considered for the waiver, as long as it was paid for the specified demand.
Tax Paid by Another Person on Behalf of Taxpayer: Amount recovered by tax officers from another person on behalf of the taxpayer can be counted as tax paid under Section 128A, if it was recovered before the notified date.
Interest/Penalty Adjustments: Interest or penalty amounts cannot be adjusted against tax dues for Section 128A benefits.
Tax Paid & Only Interest/Penalty Demand: If tax is already paid and only interest/penalty remains, Section 128A benefits can still apply, except for interest due to delayed returns or supply reporting.
Partial Waiver & Litigation: Partial payments for interest/penalty and litigation are not allowed; full payment is required for Section 128A benefits.
Multiple Tax Periods in One Notice: For a notice covering multiple periods, tax for the entire period must be paid, but the waiver only applies to the periods under Section 128A.
Erroneous Refund Demand: Tax must be paid in full (including for erroneous refunds) to avail waiver, but the waiver applies only to tax demand, not the erroneous refund penalty.
Appeals & Enhanced Tax Liability: If the tax liability is increased in an appeal, the taxpayer must pay the additional amount within 3 months for the Section 128A waiver to remain valid.
Pending SLP in Supreme Court: If an SLP is pending, the taxpayer must withdraw it and apply in FORM GST SPL-01 or SPL-02, with proof of withdrawal.
IGST & Compensation Cess: Section 128A applies to IGST and Compensation Cess, provided the full tax (including CGST, SGST, IGST, and Cess) is paid.
Irregular Transitional Credit: If wrongly availed transitional credit is involved and the demand is under Section 73, it’s covered under Section 128A.
Late Fees and Redemption Fine: Late fees and redemption fines are not covered by Section 128A, but penalties under sections 73, 122, and 125 are.
Payment Using ITC: Tax payments for Section 128A can be made using ITC, except for reverse charge or erroneous refund cases, which require payment in cash.
Reduced Tax Due to Retroactive Changes: Pay only the adjusted tax amount after applying the changes due to Sections 16(5) or (6) for transitional credit issues.
Filing Adjustments for DRC Payments: If tax is paid through FORM GST DRC-03, the taxpayer must adjust the payment using FORM GST DRC-03A before filing an application in FORM GST SPL-02.
It is requested that suitable trade notices may be issued to publicize the contents of this Circular.
Difficulty, if any, in implementation of the above instructions may please be brought to the notice of the Board.
Notification No. G.S.R. 644(E) [NO. 109 (F. NO. A-50050/2/20… Goods and Services Tax Council Secretariat, Group ‘A’ Executive posts recruitment (Amendment) Rules, 2024 – Amendment in Rule 7 and Schedule
The Goods and Services Tax Council Secretariat, Group ‘A’ Executive Posts Recruitment (Amendment) Rules, 2024 are as follows:
Title and Commencement: These are called the “Goods and Services Tax Council Secretariat, Group ‘A’ Executive Posts Recruitment (Amendment) Rules, 2024” and will come into force from the date of publication in the Official Gazette.
Amendments:
Rule 7: Add “Other Backward Classes” after “Scheduled Tribes”.
Schedule Changes:
For the Director post (Serial No. 1), the requirement “is necessary” in column (13) is changed to “is not necessary”.
For the Deputy Secretary post (Serial No. 2), the requirement “is necessary” in column (13) is changed to “is not necessary”.
For the Under Secretary post (Serial No. 3), the requirement “is necessary” in column (13) is changed to “is not necessary”.
Corrigendum G.S.R. 652(E) [F. NO. 190354/149/2024-TO (TRU-II)-PART-I CBEC], Dated 22-10-2024, Section 9 of the Central Goods and Services Tax Act, 2017
In the Notification No. 09/2024-Central Tax (Rate) dated 8th October 2024, the term “any property” in serial number 5AB, column (2), line 12 is corrected to “any immovable property”.
Corrigendum to Circular No. 237/31/2024-GST [F.NO. CBIC-20001/6/2024- GST, dated 25-10-2024, Clarifying the issues regarding implementation of provisions of Sub- Section (5) and Sub-Section (6) in section 16 of CGST ACT, 2017
The following is added to the end of para 4 of the circular:
“The restriction on refunds under Section 150 of the Finance (No. 2) Act, 2024 does not apply to refunds of pre-deposits made by the taxpayer under Section 107(6) or Section 112(8) of the CGST Act, if the appeal is decided in the taxpayer’s favor.”
Notification No. 26/2024–CENTRAL TAX [G.S.R. 713(E)/F. NO CBIC-20001/8/2024-GST], Dated 18-11-2024, Section 39 of the Central Goods and Services Tax Act, 2017-Furnishing of Returns- Extension of due date to furnish form GSTR-3B for month of October 2024, for registered person having specified principal place of business.
The Commissioner, based on the GST Council’s recommendation, extends the deadline for filing FORM GSTR-3B for October 2024 until November 21, 2024, for registered taxpayers whose principal place of business is in Maharashtra or Jharkhand.
Filing of Financial Statements of Producer Companies within 60 days of Annual General Meeting
The Ministry of Corporate Affairs has notified that Producer companies shall file their Financial Statements with the Registrar within 60 days of the annual general meeting, as per section 378ZA(10) of the Companies Act,2013. Additional fee logic changes in Form AOC-4 are expected to be deployed in the next week to enable filing within 60 days with nominal fee.
RBI
Reporting of Foreign Exchange Transactions to Trade Repository
The Reserve Bank of India has expanded the reporting requirements for foreign exchange contracts. Authorised Dealers are now required to report all foreign exchange spot, cash, and tom deals to the Trade Repository of Clearing Corporation of India Limited (CCIL), ensuring completeness of transaction data. Starting February 10, 2025, inter-bank FX contracts must be reported in hourly batches, while client FX contracts exceeding USD One Million (USD 1,000,000) and USD Fifty Thousand (USD 50,000) must be reported by May 12, 2025, and November 10, 2025, respectively. Dealers must ensure the accuracy of transactions and reconcile outstanding balances with the Trade Repository.
Operational Framework for Reclassification of Foreign Portfolio Investment to Foreign Direct Investment (FDI)
The Reserve Bank of India (RBI) has informed that the the Central Government has notified the Foreign Exchange Management (Non-debt Instruments) Rules, 2019, which require that foreign portfolio investors (FPIs) and their investor group limit their investments to less than Ten (10%) of a company’s total paid-up equity capital on a fully diluted basis, if this limit is breached, FPIs must either divest their holdings or reclassify them as Foreign Direct Investment (FDI), An operational framework for this reclassification has been provided in the Circular, and AD Category – I banks are tasked with facilitating the reporting of such transactions. The directions are effective immediately.
Other Laws
Onboarding Process on the Trade Receivables Discounting System Description
The Ministry of Micro, Small and Medium Enterprises has issued a notification wherein:
All companies registered under the Companies Act, 2013 (18 of 2013) with a turnover of more than Rs. 250 crore (two hundred and fifty crore rupees) and all Central Public Sector Enterprises shall be required to get themselves onboarded on the Trade Receivables Discounting System platforms, set up as per the notification of the Reserve Bank of India.
The onboarding process on the Trade Receivables Discounting System platforms shall be completed by 31st March 2025
SEBI (Bankers to an Issue) (Amendment) Regulations,2024
The Securities and Exchange Board of India has notified amendments in the SEBI (Bankers to an Issue) Regulations, 1994 wherein Regulation 2 and 3 has been amended as specified therein and these regulations may be called SEBI (Bankers to an Issue) (Amendment) Regulations, 2024. They shall come into force from immediate effect.
Disclaimer: Information in this note is intended to provide only a general update of the subjects covered. It is not intended to be a substitute for detailed research or the exercise of professional judgment. KNM accepts no responsibility for loss arising from any action taken or not taken by anyone using this publication. Updates are for the period 30.11.2024.